

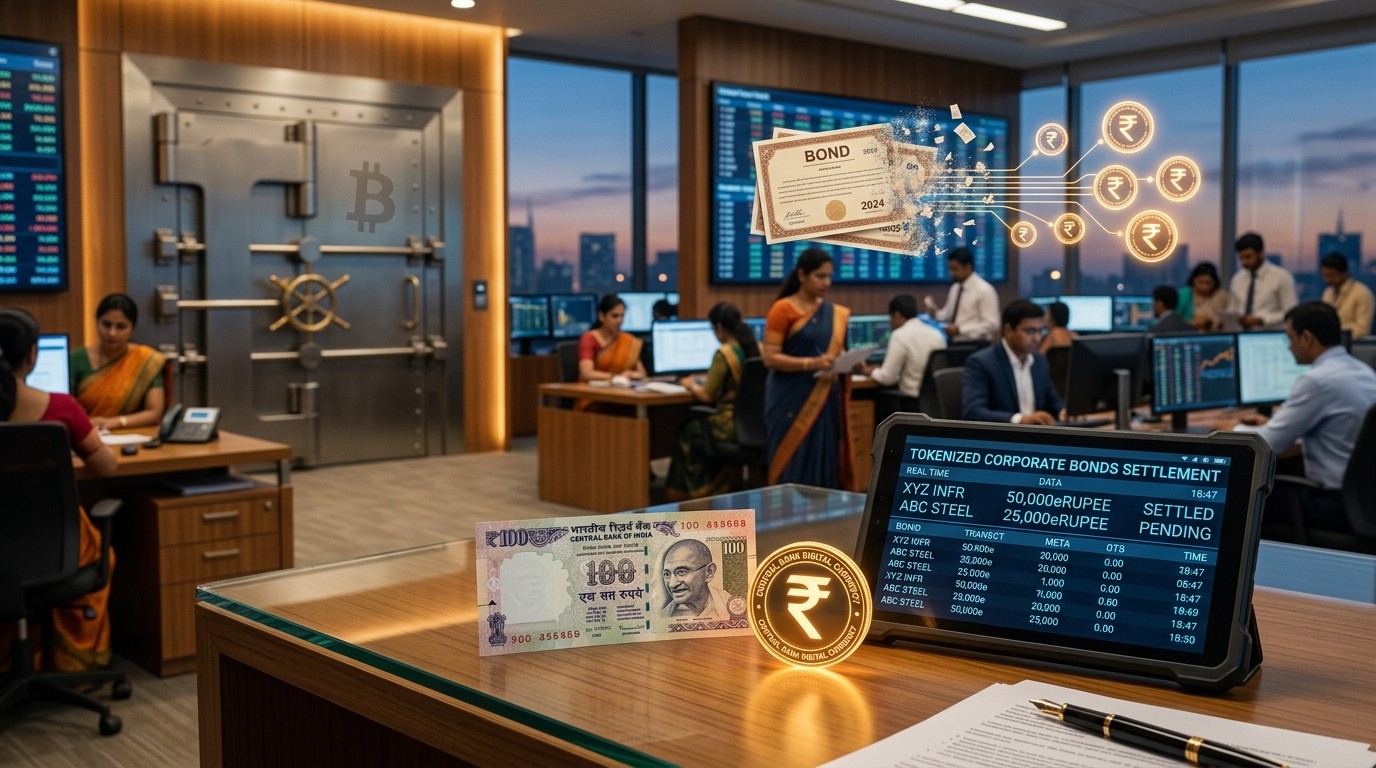
India Crypto Rules: RBI Caution And Tokenization Bet

India is not banning crypto outright, yet the central bank still will not bless private coins. Tokenized bonds are moving. Compliance notices are landing. The part nobody has settled is what happens to your holdings if the split hardens.
Financial market analysis from 04/10/2026. Market conditions may have changed since publication.
Anyone trading from India already knows the country never quite picked a lane. Tax rules exist. Anti-money-laundering duties exist. A dedicated statute covering the whole market does not. Banks have been nudged away from private coins and privately issued stablecoins. At the same time, tokenized certificates of deposit and corporate bonds are settling against central-bank money in live pilots. If that sounds contradictory, it is, and the contradiction is deliberate. I have watched enough policy cycles to know that “we like the rails, not the speculative ticket” is a sentence regulators reach for when they want innovation without giving up the monopoly on money.
Why Caution Still Sits at the Center of India Crypto Policy
The governor’s remarks at the Kautilya Economic Conclave did not invent a new doctrine. They restated one. India remains cautious on cryptocurrencies. The underlying technologies get a warmer welcome. Distributed ledger technology and tokenization were named outright. So was the idea that the central bank is already using some of that machinery internally and through public-private work. Crypto, as a private monetary claim, stays in the cautious column.
Three worries keep showing up, and they are worth separating because people often mash them into one vague fear of “volatility.”
- Monetary sovereignty: who gets to issue what people treat as money.
- Monetary policy: whether a parallel asset weakens the transmission of rates and liquidity tools.
- Capital flows: whether a borderless instrument punches holes in controls that emerging economies still use on purpose.
There is a fourth idea that sounds academic until you sit with it. Officials call it the singleness of money. Different forms of money denominated in the same currency should keep the same value and stay interchangeable. A bank deposit, a note in your pocket, and a balance at the central bank are not identical objects, yet a rupee is a rupee. That sameness is a public good. It is also easy to take for granted until something else starts calling itself money and trading at a discount, a premium, or a wobble.
Private crypto and privately issued currencies can break that sameness if their backing, their settlement, or their market price drifts away from sovereign money. I do not think every token tries to be money. A lot of them are speculative chips, governance claims, or access tickets. The policy problem starts when a token is used, or marketed, as a cash substitute. Once households and firms begin to hold it as a store of value that competes with deposits, the central bank is no longer only watching a trading fad. It is watching a rival claim on the unit of account.
Financial innovation should keep settlement finality, financial integrity, and the singleness of money. Efficiency is welcome. A second, wobbling rupee is not.
Central bank framing, paraphrased from the October address
That framing also explains the swipe at domestic-payments arguments. India already runs a fast, cheap retail system. Arguing that a private coin is required to pay a shopkeeper in Mumbai is a hard sell in a country where phone-based transfers are ordinary. The harder problem, officials keep saying, is cross-border. Remittances, trade invoices, and correspondent-banking friction are where the old pipes still creak. Their preferred answer is not a free-floating private asset. It is links between regulated systems, and central bank digital currency where that can be made to work.
Singleness of Money Is Not a Slogan
Let me slow down on this, because it is the concept people skip. Imagine two banknotes, one slightly torn, both accepted at the tea stall for the same price. Now imagine a private digital claim that says it is “rupee-like” but settles only on a specific platform, only during certain hours, and only if a reserve account somewhere offshore is intact. The shopkeeper might take it on Tuesday and refuse it on Wednesday. That is a crack in singleness. Small at first. Expensive if it spreads.
Stablecoins are the obvious stress case. A token pegged to a dollar or a rupee can look like cash until the peg slips, the reserve is questioned, or redemptions queue. Emerging-market central banks are especially sensitive here. They already manage inflation expectations and exchange-rate pressure. A widely held private coin that leaks across the border is, from their chair, a capital-flow instrument wearing a payments costume. Perhaps the most interesting part of the October remarks is how little time was spent on price charts. The worry is institutional, not aesthetic.
In my experience reading these speeches, the phrase “cautious” is doing a lot of work. It is not “banned tomorrow.” It is also not “come build your exchange inside the perimeter and we will cheer.” It leaves room for tax, for reporting, for enforcement against platforms that ignore the rules, and for a standing preference that banks stay clear. Internal government papers reported over the summer pointed to a policy lean toward prohibition for regulated institutions’ exposure. No comprehensive ban has been passed. Trading continues. That gap between preference and statute is where the market actually lives.
What the Speech Did Not Do
It did not announce a new tax. It did not name a prohibition bill. It did not walk back pilots on tokenized securities. Speeches like this are often temperature checks. They tell ministries, banks, and fintech teams which direction still has air cover. Right now the air cover is for ledgers that record regulated claims, settled in central-bank money, with identity and compliance attached. The air is thinner for coins whose main feature is that no public authority stands behind the unit.
Artificial intelligence got a mention alongside tokenization, which is a tell. The governor was talking about a toolkit, not a tribe. Tools that improve efficiency can stay, provided settlement is final, integrity holds, and the rupee remains one thing. That is a high bar. It is also a clearer bar than “we are studying the space,” which is what a lot of authorities say when they have not decided anything.
Payments at Home Versus Payments Abroad
Domestic retail is the easy rebuttal, and officials know it. A country that already moves small payments quickly does not need a new private monetary layer to buy groceries. Cross-border is the leftover problem. Correspondent chains are slow, fee-heavy, and opaque. Trade settlement with partners who want to reduce dollar intermediation is politically live. The proposed substitutes are central bank digital currencies and links between supervised payment systems, not an open crypto rail.
India’s retail payment brand has already pushed into foreign markets, including places such as Singapore, France, the UAE, Nepal, and Mauritius, with further links added this year. That matters. It shows the state would rather export a regulated interface than import a stateless one. Discussions with Russia on trade settlement via sovereign digital currencies fit the same pattern. You can disagree with the geopolitics. The design choice is consistent: public money on both ends, a corridor in the middle, compliance wrapped around the message.
Would a private stablecoin sometimes be faster in a sandbox? Maybe. Would it survive a stress week without someone asking who holds the reserves and under which law? That is the question the cautious camp refuses to skip. I find the refusal reasonable even when I think the resulting market is clumsier for ordinary traders.
Banks, Stablecoins, and the Quiet Perimeter
A reported push to keep banks away from private crypto and stablecoins, while letting regulated tokenized assets develop on a separate track, is the operational version of the speech. If commercial banks cannot hold, trade, or intermediate the private stuff, retail access depends on non-bank platforms, offshore apps, and peer arrangements. That does not kill demand. It does change who bears the operational risk, and it keeps the deposit system at arm’s length.
Stablecoins are the sensitive edge. A rupee-pegged private coin inside the banking system would look, to a supervisor, like a deposit substitute without the full deposit rulebook. A dollar-pegged coin used for trade could look like an informal capital account. Neither is a theoretical worry in a country that still manages the capital account with intent. The summer reporting that officials leaned toward prohibition for institutional exposure fits this perimeter logic. Legislation has not caught up. Guidance and supervisory nudges often move first.
A Reader’s Map of the Caution
If you only remember one distinction from the October remarks, make it this. The central bank is not arguing that databases are dangerous. It is arguing that private money is a different object from a better database. Tokenization can live in the second category. A free-floating coin that households treat as cash tries to live in the first. Policy can encourage one and restrain the other without being confused, even if the marketing departments of crypto firms would prefer a single narrative.
Caution stack, as the speech framed it:
  Sovereignty  -> who issues the unit
  Policy       -> rates and liquidity still bite
  Capital      -> borders still mean something
  Singleness   -> one rupee, one value, interchangeable
The Tokenization Track Is Not a Soft Ban
Here is where the story turns, and where a lazy summary goes wrong. Caution on private crypto is not the same thing as hostility to tokens. At the Global Fintech Festival in September, the same governor outlined work on programmable central bank digital currency, tokenized certificates of deposit, and corporate bonds settled through the wholesale digital rupee. That is not a side hobby. It is a market-structure project.
Certificates of deposit issued through a unified markets interface are being used to study how a financial market behaves when the cash leg is digital central-bank money. From there the work moved, with the securities regulator, into corporate bonds. The securities side can sit on distributed-ledger records. The cash side settles in sovereign digital money. That combination is the point. You get programmable records without asking investors to trust a private coin as the settlement asset.
On 10 September the securities regulator said its Demat 2.0 pilot for tokenized corporate bonds had launched successfully. Ownership and lifecycle events can be recorded on ledger infrastructure. Cash still clears in central-bank money. A few related transactions have already put real size on the board. The first digital-rupee-settled tokenized bond deals covered ₹1,025 crore across three issuances. One public-sector financier raised ₹500 crore. A major engineering group issued another ₹500 crore. A smaller financing house completed ₹25 crore.
Those bonds did not become cryptocurrencies. Read that twice if you trade for a living. They remain ordinary regulated securities. Contractual rights, coupon, maturity, recourse to the issuer: unchanged. Tokenization changes how ownership is recorded and how settlement is coordinated. It does not sprinkle a new monetary species onto the cap table. I like this distinction because the marketing world keeps blurring it. A tokenized bond is a bond with a different filing cabinet. A private coin is a claim whose value depends on belief, liquidity, and sometimes a reserve you cannot audit on a Tuesday afternoon.
What the Bond Pilots Actually Test
Strip the ceremony and the pilots are asking practical questions. Can issuance, allocation, and settlement share a clock? Can a coupon instruction fire without a stack of reconciliations? Can a regulator see the register without waiting for a batch file? Programmable settlement is attractive to back offices long before it is attractive to Telegram channels. That may be why it is moving while spot-crypto legislation is not.
Scale is still pilot scale. ₹1,025 crore is meaningful for a demonstration and small next to India’s corporate bond stock. Demos fail in boring ways: identity mismatches, holiday calendars, a participant whose core system cannot speak the new protocol. Success here means the next issuance is dull. Dull is a compliment in market infrastructure.
There is also a political economy point. Issuers in these deals are established names, not anonymous founders. Investors are inside the securities perimeter. If something breaks, the contract is still a bond contract. That is a very different failure mode from an offshore exchange freezing withdrawals. Supervisors can like the first experiment and dislike the second without contradicting themselves.
| Track | What officials seem to want | What is live now |
| Private crypto | Caution, limited bank exposure, AML perimeter | Trading under tax and reporting rules, no full statute |
| Stablecoins, private | Keep them away from regulated balance sheets | No broad domestic endorsement |
| Tokenized securities | Ledger records, central-bank cash leg | CD and corporate-bond pilots, Demat 2.0 |
| Retail digital rupee | Sovereign cash, programmable pilots | Benefit-transfer trials, convertibility to deposits |
| Cross-border | Linked regulated systems, CBDC corridors | Payment links abroad, exploratory trade talks |
Look at that table for a second. The country is not frozen. It is sorting. Assets that look like securities stay in the securities world, with a better settlement asset. Assets that look like private money stay outside the hug of the banking system. Retail users sit in between, paying tax on virtual digital assets and watching platforms get compliance letters.
Programmable Rupees and Targeted Transfers
The digital rupee project has kept moving while the private-coin debate loops. In August the government announced a benefit-transfer pilot using the central bank digital currency in Chandigarh and Dadra and Nagar Haveli, tied to a food-security scheme, with a start date of 14 August. Programmable features are being explored for targeted government transfers. The retail digital rupee is meant to keep the legal status of sovereign currency and to convert into bank deposits.
Programmability is the phrase that makes civil-liberties people sit up, and they should. A transfer that can only be spent on a defined purpose is useful for leakage control. It is also a design that can be misused if the rule set grows without a clear limit. I do not think the pilot itself answers that tension. It does show the state wants a digital cash instrument it can aim, rather than a public chain it cannot. Whether households treat the retail digital rupee as a daily wallet or as a novelty will depend on merchant acceptance and on whether it feels simpler than the payment apps they already trust.
Wholesale use is the cleaner near-term win. Bond settlement does not need a tea stall to accept a QR code. It needs a handful of institutions, a legal finality rule, and a cash token that cannot go bankrupt overnight. That is why the corporate-bond work feels more advanced than the retail story, even though retail gets the headlines.
Cross-Border Ambition Without a Private Coin
September brought another thread. India and Russia began talking about trade-settlement infrastructure built on central bank digital currency links. Pair that with the overseas reach of the domestic instant-payment system and you see a strategy. Export the regulated rail. Experiment with sovereign digital corridors where partners are willing. Leave the private crypto route as a risk to be contained, not a highway to be paved.
Will those corridors beat existing banking links on cost? Too early. Corridors fail on legal harmonization more often than on software. Still, the intent matters for anyone pricing the “crypto will fix remittances” pitch in this market. The official alternative is being built in public, slowly, with names attached.
Compliance Is the Live Statute
Absence of a comprehensive crypto law is not absence of law. Since March 2023, virtual digital asset service providers have sat inside the prevention of money-laundering framework. Platforms that serve Indian customers are expected to register with the financial intelligence unit as reporting entities, even if they have no office in the country. Reporting, record-keeping, and the rest of the anti-money-laundering kit apply. Official notices still warn that crypto assets and non-fungible tokens are not regulated as investment products, and that losses may have no regulatory remedy.
Tax law has been more explicit than market-structure law. The Income Tax Act, 2025, in force from 1 April 2026, defines virtual digital assets, including cryptocurrencies and tokenized assets. Recognition for tax is not the same thing as endorsement. It is the state saying: if you made money, we can see the category. Traders sometimes treat a tax line as legitimacy. Supervisors do not.
Enforcement tightened again in September. The intelligence unit issued notices to 15 virtual asset providers for operating without meeting registration requirements. Names in that batch included several offshore venues. The action asked for applications and web addresses reachable by Indian users to come down. The legal theory is simple enough. Obligations follow the service offered in India. A missing local office is not a shield. Whether every URL actually disappears is a cat-and-mouse question. The signal to payment firms and banks is less fuzzy. Touch an unregistered venue and you inherit a problem.
- Register if you serve Indian customers, office or no office.
- Keep records and file the reports the laundering statute expects.
- Do not assume a tax definition equals a license to solicit.
- Expect takedown pressure if you skip the register and still market in.
- Separate tokenized regulated securities from exchange-traded private coins in your own compliance map.
That fifth item is the one finance teams botch. A ledger is not a business line. The same word, token, covers a bond in a pilot and a meme coin on an unregistered app. Policy is trying to pull them apart. Firms that keep them in one bucket will misread the next circular.
How This Lands on Traders and Treasurers
If you hold private crypto as an Indian resident, nothing in the October speech switched the tax switch or closed the market overnight. The 30-style flat treatment and the awkward loss rules of recent years, the reporting duties, the platform risk: still the operating environment. What changed is the clarity of the hierarchy. Sovereign digital money and tokenized regulated paper are projects. Private coins are tolerated under restraints, not cultivated.
For a corporate treasurer the hierarchy is useful. A tokenized certificate of deposit or a bond that settles in wholesale digital rupee may, over time, cut settlement friction without putting the company in the crypto-policy blast radius. That is a different conversation from “should we hold a coin on the balance sheet.” The second conversation remains a bad one if supervisors are telling banks to stay out. I would not volunteer a treasury for that argument.
Retail investors get the awkward middle. Access persists through platforms that comply, and through ones that might not for long. Price risk is unchanged by a speech. Legal risk is path-dependent. A future statute could codify the lean toward tighter limits. It could also freeze today’s compromise for years, because comprehensive bills are slow and coalitions are split. Betting the farm on either outcome is not analysis. It is a mood.
Why Prohibition Talk Has Not Become a Statute
Reports in July described a central-bank preference leaning toward prohibition, especially insulation of banks and financial institutions from holdings, trading, and other exposure to cryptocurrencies and privately issued stablecoins. As of 4 October, that preference is not a comprehensive enacted ban. The gap is the story of Indian crypto policy in miniature. Institutions hear “stay away.” Citizens still find markets. The finance ministry has to weigh tax revenue, enforcement cost, court risk, and the optics of a ban that would not fully bite.
Bans are blunt. They also migrate activity rather than erase it, which is an old lesson from capital controls everywhere. A cautious regime with registration, tax, and bank distance may be the politically durable option even if economists at the central bank would write a stricter memo. I suspect that compromise annoys both camps. Purists want a clean prohibition or a clean license regime. What they have is a corridor with walls that move.
The durable policy is rarely the tidy one. It is the one that lets the state keep the unit of account while the market keeps a taxable, monitorable fringe.
Tokenization Without the Costume Jewelry
There is a fashion in global finance to call every database upgrade a token. Some of that is real efficiency. Some of it is a costume. The Indian pilots are interesting because they keep the costume off the cash leg. Securities can be tokenized. Settlement money stays sovereign. That choice dodges the classic failure where a beautifully recorded asset cannot be paid for when the private settlement token breaks.
Finality is the unglamorous prize. In traditional systems, finality is a legal moment backed by a central bank and a rulebook. On open crypto networks, finality is probabilistic and social, which is fine for some uses and awkward for a bond covenant. By anchoring the cash side in the digital rupee, the pilots borrow finality instead of reinventing it. That is, to my eye, the adult version of tokenization. It will not trend on social feeds. It might still change how the next decade of Indian fixed income clears.
Secondary-market questions remain. A pilot issuance is not a liquid order book. Custody, repo, and default management have to be rewritten if the register is a ledger rather than a traditional depository entry. None of that is impossible. All of it is slower than a keynote slide. Anyone selling “instant global liquidity” off the back of these deals is selling ahead of the plumbing.
A Practical Split for Anyone Allocating Capital
I would draw the line in four buckets, and then refuse to mix them in a single risk memo.
- Sovereign digital cash. Retail and wholesale digital rupee. Policy-supported. Design still evolving. Not a speculative asset.
- Tokenized regulated claims. Bonds, certificates of deposit, maybe more paper later. Upside is operational. Credit risk remains the issuer’s.
- Compliant private-crypto exposure. Possible, taxed, platform-dependent, politically reversible. Size it like a risk budget, not like a payments revolution.
- Unregistered offshore access. The September notices are the warning label. Convenience is not a legal strategy.
Bucket three is where arguments get loud. Global prices do not wait for New Delhi. Indian residents who already hold coins will not unload because a conclave speech reused the word cautious. The rational response is narrower. Know the reporting line. Know that bank rails can tighten without a headline ban. Know that a tokenized bond pilot is not a green light for the rest of the ticker list.
What I Would Watch Next
Speeches set tone. The next evidence is administrative. Does the securities pilot add issuers beyond the first three, and do secondary transfers work without a special team on the phone? Does programmable benefit transfer stay a small geography or spread? Do more offshore platforms lose access after the batch of 15 notices, or does the traffic simply move to the next domain? Does a bill finally define market structure, or does tax-plus-laundering-law remain the de facto code?
I would also watch bank circulars more closely than conference panels. If supervised institutions get a sharper written limit on crypto and stablecoin exposure, the October language will have grown teeth. If tokenized bond settlement becomes a routine option in the primary market, the “we promote the technology” line will have grown a balance sheet. Tone without either outcome is just a good paragraph.
Cross-border pilots deserve a skeptical clock. Talks on sovereign digital settlement with a major partner can sit in working groups for years. A live corridor with volume, dispute rules, and sanctions screening would be news. A memorandum is a press release. There is a difference, and traders overpay for the second.
The Global Pattern This Fits
India is not alone in liking tokenization more than private money. Several large jurisdictions are trying to put securities on ledgers while keeping stablecoins in a narrow, fully reserved box, or outside the box entirely. The Indian version is stricter on the private-money side and more state-led on the cash side. That fits a country with an active capital-account framework and a payments system it considers a success.
Comparisons can mislead. A small open economy that wants to be a token hub has different incentives from a continental-scale market protecting monetary control. Copying the press release from somewhere else is how local fintech teams waste a year. The relevant constraint here is singleness, plus the ability to see flows. Anything that serves those constraints can get a pilot. Anything that threatens them gets a speech like the one on 3 October.
Common Misreads, Gently Corrected
First misread: “India is pro-crypto now because it tokenized bonds.” No. The bonds stayed bonds. Second: “India banned crypto.” No statute says that, and trading continues under tax and laundering rules. Third: “The digital rupee is a crypto coin with a flag on it.” It is sovereign currency in digital form, convertible to deposits, not a privately issued asset with a market cap. Fourth: “Registration notices are optional for foreign apps.” The September batch says the opposite. Service into the country is the hook.
A fifth misread is subtler. People hear “cautious” and assume paralysis. The bond numbers argue otherwise. ₹500 crore, ₹500 crore, and ₹25 crore are not paralysis. They are a preference for experiments that cannot be mistaken for a new currency. That preference can frustrate founders. It is still movement.
A Note on Language and Hype
I have found that half the confusion in this market is vocabulary. Call a depository upgrade a revolution and investors expect a price. Call a pilot a ban lift and they expect a bank account. The cleaner sentence is dull and accurate. India wants ledgers where they cut friction, sovereign money where settlement must be final, and a supervised perimeter around private coins that refuse to stay in the speculative corner.
If you write about this space, retire the single mood. The mood is split, on purpose. Praise the settlement experiment without pretending it blesses an unregistered exchange. Criticize the gray zone without pretending the pilots are fake. Readers can hold both ideas. Platforms that cannot are selling a product, not an explanation.
Policy filter: Does it preserve one rupee, final settlement, and a visible compliance trail? If yes, pilot. If it mints a rival money, caution.Where the Opportunity Actually Sits
Opportunity, if that word still fits, is mostly industrial. Firms that can connect issuer systems to a ledger register, handle whitelist logic, and reconcile a central-bank cash leg will have work. Custodians who understand both securities law and key management will have work. Retail exchanges pitching a payments revolution against an already fast domestic rail will have a speech to argue with.
There is a narrower opportunity in education. A lot of affluent investors still conflate “blockchain” with “coin I can sell on Sunday.” The bond pilots are a chance to show a use that does not require that conflation. Whether wealth managers take it is another matter. Product shelves love a simple story. This story has two shelves, and one of them is labeled caution.
Longer term, a successful wholesale digital rupee could pull more market plumbing onto programmable rails: collateral moves, on-chain covenants that are actually just better workflow, fractional institutional lots with cleaner registers. None of that requires a household to hold a private coin. That is the feature, from the central bank’s side, not a bug. Builders who need the private coin to justify the company will find the feature annoying. Builders who sell workflow may find a client.
Risks the Cautious Line Does Not Remove
Caution is not a shield against every failure mode. Tokenized pilots can still mis-record a beneficial owner. Programmable transfers can exclude someone who should have been paid. A digital rupee wallet can be phished just like any other app. Cross-border corridors can clash with sanctions law. And private crypto, precisely because it is not banned, can still produce consumer losses that the state has already said may have no remedy.
There is political risk too. A scandal at an unregistered venue would strengthen the prohibition camp inside government. A smooth year of bond pilots would strengthen the technology camp. Policy is not a fixed object. It is a committee that reads headlines. Anyone with exposure should assume the committee is still in session.
Currency-management risk sits underneath all of this. If private dollar-linked tokens became a household habit, the capital-flow worry would stop being theoretical. The October speech is an attempt to stay ahead of that habit, not a claim that the habit is impossible. Habits form in group chats faster than statutes form in parliament. That mismatch is why enforcement letters and bank guidance keep arriving between the big speeches.
Putting the October Message in One Place
So what, practically, did the central bank say? India is cautious on crypto because of sovereignty, policy transmission, capital flows, and the need for one interchangeable rupee. It will promote distributed ledgers and tokenization. It is already doing so inside its own walls and with partners. Domestic private coins are not required for domestic payments. Cross-border is the real gap, and the preferred tools are regulated links and sovereign digital money. Tokenized deposits certificates and corporate bonds can settle in wholesale digital rupee. Retail digital rupee pilots, including targeted benefit transfers, continue. Tax and laundering rules remain the live framework. Fifteen platforms were just told that serving India without registration is not a loophole.
That is a lot of policy in a short set of remarks, which is why summaries that pick only “cautious” or only “tokenization” both lie a little. The lie of omission is how this story gets traded on social feeds. The fuller version is less viral and more useful. Hold both halves.
I will leave you with the shopkeeper test, because it still organizes the rest. If a new instrument cannot be refused on Wednesday after being accepted on Tuesday, without a legal drama, it might be money. India already has money. It is trying to digitize the cabinet around that money, and to keep rival cabinets from calling themselves the same thing. Whether that attempt holds is the open question. The pilots say the cabinet project is real. The notices say the rival cabinets are still being measured for the door.
Markets hate open questions, so they will fill the gap with price. Policy will fill it with circulars. Between those two habits, the only sensible posture is specific. Know which bucket you are in. Do not borrow the optimism of the bond pilot to justify the risk of an unregistered coin, and do not borrow the caution on private money to dismiss a settlement upgrade that already has issuers, coupons, and central-bank cash behind it. The country is running both experiments in plain sight. Pretending there is only one is how people get surprised.
]]>A good investor has to have three things: cash at the right time, analytically-derived courage, and experience.


Japan Sanctions Garantex In New Russia Asset Freeze

California CEO Charged Over Restricted Servers Sent To China
Related Articles
Unsealing Epstein-Maxwell Case: What Lies Ahead?
The DOJ is pushing to unseal key exhibits from the Epstein-Maxwell investigations, but what truths will they reveal? Click to uncover the latest in this high-profile case.

Legendary Labs Jinlian Capital Merger Reshapes Web3 Prediction Markets
The worlds of crypto speculation, sports fandom, and regulated gaming just collided in a major way. Legendary Labs and Jinlian Capital have joined forces to build something bigger in prediction markets, but what does this mean for the future of decentralized forecasting? The details might surprise you...

Binance bStocks Surge: $143 Million Daily Volume Marks Bold Crypto Equity Push
Binance just dropped its bStocks product and the numbers are staggering - $143 million in average daily trading volume right out of the gate. But what does this mean for regular investors seeking stock exposure on crypto platforms? The early momentum raises big questions about the future of traditional markets meeting blockchain.