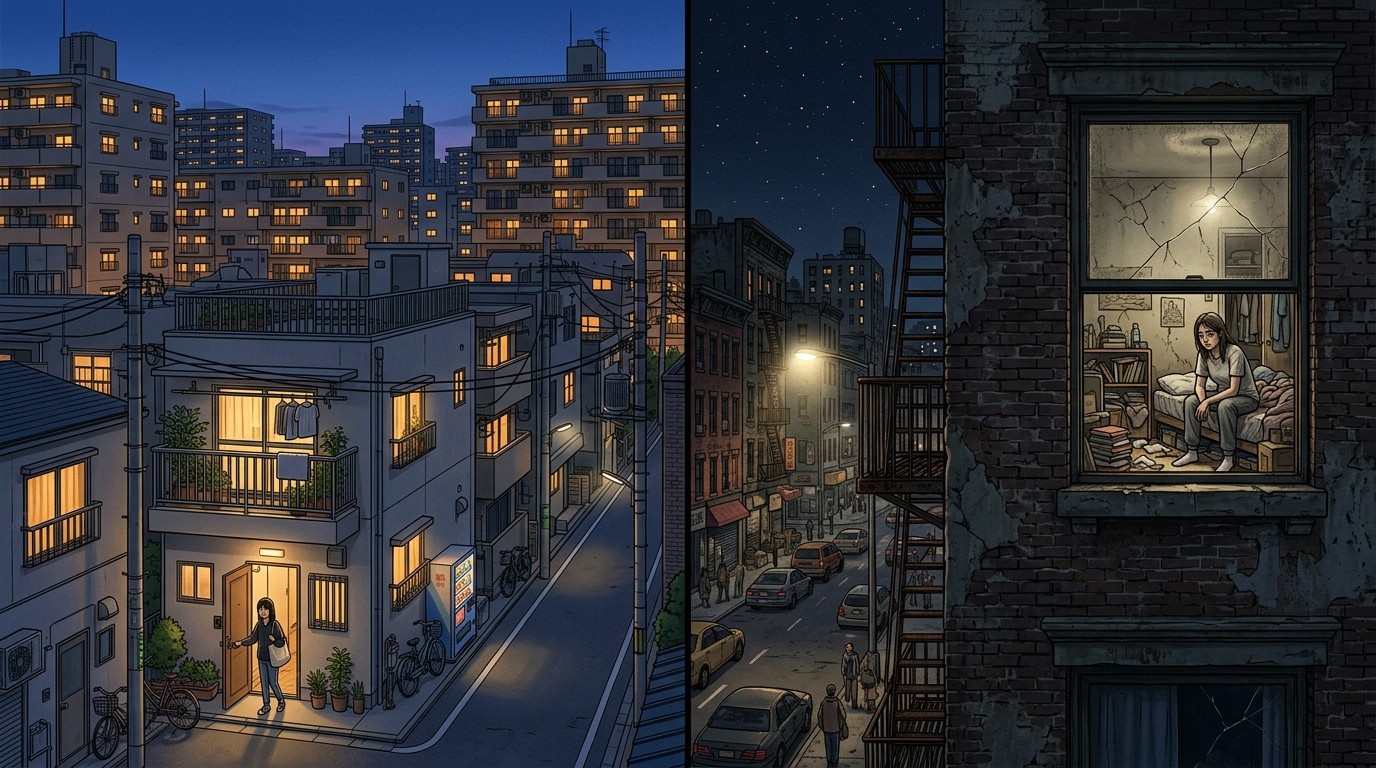

Picture January in a shared New York walk-up. The radiator clanks, the hallway smells faintly of old paint, and there is a hole in the bedroom wall large enough to watch the weather change. Snow does not stay outside. You have called about the leak more times than you can count. Nothing moves. Now set that scene next to a city with almost twice the people, where a one-bedroom often costs a fraction of the New York figure. I have watched friends treat that gap as a mystery of culture or luck. It is neither. It is the long result of how each place treats new homes.
Tokyo Metropolis holds about 14.27 million residents. New York City sits nearer 8.5 million. On paper, the larger city should be the more expensive one. It is not. In the mid-1990s a one-bedroom in Tokyo and a one-bedroom in New York both sat a little under $1,000 a month. By 2025 the New York average had climbed to roughly $4,400. The Tokyo figure was closer to $1,270. A softer yen explains part of the dollar gap. It does not explain the yen story. In local currency, Tokyo rents barely budged across three decades. New York rents nearly tripled.
Why Tokyo Apartments Stayed Within Reach
Housing prices are not a mood. They are the meeting point of people who want a roof and the number of roofs that exist. When demand rises and supply does not, the price does the adjusting. Tokyo spent decades letting the stock grow. New York spent decades making growth slow, local, and easy to stop. That single difference shows up in crumbling walls, vacant regulated units, and rents that feel detached from wages.
I keep coming back to a simple test. If a city adds people and jobs but refuses new apartments, someone has to lose. Usually it is the newcomer, the roommate who wanted a door of their own, or the landlord who cannot fund a repair because the legal rent will never cover the work. Tokyo did not abolish scarcity. It refused to treat scarcity as a permanent feature of city life.
Two Rents, Thirty Years Apart
The mid-1990s comparison is the cleanest way to see the split. Back then the two cities were not living in different price universes. A young professional in either place could look at a one-bedroom and see a similar monthly number. Then the paths diverged.
New York’s climb was not a single shock. It was a slow squeeze. Each year a few more households competed for a stock that barely expanded. Landlords with market-rate units raised asking rents because they could. Tenants in regulated stock stayed put because moving meant jumping into that market. The result is a city where the advertised one-bedroom and the lived-in one-bedroom feel like different products.
Tokyo’s path looks almost dull by comparison. Rents in yen drifted. They did not explode. A weaker currency later made the dollar price look even softer to an American reader, which is worth stating plainly so nobody treats the exchange rate as the whole story. Strip the currency effect away and the local rent still failed to triple. That is the part that matters for anyone asking why Tokyo apartments cost less.
A city can be enormous and still keep rents from running away, but only if the number of homes is allowed to rise with the number of people.
Housing economists, summarizing three decades of rent data
Perhaps the most interesting aspect is how ordinary the Tokyo outcome looks once you stop treating high rent as a law of big cities. Size alone did not force the New York number. Policy did a lot of the forcing.
Population Was Never the Full Excuse
People reach for population first. Tokyo is bigger, denser in places, and famous for packed trains. If crowding explained rent, Tokyo should win the expensive contest. It does not. New York is smaller and, for a one-bedroom, far costlier.
Demand still matters. Both cities attract workers, students, and anyone who wants a thick job market. Both have limited land in the core. The difference is what happens after demand shows up. One system treats a new apartment as a normal outcome of the rules. The other treats it as a special request that neighbors, boards, and landmarks can stall.
I have found that renters sense this before they can name it. In a tight market, every listing feels like a contest. In a market that kept building, a listing is still a budget decision, just not a crisis. Tokyo is not cheap by Japanese standards. It is simply a place that absorbed millions without producing New York’s mix of sky-high asking rents and buildings left to rot.
A Housing Stock That Actually Grew
Between 1963 and 2013, Tokyo’s housing stock nearly tripled, reaching about 7.36 million homes. That is not a slogan. It is a physical count of doors, kitchens, and leases. Since the 1960s the stock has kept that multiplied shape, while New York’s housing stock grew on the order of 20 to 30 percent.
Starts tell the same story in annual form. From 1995 to 2015 Tokyo averaged about 155,000 housing starts a year. It still starts roughly 130,000 homes annually. New York, by contrast, added roughly 50,000 homes in 2025. One city is replacing and adding at a pace that can absorb newcomers. The other is adding a fraction of that, then acting surprised when rents jump.
| Measure | Tokyo | New York City |
| Population scale | About 14.27 million in the metropolis | About 8.5 million in the city |
| One-bedroom, mid-1990s | A little under $1,000 | A little under $1,000 |
| One-bedroom, 2025 | About $1,270 | About $4,400 |
| Typical one-bedroom size | About 430 square feet | About 590 square feet |
| Recent annual additions | Roughly 130,000 starts | Roughly 50,000 added in 2025 |
| Long-run stock growth | Nearly tripled since the 1960s | About 20 to 30 percent |
Read that table slowly. The larger city built more, kept rents flatter in local terms, and did it with smaller typical units. None of those lines require a miracle. They require permission to build, and a tax and cultural habit of replacing old stock instead of freezing it in place.
Zoning That Lets Homes, Shops, and Light Work Share a Block
Japan does not invent a new land-use code for every neighborhood fight. The national government defines 13 standard zones. Those zones are used across the country. Homes, shops, and light industry can sit on the same blocks in many of them. A project that follows the written rules can go ahead as-of-right. Neighbors do not get a veto just because they dislike the shadow or the new faces.
That top-down design cuts both ways. A national system could tighten rules as easily as it loosens them. Japan’s version has repeatedly loosened them when housing was the goal. The point is not that every national code is wise. The point is that predictable rules, applied the same way from one ward to the next, remove the custom bottleneck.
Mixed use sounds abstract until you walk it. A bakery under apartments is not a zoning exception. It is a normal block. That pattern puts daily errands closer to the front door, which matters when the apartment itself is modest. Small homes work better when the street does some of the living.
- Rules are written once, not renegotiated on every lot.
- Projects that match the code do not wait on a political calendar.
- Shops and homes are allowed to share blocks instead of being sealed apart.
- The same framework can be eased when the housing count falls behind.
In my experience, renters rarely care what the zone is called. They care whether a vacant lot becomes apartments in three years or in fifteen. Tokyo’s code is built for the first outcome.
New York’s Review Path Works in the Opposite Direction
New York City zoning often does the reverse. A site that needs a rezoning enters the Uniform Land Use Review Procedure. The path is long, public, and easy to fail. About 40 percent of private rezoning proposals do not get approved. That is not a rounding error. It is a standing tax on anyone who wants to add homes where the map currently forbids them.
Discretion sounds fair in a hearing room. Everyone gets a turn. On a balance sheet it means delay, lawyers, and a real chance of a no. Developers price that risk in, or they walk. Either way, fewer apartments reach the market. The ones that do arrive later and cost more to entitle, which shows up in the rent.
There is a human side to the same machinery. A neighbor who fears construction has a formal route to slow it. A renter who needs a unit next year does not have an equal route to speed it up. The process is loud about objections and quiet about the people who never get a lease because the building was never approved.
Landmarks, Historic Districts, and the Missing Buildings
About 27 percent of Manhattan’s lots sit under restrictive landmark rules. Historic districts add new buildings at roughly one-sixth the rate of other lots. Preservation has a real purpose. Some streets are worth keeping. The trouble starts when preservation becomes the default answer to housing demand across a huge share of the borough where people most want to live.
A frozen facade does not freeze the number of households. Jobs still cluster. Students still arrive. The demand spills into the remaining buildable lots, then into outer boroughs, then into higher rents everywhere the map still allows a listing. Landmark status protects a look. It does not protect a renter from a $4,400 one-bedroom.
I am not arguing that every old building should vanish. I am arguing that a city cannot landmark its way to affordability. When new construction in protected areas runs at a fraction of the normal rate, the shortfall has to land somewhere. It lands in the monthly payment.
The Odd Problem of Empty Regulated Apartments
Scarcity in New York is not only a story of unbuilt towers. It is also a story of apartments that exist and sit dark. The 2019 Housing Stability and Tenant Protection Act capped rent increases on vacant rent-stabilized units and limited how much of a renovation landlords can recover. The intent was tenant protection. The side effect is arithmetic.
Take a unit renting near $700 that needs about $100,000 of work to meet code. If the legal rent after vacancy cannot repay that work, many owners leave it empty. Nearly 57,000 rent-stabilized apartments were vacant in 2025. That is a small city of missing homes, sitting inside a city that claims it has nowhere to put people.
This is the part that feels upside down when you are the person with the hole in the wall. The building is decaying because the rent does not fund the repair. The rules then make a full renovation on turnover a losing bet. So the hole stays, or the unit goes dark, and the market-rate stock next door gets more expensive because those missing units never re-enter the search.
A rent cap that ignores the cost of bringing a unit back to code does not create a home. It creates a vacancy with a lock on the door.
Recent rent guidelines have pushed further in the same direction. A freeze on roughly one million stabilized apartments helps the tenant who already has the lease. It does not add a single new home. Analysts expect more units to sit empty while prices on non-stabilized apartments keep rising. The renter watching snow come through the bedroom wall is not saved by another frozen year. She is stuck in the building the freeze helped hollow out.
Smaller Apartments Lower the First Rung
Size is the quiet lever. A typical Tokyo one-bedroom runs about 430 square feet. A New York one-bedroom runs about 590. Forty percent more floor area is not a small design preference. It is a higher minimum price, because land, structure, and finishes scale with the box.
Smaller units drop the barrier for single renters and early-career workers who want their own door. Not every household needs a large one-bedroom. Many need a clean, legal, private room with a kitchen that works. Tokyo builds that product as a normal part of the stock. New York spent decades making it hard.
A 400-square-foot minimum dating to 1987, plus zoning rules known as the Dwelling Unit Factor, pushed average unit sizes up. The City of Yes package only eased those limits in December 2024. That is decades of missing small apartments, which is another way of saying decades of missing cheaper leases. A rule that sounds like a quality floor can function as a price floor.
- Set a large minimum size, and the cheapest legal unit gets expensive.
- Force a high average unit size across a building, and studios get squeezed out.
- Ease those rules late, and you are catching up to a stock Tokyo already has.
Would I want to live in 430 square feet forever? No. Would I rather have 430 square feet of my own than a leaking share of a larger room? For a lot of people in their twenties, the answer is obvious. Tokyo took that answer seriously.
Buildings That Are Allowed to Retire
Japan’s tax code depreciates a wooden house over 22 years. The average Japanese home is demolished at about 32 years old. In the United States the comparable age is closer to 70. Old stock in Tokyo gets replaced with newer, often denser buildings. Old stock in New York is more likely to be preserved, patched, or left in a gray zone where neither a full fix nor a replacement quite pencils.
Fast turnover is not automatically charming. A 32-year cycle can feel disposable, and some of what gets torn down had character. The housing result, though, is hard to argue with. Newer buildings meet current codes. Denser buildings put more households on the same land. The city does not spend half a century negotiating with a structure that was never meant to last that long.
There is a cultural piece here, and I do not want to flatten it into a spreadsheet. Japanese buyers have long treated houses more like depreciating goods than like heirlooms. American buyers often treat the structure as the asset that should rise forever. When policy and tax rules agree with that second view, demolition becomes a fight. When they agree with the first, replacement becomes ordinary. Rents follow the ordinary path more than they follow the sentimental one.
Replacement habit, simplified:
  Shorter tax life
  Earlier demolition
  Newer code compliance
  More homes on the same parcel
None of that requires loving concrete. It requires accepting that a city of millions cannot museum every wooden house and still house the next million people at a tolerable rent.
Factory-Built Homes and the Speed Problem
Pace is not only a zoning question. It is a construction question. One Sekisui House plant produces about 20 houses a day. Roughly 13 percent of new Japanese homes are prefab or modular. That share will not solve every urban site, especially tight infill lots with odd shapes. It does show a supply chain that treats housing as something you can manufacture, not only something you can argue about.
New York has started to experiment with modular construction. The share is still small. Factories need steady orders. Steady orders need permits that arrive on a schedule. If entitlement is a coin flip, a plant cannot plan a year of panels. The zoning delay and the construction delay feed each other.
I keep a soft spot for the unglamorous version of this. A repetitive floor plate, a known kitchen, a window that meets code, repeated until the block is full. It will not win a design award. It will win a lease. Tokyo’s volume, year after year, is built from that kind of repetition as much as from any single landmark tower.
What the Gap Feels Like on a Tuesday Night
Statistics are clean. Leases are not. A New Yorker splitting a crumbling apartment is not thinking about housing starts in 2004. She is thinking about the drip, the roommate schedule, and whether a raise will cover a place with intact walls. A Tokyo renter in a 430-square-foot one-bedroom is thinking about rent that did not triple, a building that is more likely to be recent, and a street where shops sit under homes because the zone allows it.
The lifestyles diverge in small ways that add up. Smaller private units mean fewer forced shares, which means fewer fights about dishes and fewer people stuck with a landlord who will not fix a hole because three names are on the lease. Shorter building lives mean fewer decades of deferred maintenance stacked on top of each other. More annual starts mean a listing is less likely to be the only tolerable option in the postcode.
None of this makes Tokyo a bargain paradise. Local wages, commutes, and deposit customs still shape the monthly reality. The claim is narrower, and stronger for being narrow. A much larger city kept one-bedroom rents from doing what New York rents did. The method was more homes, smaller homes, faster replacement, and rules that do not hand every project to a veto.
Rent Freezes Do Not Patch a Hole in the Wall
It is tempting, when rents hurt, to freeze them. The politics are simple. The tenant in place feels relief. The tenant not yet in place does not get a vote in that particular hearing. Over time the stock responds. Owners delay work. Vacancies in regulated units linger when the rehab math fails. Market rents on everything else rise because the frozen stock is not expanding.
A freeze on about a million stabilized apartments is a large intervention. It is also a zero on the supply line. Housing economists have been blunt about this trade for years. Protecting incumbents without adding units shifts the pain to newcomers and to the physical condition of the regulated buildings. Tokyo’s record is the contrasting case: affordability that came from volume, not from a ceiling on the old price.
Would a New York freeze feel different if the city were adding 130,000 homes a year? Maybe the politics would be calmer, because the outside option would be a real apartment rather than a bidding war. We do not have that counterfactual. We have the city that froze and the city that built.
What Transfers, and What Does Not
Copying a country is a bad plan. Earthquake codes, land ownership, and the way buyers think about resale value are not plug-and-play. A national zoning map would be a political earthquake of its own in the United States, where land use sits with cities and towns. The useful transfer is the set of mechanisms, not the flag.
- Let code-compliant buildings proceed without a custom political approval.
- Allow small apartments as a normal product, not a hardship waiver.
- Stop rules that make a legal renovation of a vacant unit a financial loss.
- Treat replacement of worn buildings as ordinary, especially where demand is thick.
- Measure success by homes started, not by hearings held.
City of Yes moved the unit-size rules in late 2024. That is a late, partial step toward the small-apartment market Tokyo already runs. It does not unwind landmark coverage, it does not shorten ULURP into something predictable, and it does not fix the vacancy trap in the stabilized stock. Partial steps still count. They just do not close a thirty-year gap by themselves.
There is a fairness argument underneath the technical one. The household that bought a brownstone in 1998 captured a windfall as scarcity deepened. The household that arrived in 2022 pays the scarcity. A system that blocks new homes quietly transfers wealth from future renters to current owners. Tokyo’s looser rules did less of that transfer. That is a distributional fact, not only a construction fact.
A Closer Look at the Dollar Gap and the Yen Gap
Anyone comparing the two cities in dollars has to keep the currency in view. The yen’s weakness inflates the apparent bargain for an American salary. That is real, and it should not be waved away. A traveler or a remote worker paid in dollars will feel Tokyo as cheaper than the local wage story alone suggests.
The local story is the stricter test. Tokyo rents in yen did not march upward the way New York rents in dollars did. If the entire gap were an exchange-rate trick, the yen series would have climbed and the dollar series would have looked soft only on the conversion. That is not what happened. Supply showed up in the local price.
I mention this because international comparisons get sloppy fast. A viral chart can mix currencies, unit sizes, and city boundaries until the lesson disappears. Here the boundaries are clear enough. Metropolis versus city. One-bedroom versus one-bedroom. Mid-1990s versus the middle of this decade. Stock that tripled versus stock that grew by a quarter or so. The direction survives the caveats.
Demand Still Has a Job to Do
None of this says demand is fake. New York’s job mix, its role in finance and media, and its draw for new arrivals all push willingness to pay. Tokyo’s job market is enormous too. Both cities can support high rents if they choose not to build. The choice is the variable.
A useful mental split is this. Demand sets the ceiling people will pay when homes are scarce. Supply decides whether that ceiling is tested every year. Tokyo kept adding enough homes that the ceiling was tested less often. New York tested it constantly, then added rules that made some of the existing homes unusable.
Remote work shuffled some demand after 2020, and both cities felt it in different neighborhoods. The long comparison still holds, because the divergence started in the 1990s, not in the pandemic. A two-year shock does not explain a thirty-year split in rent growth.
Owners, Renters, and the Repair Bill
Talk of supply can sound like it ignores the person already paying rent. It should not. The hole in the wall is a supply story and a maintenance story at once. When regulated rents cannot fund a code repair, the tenant does not get a cheaper good apartment. The tenant gets a cheap bad apartment, or an empty one next door that nobody can rent.
Market-rate owners in a scarce city have the opposite problem. They can raise rents because alternatives are thin. Some reinvest. Some do the minimum, because the listing will fill either way. Scarcity is kind to neglect. Abundance is not. A landlord in a city adding 130,000 homes a year has to keep the unit competitive. That is an underrated consumer protection.
So the Tokyo pattern is not only “more building.” It is a competitive pressure that makes a leaking wall a business problem rather than a tenant’s private misfortune. I would take that pressure over a freeze that leaves the wall untouched.
Density Without the Cartoon
People hear “build more” and picture a wall of towers on every side street. Tokyo’s actual pattern is more repetitive mid-rise, more replacement of low houses with small apartment buildings, more mixed streets. Density there is often a five- to ten-story fact, not a science-fiction skyline. New York already has towers. What it lacks is permission for ordinary buildings on ordinary lots.
The one-sixth construction rate in historic districts is the cartoon in reverse. Those areas look preserved because they are not adding homes. The cost of that look is paid by someone renting three neighborhoods away. A city can keep a set of truly singular blocks and still let the rest of the map do its job. It cannot keep a quarter of Manhattan’s lots in a slow lane and expect rents to behave.
Mixed-use zoning helps the feel of density too. A street with a ground-floor shop is busier, safer in the ordinary sense, and more useful to the person in the small apartment upstairs. Separating uses, then wondering why residential blocks feel dead after 7 p.m., is a choice. Tokyo’s 13-zone framework makes the livelier choice the default.
A Practical Reading for Anyone Pricing a Lease
If you are comparing cities for work, do not stop at the headline rent. Ask what the unit size is, how old the building is, and how many similar units hit the market each month. A $1,270 one-bedroom at 430 square feet is a different product from a $4,400 one-bedroom at 590 square feet. The per-foot gap is still large. The lifestyle gap is large too, because one of those numbers often buys privacy and the other often buys a share.
If you already live in the expensive city, the personal move and the civic move are different. Personally, people trade space, commute, or roommates. Civically, the rent comes down only if the stock grows and the vacant regulated units come back. Voting for another freeze feels like help. Counting building permits is the stricter kindness.
Affordability, roughly: new homes + repaired vacancies + smaller legal units = rents that do not have to triple.That line is blunt on purpose. Every extra review, every minimum size, every cap that blocks a rehab, pushes the other way. Tokyo did not stumble into flat rents. It stacked the decisions that produce them.
The Long Drift, Not a Single Law
It would be tidy to blame one statute. The record is a stack. Flexible national zones. As-of-right approvals. Smaller units. Fast depreciation and earlier demolition. Factory output. High annual starts for twenty years and more. On the other side: discretionary rezonings that fail often, landmark coverage that slows new buildings to a fraction, minimum sizes that lasted for decades, and a 2019 law that left tens of thousands of stabilized units empty.
Each rule had a constituency. Neighbors wanted a say. Preservationists wanted facades. Tenant advocates wanted caps. Some of those aims are understandable one at a time. Together they produced a city where a one-bedroom costs more than three times the Tokyo equivalent, and where a bedroom wall can open to the weather while regulated units sit vacant nearby.
Tokyo is not a rebuke of city life. It is a rebuke of the idea that city life must come with crumbling regulated stock and runaway market rents. The larger city chose volume. The smaller one chose process. Rents recorded the choice.
What I Would Watch Next
Three numbers would tell me if New York is actually changing course. Annual homes added, compared with a six-figure pace rather than a rounding error. Vacant stabilized units, and whether that 57,000 figure shrinks because rehabs pencil again. And the share of new buildings that are small apartments, now that the old size rules have eased. If those three move, rents have a chance. If they do not, another freeze will be offered as comfort, and the hole in the wall will still be there in January.
On the Tokyo side I would watch whether the national zones stay loose. A top-down system can reverse. The habit of building is strong, but habits follow rules. The reassuring fact is that the rules have been loosened more than once when housing was the stated goal. That is a political muscle New York has barely used.
For renters deciding where to put a year of their life, the lesson is already usable. A big city can stay within reach. It does so by treating apartments as something the rules are supposed to produce, not something the rules are supposed to interrogate. Tokyo apartments cost less because the city kept making more of them, smaller and newer, while New York spent the same decades making each new door harder to open.
The snow through the bedroom wall is not a quirk of big-city character. It is what scarcity looks like up close. The cheaper one-bedroom in the larger city is what steady supply looks like up close. Between those two pictures, the policy choice is not subtle, even if the hearings are.