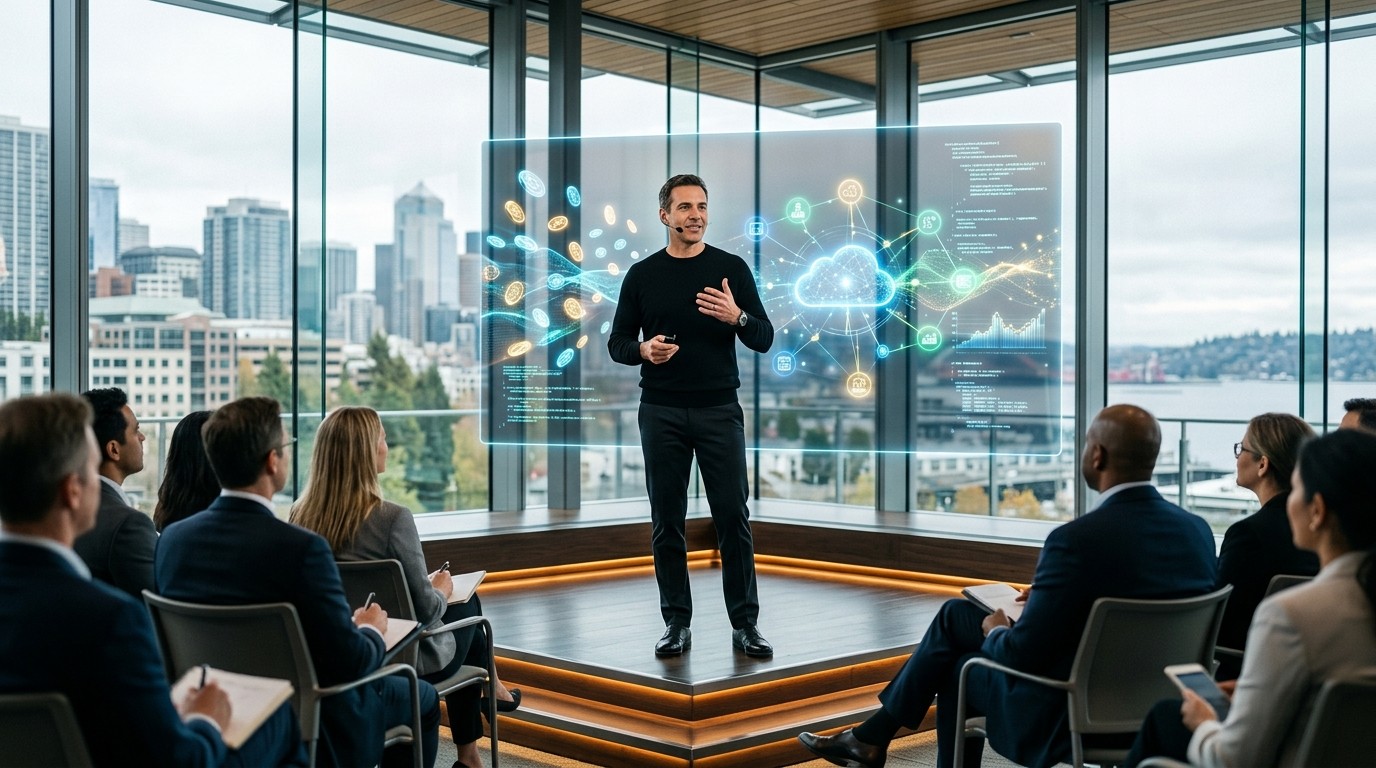

I keep coming back to a small scene from late September. About fifty executives from large customers sat in a downtown Seattle pavilion and got something rare: an open floor with the person who has run the company since 2014. One of them asked a plain question. What can you actually do to help us adapt? The answer was not a product demo. It was a word that sounds softer than it is. Diffusion. Tools have to spread inside the enterprise, from the top, from the bottom, and through the middle. That is the whole bet, and it is harder than the last one he won.
Nearly four years after generative systems jumped from lab curiosity to board agenda, the company still does not own the chip layer, the model layer, or a consumer agent that people talk about at dinner. It rents the chips. It partners on models. It sells a workplace assistant that many finance teams still treat as an optional add-on. Market value sits near four trillion dollars. The stock, even after a sharp third-quarter bounce, was up only about 7 percent for the year through Friday. Peers and the broader tech index have run ahead. Calendar years of beating the wide market stopped in 2023. That gap is the story.
The Second Reinvention Is a Business Model Problem
The first reinvention is already folklore. A perpetual license machine became a subscription machine, and infrastructure rent became the growth engine. Customers were allowed to mix in rival software instead of being locked to one stack. Dealmaking added a game studio, a professional network, and a code host. Electrical engineering training plus a willingness to drop sacred habits turned a legacy label into a cloud compounder. Investors remember that sequence because it worked. Memory is also a trap. The next shift does not look like the last one.
This time the unit of sale is not a seat alone. It is a token, a slice of compute that models burn while they read, write, search, and retry. Consumption pricing means revenue moves with intensity of use. That can expand the addressable market. It can also scare budget owners who have spent a decade learning how to forecast a fixed license. I have found that finance teams forgive a messy product faster than they forgive a bill they cannot model. That tension sits under every slide about agents.
On the July earnings call, the case was framed as further expansion of total addressable market. Fair enough. Expansion only counts if customers consume because the work got better, not because a meter was left running. A security executive put the internal test bluntly: if customers consume, value was added; if they do not, it was not. That is a cleaner standard than a seat count. It is also a standard the company has not fully lived under yet.
Leaders who are hands-on are able to change. Otherwise they move from press event to press event. You have got to be in it.
Remarks to customer executives in Seattle
Why the Cloud Playbook Does Not Copy Cleanly
Cloud won because the alternative was worse. Running your own servers aged badly. Migration had a clear villain and a clear savings story. Artificial intelligence does not arrive with that kind of villain. A decent spreadsheet still works. A careful analyst still beats a sloppy agent. The pain is diffuse, which is why the Seattle answer leaned on diffusion inside the firm rather than on a single killer app.
There is another mismatch. Infrastructure rental scales with capacity you already own. Application value scales with trust. A developer might forgive a coding assistant that suggests a bad function. A controller will not forgive an agent that files the wrong scenario into a board pack. The company wants both crowds. Coding factories for technical teams. A workplace companion for everyone else. Those are different sales, different failure modes, and different pricing nerves.
Perhaps the most interesting aspect is how openly the model is being rewritten in public. Fixed price per user per month looked elegant when the assistant mostly drafted email. It looks brittle once the assistant opens tools, loops, and burns compute to finish a multi-step job. Executives have said the economics no longer support the best outcome inside a flat monthly fee. That admission is rare. Most vendors pretend the old meter still fits.
What the Seat Numbers Actually Say
The productivity suite still has a commercial base above 450 million. The paid assistant sits at about 30 million seats, priced near an extra 30 dollars per person each month. Do the ratio. Roughly one paid assistant seat for every fifteen commercial productivity users. That is not failure. It is also not ubiquity. A portfolio manager who holds the shares put it in practical terms: the product needs more maturity before anyone can be sure of the right bundle or the right price.
I read that gap as a distribution advantage that has not yet become a habit advantage. The suite is already on the desktop. The assistant is not yet the default way work gets finished. Habit is slower than install. Anyone who has watched a new collaboration tool sit unused in a toolbar knows the difference.
| Signal | Rough scale | What it implies |
| Commercial productivity base | Above 450 million | Distribution is already won |
| Paid assistant seats | About 30 million | Attach rate still early |
| Assistant add-on price | About 30 dollars per user monthly | Fixed fee under pressure |
| Coding assistant users | About 50 million, from 26 million | Consumption shift can grow usage |
| Share price year to date | About 7 percent | Market wants a clearer hit |
Numbers like these age fast. Treat them as a snapshot of a transition, not as a scoreboard. The direction matters more than the precise count. Seats prove access. Tokens will prove intensity. Investors who only watch seats will misread the next two years.
GitHub as the Dress Rehearsal
The coding assistant was the early sensation. A collaboration with the lab Microsoft backed in 2019 produced a tool, launched in 2021, that could draft parts of applications from public code. Then the market moved. AI-native editors and rival coding agents took share while the original product lagged the pace of change. That slip cost position. It also produced a usable lesson.
Pricing was reset this year to track computing demand. Some customers balked. By July the user count had reached 50 million, up from 26 million last October, roughly one in five people on the code host. Sales growth for the coding assistant accelerated 60 percent from the prior quarter once the new model was in effect, with meaningful consumption revenue attached. The operating lead described it as a product that went out and learned. Lessons were shared with other teams eyeing the same meter.
Is a coding tool a fair proxy for a finance assistant? Only partly. Developers already think in usage. They will pay for speed if the diff is good. A marketing manager does not think in tokens. Still, the rehearsal matters. It showed that a price change can anger people and still grow the base if the output is obvious. Cowork, the newer usage-billed product for larger assignments, is the attempt to export that logic beyond engineers.
- Code assist came first, then agentic coding, then talk of a software factory, all inside roughly a year.
- Customers are being nudged to run their own factories and spend more to produce code faster.
- Non-technical staff are the second audience, via a companion that drafts apps and acts like a teammate.
- Consumption revenue showed up after the coding price change, which is the proof point sales teams now cite.
Usage Billing and the Fear of an Open Meter
The internal name is usage-based billing. The first product under that banner, Cowork, takes large productivity jobs and shows its progress while it works. Thousands of customers were already paying and using it by the July call, according to company remarks. An analyst who recommends the shares compared the setup to what happened when a rival coding agent moved to consumption: token bills jumped. The same jump is possible here. Possible is not promised.
A vice president at an advisory firm that tracks the vendor was more cautious. Budget owners worry that switching the feature on lets people drain the account. There is no clean way, yet, to prove each session paid for itself. That objection is not technophobia. It is procurement. I would rather hear that objection early than discover it in a renewal quarter.
The chief executive has used the tool himself. On a podcast recorded after the September gathering, he described asking it for a supply chain optimization spreadsheet with multiple scenarios. The artifact, in his telling, was strong. Anecdotes from the top are useful color. They are not a cohort study. The product has to survive a Tuesday afternoon in a shared inbox, not only a prepared demo.
Pricing tension, simplified:
  Fixed seat  = predictable, capped upside
  Token meter = variable, harder to forecast
  Hybrid      = where most enterprises will actually land
Models Under the Same Roof
Uncertainty also sits with the model group. The executive hired in 2024 to lead artificial intelligence initiatives previously co-founded a lab later acquired by a search giant. The hire landed as the old alliance cooled. Last year the company lost exclusive cloud status with that lab. This year the intellectual property license became non-exclusive. A very large investment remained. Preferential treatment did not. The company still describes itself as the primary cloud partner. Primary is not exclusive. The difference is worth real money.
The in-house group has shipped models for coding, images, and reasoning, and recently claimed a speech-to-text system as the most accurate real-time transcription available. Independent leaderboards still place raw general intellect behind the two labs most buyers name first. That gap is not fatal if the company means what it has started saying: priority is a frontier ecosystem, not a single frontier model, so value spreads across industries and countries. A June note on the chief executive’s own site made that argument explicit.
There is a practical upside to building models and applications together. The productivity engineering group has reported better performance from the internal transcription models at a lower price, with tighter feedback as products ship. In March, commercial and consumer assistant engineering were pulled into one organization after adoption stayed sluggish. A different executive took the experience layer. Model work stayed with the 2024 hire. Org charts are not strategy. They do show where blame and credit are being separated.
Priority has to be a frontier ecosystem, not just a frontier model, so value flows across companies, industries, and countries.
At the September assistant event, a slide said the product could connect to every model, with logos for the leading labs and the in-house effort. Multi-model is a sensible hedge. It is also an admission that no single bet is safe. Buyers like choice. They also like a default that does not make them pick. Getting both is the product problem hiding inside the partnership problem.
Rivals Walking Onto Old Turf
Model leaders are no longer staying in the model business. Cybersecurity, customer service, and other line-of-business tools are showing up from labs that, three years ago, mostly sold an interface. In January, as one coding agent gathered momentum, internal teams studied how it chained tools to finish jobs. Deals were being lost. A person familiar with the review, speaking privately, described a close look at a rising competitor. The company declined to comment on that account. The marketing lead for workplace artificial intelligence did say the moment clarified the economics: a fixed monthly price could not keep delivering the best outcome.
That is the uncomfortable part of platform power. Distribution used to be the moat. Now a lab with a strong model can ship a narrow app and peel off a workflow without owning the suite. The response cannot only be a better sidebar. It has to be a system that already holds the files, the permissions, the identity, and the audit trail. If that system taxes every ambitious task, customers will route the ambitious tasks elsewhere.
- Hold the system of record so work does not leave.
- Price intense jobs on usage so quality is not capped by a flat fee.
- Keep a credible in-house model so negotiations with labs stay balanced.
- Prove, in the renewal, that consumption matched a result someone can name.
Azure Is the Quiet Lead
Lost in the assistant debate is the infrastructure business. Renting chips to developers who train and serve models is already large. It does not require the workplace product to be loved. It requires capacity, power, and a sales motion enterprises already trust. In my experience, investors underweight this when the narrative is about chat windows. Capacity is less glamorous. It is also where a lot of the near-term profit pool sits.
The risk is concentration and cycle. If model customers slow spending, or if they split workloads across more clouds now that exclusivity is gone, growth rates cool even while the assistant story improves. The two businesses can diverge. A strong rental quarter does not prove the application layer. A weak rental quarter does not disprove it. Separating those threads is the only honest way to read the print.
Local inference adds a third thread. A Windows and device event set for Wednesday in San Francisco was framed, in the invitation, as a conversation on how on-device intelligence shapes the next chapter of the personal computer. On-device work changes the token math. Some tasks never hit the meter. Others still do, because the hard reasoning stays in the cloud. Hybrid devices could defend the franchise. They could also complicate the consumption story sales teams just started telling.
How Wall Street Is Scoring the Transition
The share has not beaten the broad market in a calendar year since 2023. A third-quarter rally narrowed the gap and did not close it. Relative lag is not a verdict on the franchise. It is a verdict on timing. Mega-cap peers tied more cleanly to chips, or to a consumer model people open every day, have had an easier story to tell. This story has more moving parts: cloud rental, a cooling lab partnership, an assistant still earning its attach rate, and a price model in mid-rewrite.
One bank upgrade argued that investors underestimate how the company is differentiating. Differentiation here is less about a single benchmark win and more about where the work already lives. Identity, documents, mail, meetings, code hosts, security consoles. If agents become useful, they will be useful inside those surfaces. That is a real claim. It is not yet a measured one. Measurement is what the next few renewal cycles have to supply.
Investor checklist: attach rate + token yield + renewal commentary + cloud mixI would watch four comments on calls more than the headline growth rate. First, whether assistant seats are expanding inside existing accounts or only landing as pilots. Second, whether usage billing is additive or simply re-slicing the same budget. Third, whether customers describe the tool in a workflow, not in a feature list. Fourth, whether cloud growth still leans on a narrow set of model customers. Any one of those can flip the mood faster than a keynote.
The Hands-On Standard He Set for Himself
Back in the pavilion, the answer closed on leadership behavior. People at the top of organizations change the outcome only if they use the tools. Otherwise they collect events. The line was aimed at customers. It lands on the speaker too. Posting about deliberate pacing in model development, then speaking about safety fears at a summit days later, is a more public posture than the cloud years required. Public posture is not the same as being in the product. The September line admits that.
Deliberate pacing is a double edge. Too fast, and safety incidents or hollow demos burn trust. Too slow, and the labs shipping agents every month define the category. A company this large cannot win a pure speed contest against a startup. It can win a trust contest if the agent respects permissions, cites its sources, and fails in a way an auditor can explain. That is a less exciting sentence than a benchmark chart. It may be the sentence that keeps the suite at the center.
An advisor who still sees the current chief executive as the right person to run the shift said the pattern is recognizable. Situations get identified. A plan follows. The plan gets worked. The caveat was honest: artificial intelligence carries more unknowns than the cloud transition did. Market dynamics are messier. A plan is not a moat. It is a start.
What Success Would Look Like in Practice
Forget the slogan about factories for a moment. Success, in operating terms, would look boring. A procurement lead can forecast the token bill within a band. A team lead can point to hours returned on a recurring task. A developer stays in the hosted coding tool because the suggestions survive review. A security buyer pays by intensity and can show the board a drop in open incidents. None of that requires a model that tops every public leaderboard. It requires the work to move.
Failure would also look boring, which is why it is dangerous. Seats stay flat. Usage spikes once, then gets shut off after a surprise invoice. Coding share keeps leaking to sharper agents. Cloud growth depends on one or two labs that now have other options. The stock grinds while peers get the multiple. No single quarter would announce that outcome. It would arrive as a series of small renewals.
There is a middle path I think is the likely one. Hybrid pricing. A base seat for light use. A meter for heavy agent work. In-house models for cost and privacy. Outside models where the quality gap is still wide. Devices that handle the easy tasks locally so the cloud bill does not shock a mid-size customer. That path is less clean than the cloud story. It can still compound if execution stays dull and consistent.
A Note on Pacing, Safety, and Trust
Safety talk can sound like a delay tactic. Sometimes it is. Sometimes it is the only way a regulated buyer will turn a feature on. Banks, hospitals, and public agencies do not adopt at the speed of a demo account. The September remarks about deliberate pacing, paired with summit comments on safety fears, read to me as an attempt to keep those buyers in the conversation while labs race. Whether the attempt is credible depends on incident response, not on phrasing.
Trust also covers the partnership residue. A non-exclusive license and a primary cloud role can coexist. They do not feel the same to a customer choosing where to build. If the flagship models are available everywhere, the reason to build here has to be integration, price, or data gravity. Integration is the honest pitch. It should be made without pretending the old exclusivity still exists.
Where the Organization Still Has to Tighten
Sluggish assistant adoption prompted the March regrouping of commercial and consumer engineering. That kind of merge usually means the experience felt fragmented. Users do not care which internal team owns a button. They care that the button behaves the same in mail, in a document, and in a meeting. Fragmentation is a tax on diffusion, the very thing the Seattle answer named as the goal.
Model teams and application teams under one roof can shorten feedback. They can also blur accountability. Who owns a bad answer in a customer demo, the model or the product shell? The tighter collaboration described by the productivity engineering lead is a good sign only if someone can still say no to a launch. Speed without a veto produces the kind of assistant people try once.
Culture is the quieter variable. The first reinvention asked veterans to stop defending the license. This one asks them to stop defending the seat. Some will. Some will price-protect the old bundle until a rival invoice forces the issue. Hands-on leaders, the standard set on that stage, are the ones who notice the protectionism early.
Reading the Next Device Event Without the Hype
Local intelligence on the personal computer is easy to oversell. A faster on-device model does not, by itself, create a new category. It does change cost, latency, and privacy for a slice of tasks: transcription in a meeting room, summarization of a local file, a first draft that never leaves the machine. Those are real. They are not the whole agent story. Hard planning still wants a larger model and a live set of tools.
If the Wednesday conversation in San Francisco ties devices to the same identity and permission model as the suite, it supports the ecosystem claim. If it is a spec sheet with a new key on the keyboard, it will fade by the following week. I tend to judge these events by whether a buyer can describe the workflow afterward without using the word revolutionary. Plain language is a better filter than applause.
Capital, Patience, and the Size of the Bet
A company near four trillion dollars does not get to hide a miss inside a small segment. Assistant revenue can grow quickly in percentage terms and still be a rounding error next to cloud and the suite. That scale cuts both ways. There is room to fund the rewrite. There is also no excuse if, two years on, the attach rate has barely moved and token revenue is a footnote. Size raises the burden of proof.
Patience from long-term holders is the asset earned in the last decade. It is not infinite. The portfolio manager’s call for product maturity before a final view on pricing is a polite version of a clock. Maturity, here, means fewer surprises in the bill and more repeatable wins in the workflow. Neither shows up in a single keynote.
Could someone else have run this transition? Maybe. The record from 2014 onward is the reason the benefit of the doubt still exists. Cloud, subscriptions, and a willingness to sell alongside rivals were not obvious inside the old culture. The open question is whether that adaptability extends to a meter that makes revenue lumpier and to a product category where smaller labs set the pace. Adaptability is a trait. It is not a guarantee.
A Practical Frame for Operators Watching From Outside
If you buy software from this vendor, the useful move is narrower than the macro debate. Pilot the heavy agent on a task with a before-and-after. Cap the first month of usage. Ask for an export of what the tool touched. Compare that with the fixed seat you already pay. Keep the coding assistant and the workplace assistant on separate scorecards. They will not mature on the same calendar.
If you compete with the suite, assume distribution remains the hard part. A better model does not automatically dislodge a file system people already live in. It can dislodge a workflow that feels optional. Customer service macros, security triage, internal reporting. Those are the doors. The suite defends them only if the in-house agent is good enough that leaving feels like extra work.
If you hold the shares, separate the rental business from the application experiment in your own notes. Give the experiment a clock measured in renewals, not in news cycles. Usage billing is the tell. If customers consume and stay, the second reinvention is underway. If they consume once and clamp down, the seat era has not actually ended.
When customers consume, value was added. If they do not consume, it was not.
Security product leadership, on the internal test
The Part That Still Feels Unresolved
Four years is a long time in this market and a short time inside a company this size. The early partnership created a head start that later frayed. Coding share was given up and partly clawed back under a new price. The assistant is present and not yet pervasive. In-house models are useful in spots and not yet the default intellect buyers name. That mix can still resolve in favor of the incumbent. It can also resolve as a very profitable cloud landlord that missed the application layer. Both outcomes are on the table. Pretending otherwise is how holders get surprised.
What I trust least is any sentence that treats tokens as a metaphor. They are a bill. Bills change behavior. The company that learns to make the bill feel earned, inside tools people already open, will have done the harder reinvention. The company that only rents the chips will still be large. It will not have answered the question asked in that pavilion.
Diffusion, bottom up and top down and through the middle, is not a slogan you can ship. It is a pattern you either see in the renewal data or you do not. Hands on, or press event to press event. He set the standard himself. The next year is the test of whether the standard applies at the top of his own house.