

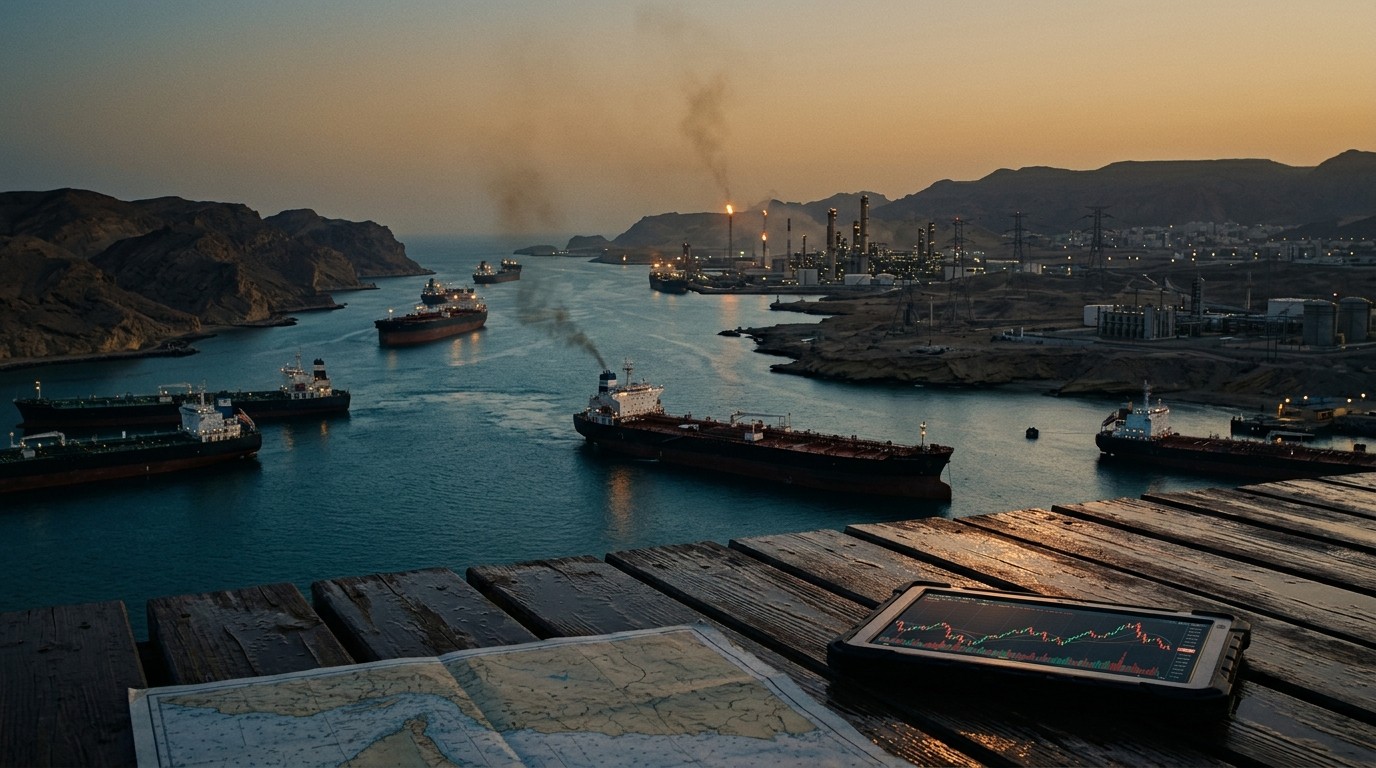
Iran Energy Rationing And Hormuz Stalemate Shake Oil

Tehran is asking households to cut power so factories can keep running, while mediators say the nuclear track is stuck. Oil through the strait just plunged. The part markets are not pricing yet is what happens if this freeze lasts past November.
Financial market analysis from 07/10/2026. Market conditions may have changed since publication.
I was halfway through a late coffee when the oil tape did something it only does when the story behind the barrel gets personal. Not a clean spike. A stutter. A few dollars up, a fade, then another lurch as traders tried to decide whether a rationing speech in Tehran was domestic theater or a real signal that the energy file had moved from negotiation to endurance. If you have watched this corridor long enough, you know the difference. Theater moves headlines. Endurance moves freight rates, insurance quotes, and the quiet conversations refinery buyers have after the close.
The latest turn is blunt. Iran’s president has asked ordinary people to cut electricity, gas, gasoline, and water so the production cycle does not break. He has framed that sacrifice as the price of standing up to Western pressure. At the same time, mediation channels are being described as stuck. Washington’s line, as relayed through regional reporting, is that nothing meaningful moves until the nuclear file moves, and that the strait is no longer the bargaining chip it once was. Tehran answers that it remains ready for a balanced deal, provided national interests are not crossed. Between those two sentences sits a waterway that still carries a huge share of the world’s seaborne crude, a currency that has been sliding hard, and a run of incidents against commercial vessels that nobody serious can wave away.
Why A Household Power Cut Is Now A Market Story
Energy rationing inside a major producer used to be background noise for equity desks. It is not background anymore. When a government tells citizens that cultural halls and sports complexes may go dark so factories can keep the lights on, it is admitting that the constraint has reached the real economy. Not the slogan economy. The one that pays wages, loads tankers, and keeps refineries from tripping offline.
I have found that markets misread these speeches in a predictable way. They treat the patriotic line as the whole message and skip the operational line. The operational line here is simple. Protect the production cycle. Reduce consumption across electricity, gas, gasoline, water, and other energy uses. If necessary, shut public leisure sites. That is not a campaign poster. That is a load-shedding plan with a political wrapper.
Perhaps the most interesting aspect is how openly hardship is being sold as strategy. The condition for resistance, the president said, is that everyone endure difficulty. You can disagree with the framing and still take the economics seriously. A state that expects households to absorb the shock is a state that expects the external squeeze to last. Short squeezes get papered over with reserves and quiet barter. Long squeezes show up in the dark at 7 p.m.
What The Rationing Request Actually Asks People To Give Up
Read the request as a stack, not a slogan. Electricity first, because industry and summer cooling already fight over the same grid. Gas next, because residential heating and petrochemical feedstock share molecules. Gasoline, because subsidized fuel is both a social contract and a fiscal leak. Water, because power plants and farms drink from the same stressed basins. Other energy sectors left unnamed, which is usually where the awkward cuts live.
Closing cultural and sports complexes is the tell. Those buildings are visible, politically costly, and electrically hungry in a dumb way. Turning them off does not refine a barrel. It does free megawatts and, more importantly, it teaches the public which priority won. Industrial production over leisure. In my experience, governments reach for that trade only after quieter measures have already been tried.
- Household power cuts protect factory uptime and export-linked industry.
- Fuel restraint slows the drain on subsidized gasoline and diesel.
- Gas savings keep feedstock available for plants that still earn hard currency.
- Water limits are a warning that the constraint is physical, not only financial.
- Public venue closures make the sacrifice visible without stopping the ports.
None of that proves exports have gone to zero. It does prove the leadership wants the public braced for a grind. Investors who only trade the daily barrel miss that. The grind is what sets the floor under risk premia for months, not hours.
A Stalemate With Two Different Clocks
Mediators are describing the channel as stalled. That word gets abused. A stall can mean a pause before a handshake. It can also mean both sides have decided the next useful date is after someone else’s election. Regional reporting this week leaned toward the second reading. American officials, according to those accounts, are telling Tehran there will be no progress until there is progress on the nuclear file. The same accounts say the strait is no longer treated in Washington as the priority it was, on the argument that Tehran has lost practical control of it.
Tehran’s public answer is the mirror image, not a surrender. Iran is fully prepared, the president said, for a balanced and fair agreement that secures lasting peace in the region. The red line is national interest and the rights of the Iranian people. If the United States stays inside international legal frameworks, a deal is not out of reach. That is an open door with a lock still on it. Both sentences can be true at once. Willingness to talk is not the same as willingness to move the file the other side calls the precondition.
A stalled channel is not a quiet channel. It is a channel where each side has decided the other must blink first, and both have calendars that reward waiting.
Market desk observation, not a diplomatic communique
The American clock, if recent presidential signaling holds, runs through the November midterm vote and possibly toward a harder military option after that. The Iranian clock runs through winter demand, currency stress, and the need to keep industrial power online. Those clocks do not sync. That mismatch is the whole trade.
The Strait Is Where The Narratives Collide
Here is the part that refuses to sit still. One side of the argument says the waterway is no longer a lever because control has slipped. The other side, via an adviser linked to the revolutionary guards, says the strait is fully controlled, will stay closed to normal traffic until demands are met, and that whatever crude is still slipping out is a very small smuggled volume. Meanwhile, commercial shipping has absorbed a cluster of drone strikes. Accounts circulating among maritime analysts put the recent count near thirteen vessels in about eight days, with several disabled, burning, or blacked out.
I do not need to pick a flag to see the market implication. If strikes were rare and symbolic, insurers yawn. If strikes disable ships, underwriters rewrite the quote. A disabled tanker is not a headline. It is a hull, a crew, a cargo, and a claims file. Thirteen incidents in a little over a week is not a rounding error, whatever officials say about who holds the channel.
There is a sharper reading that some shipping watchers are now willing to say out loud. Earlier weeks looked oddly restrained, as if vessels were being warned more than wrecked. The latest stretch does not look restrained. Ships set ablaze or left without power change the risk math for every charterer who still routes through the Gulf. You can call that loss of control, retained control, or a messy mix. The premium does not care about the label.
Oil Flow Numbers That Do Not Agree With The Slogans
Officials in Washington have suggested Iranian crude exports are near a standstill. Iranian media, answering that claim, reported something narrower and, to my eye, more useful. Oil passing through the strait was said to have fallen about 60 percent, with flow over the last two days near 3.8 million barrels a day. The weekly average was put around 9.3 million. Those figures describe the whole corridor, not one country’s loadings. Still, a drop of that size in two days is the kind of number physical traders circle in red.
Hold both claims in your head without forcing them to marry. Near-zero Iranian exports can coexist with millions of barrels of other producers’ crude still moving, if the channel is open to some flags and hostile to others. A 60 percent corridor drop can also mean buyers are refusing the route, not that pumps have stopped. The smuggling line, that volumes still leaving are very small, is a political boast as much as a statistic. Boast or not, it concedes the legal export machine is impaired.
| Signal | What was claimed | How a desk should read it |
| Export standstill | Iranian crude near zero | Treat as a pressure narrative until tanker tracking agrees |
| Corridor drop | About 60 percent, near 3.8 million barrels a day versus a 9.3 million weekly average | Physical tightness risk if it lasts beyond a few sessions |
| Full control | Strait shut until demands are met, smuggling very small | Political message, but consistent with higher war-risk cover |
| Lost control | Hormuz no longer the priority lever | May explain why nuclear talks are the stated precondition |
| Ship strikes | Multiple vessels hit, some disabled or ablaze | The cleanest real-time indicator of route stress |
Numbers like 3.8 and 9.3 will be revised. They always are. What matters is the direction and the argument around it. Tehran is no longer pretending the corridor looks normal. That admission, more than any rival claim, is what sticks.
The Currency Slide And The Neighbor Who Feels It First
A cratering rial is not an abstract FX chart if you live next door. Iraq’s economy, its fuel trade, and parts of its politics have long been tangled with Iranian supply and Iranian cash cycles. When the rial buckles under sanctions and a wartime budget, the spillover does not wait for a summit. Importers reprice. Cross-border settlements get clumsy. Aligned political networks lose the slack that cheap energy used to provide.
I keep coming back to this because equity investors treat Gulf risk as a tanker story and forget the invoice story. A weak currency forces a producer to chase hard-currency barrels even harder, which can mean more smuggling attempts, more discounting, and more friction with any naval screen trying to stop both. It also forces austerity at home, which is exactly what the rationing speech is doing in public. The rial is the silent co-author of that speech.
Does a weaker currency make a deal more likely? Sometimes. It can also harden a leadership that has already told its people endurance is the strategy. Pain is not a reliable diplomat. It is a reliable source of volatility.
Blockade Pressure Without Calling It A Blockade
Sweeping sanctions are familiar. Naval action against ports is a different temperature. Reporting around this episode describes US naval measures aimed at Iranian ports continuing to bite, alongside the sanctions stack. Whether lawyers call that a blockade, a quarantine, or interdiction, shipowners hear one thing. The approach to the load port is no longer a paperwork problem. It is a routing problem.
That is why the president’s line about not allowing the production cycle to be damaged matters. If ports are constrained, the barrels you can still produce need somewhere to go, or the wells and plants back up. Rationing domestic energy is one way to keep export-linked industry alive while the maritime door narrows. It is an ugly workaround. Workarounds are what sanctioned economies run on until they cannot.
- Sanctions restrict buyers, banks, insurers, and shipping services.
- Naval pressure raises the cost and risk of reaching load points.
- Domestic cuts try to reserve power and fuel for whatever can still earn abroad.
- Discounts and indirect routes attempt to clear the barrels that do move.
- Public speeches prepare households for the gap between those steps.
Skip any one of those and the picture looks cleaner than it is. Put them together and you get a wartime economy that still speaks the language of a possible agreement. Both registers are active. That is not confusion. That is policy.
Nuclear File First, Everything Else Later
The precondition being relayed to Tehran is narrow. No progress in the wider talks until there is progress on the nuclear file. Hormuz, in that telling, has been demoted. You can see why a negotiator would try that move. If the strait is judged less controllable, it is a weaker hostage. If enrichment and related commitments are judged the core security issue, everything else becomes a sequel.
Tehran’s red line answers in kind. National interests and the rights of the public are not negotiable, and any deal has to look balanced. Legal frameworks get a mention, which is a way of saying the other side should not invent rules mid-channel. I read that as a refusal to accept nuclear concessions as a toll booth in front of sanctions relief. They will talk. They will not, on current evidence, pay the toll first.
Stalemate is the honest word. Not collapse of contact. Not imminent signature. A freeze in which each capital can tell its audience it has not given the point away. Freezes are tradable. They are also how small incidents become the only price discovery left.
The Calendar Nobody On The Desk Can Ignore
American political timing has walked into this story whether energy traders want it or not. Recent presidential comments have been read as a hint that the status quo holds through the midterm vote, with a heavier air campaign against Iranian targets conceivable toward the end of November if the file does not move. Treat that as a signal, not a schedule. Signals still reprice options.
Why does a vote in another country change a barrel in the Gulf? Because the perceived cost of escalation changes. Before a midterm, a White House may prefer a contained squeeze to a visible war. After it, the same office may decide the squeeze failed and reach for strikes. Markets that assume linear pressure get hurt by step changes. November is a step on the calendar even if nothing is fired.
From the other shore, waiting can also look rational. If you believe the other side is constrained by its own election, you ration, you harass shipping just enough to stay relevant, and you keep the diplomatic sentence alive. That is a bet. Bets expire. The rationing speech is what a government sounds like when it is funding the bet with household comfort.
The condition for resistance and standing up to the West is for everyone to endure hardship.
Iranian president, in remarks carried by domestic news agencies
Quotations like that age badly if the hardship is uneven. They age even worse if the factories they were meant to protect still lose power. Watch industrial output chatter and port call frequency more than the next patriotic line.
How The Narrative Battle Leaks Into Prices
Western coverage has, fairly or not, leaned on one side of the Hormuz argument while giving less airtime to Tehran’s control claim. Iranian outlets have done the reverse. Traders do not need a referee. They need a working model of what a charterer will actually do on Monday morning.
A charterer does not load because a spokesman said the strait is open. A charterer loads because the owner, the insurer, the flag state, and the buyer all still say yes. Each drone strike deletes a yes. Each week without a strike slowly writes it back. The last eight days deleted more yeses than the market’s calm patches implied. That is why some analysts now argue the earlier quiet was a choice, not an inability, and that the choice has changed.
I am wary of mind-reading navies. I am not wary of disabled ships. If vessels are blacked out or burning, the route is impaired regardless of which press conference you prefer. Price the impairment. Leave the slogans to the slogans.
What Severe Hardship Looks Like Without The Poster
Strip the speech down and the admission is plain. This is a heavily sanctioned economy being run on a wartime footing, and the leadership wants that understood at home. Oil revenue, the historic shock absorber, is contested. The currency has given way. Neighbors are feeling the draft. Public buildings may close so industry can run. That is a coherent picture of stress even if every export figure is still being fought over.
Hardship on that scale has a market cousin called demand destruction, except here the destruction is being chosen. Voluntary cuts in a producing country do not lower Brent by themselves. They can lower the chance of an unplanned industrial outage, which is mildly bearish for local product tightness and irrelevant to seaborne crude if exports are already choked. They can also signal that spare capacity at home is a fiction. A producer rationing its own grid is not a producer sitting on easy barrels.
Rough desk map, not a forecast:
  Route stress      -> insurance and freight
  Export argument   -> flat price and spreads
  Domestic cuts     -> duration of the squeeze
  Election calendar -> timing of any step-up
  Currency slide    -> discount and smuggling risk
Use that map as a checklist, not a model. If three boxes flash at once, the quiet session you liked yesterday is a trap.
Shipping, Insurance, And The Cost Nobody Screenshots
Freight is the honest journalist of this story. War-risk premiums do not attend press conferences. They attend incident logs. A run of drone attacks that leaves ships disabled is exactly the log underwriters price. Even a partial corridor, open to some hulls and hostile to others, splits the market into a clean route and a discounted route. The clean route gets bid up. The discounted route becomes a specialist trade with specialist failures.
Owners who can refuse the Gulf will refuse it until the extra dollars cover the worst week, not the average week. That is why a two-day drop toward 3.8 million barrels can matter more than a soothed weekly average of 9.3 million. Averages hide the day the owner said no. Clusters of strikes create those days.
There is also the crew question, which desks mention too rarely. Mariners talk. A blacked-out ship becomes a story in every mess room on the rotation. Recruitment and retention fray before the official route status changes. I have watched freight blow out on reputation alone, weeks before the casualty statistics caught up. This episode already has the anecdotes.
Refiners, Differentials, And The Barrel That Still Has To Land
Asian and European refiners do not buy narratives. They buy molecules that fit the kit. If Iranian grades are scarce, buyers lean on substitutes with similar yields, and those substitutes firm. If the whole strait slows, the substitute trade gets crowded at the same time, which is how a regional security story becomes a global crack-spread story.
Watch sour crude differentials and diesel cracks more than the headline flat price. A blockade that mostly removes heavy sour barrels tightens a different part of the stack than a general tanker panic. The current mix, sanctions plus route incidents plus a claimed corridor drop, can do both. That is awkward for anyone running a single macro hedge and calling it coverage.
Winter does not care about talks. Heating demand and refinery maintenance calendars will collide with this freeze if it lasts. A stalemate that looked abstract in early autumn can look physical in December. That is the lag retail commentary always misses, and it is the lag that pays the people who map runs rather than headlines.
Scenarios Worth Stress-Testing Before The Next Speech
I am not in the prediction business. I am in the what-breaks-first business. Three paths are enough to stress a book.
Path one is the long freeze. Talks stay stuck through the US vote. Rationing deepens. Incidents continue at a level that keeps insurance elevated but does not close the corridor outright. Iranian exports stay impaired, other Gulf barrels move at a premium, and the rial remains under pressure. This path is boring until it is not, because boredom is how risk premia get sold too cheap.
Path two is a narrow deal, or at least a de-escalation swap. Nuclear steps in exchange for limited relief, enough to restart some legal liftings and cool the strike tempo. Domestic rationing eases only slowly, because grids do not heal on signatures. Flat price gives back the fear premium. Differentials take longer. This path needs both capitals to value a small win more than a posture, which current language does not show.
Path three is a step-up. Strikes on ships multiply, or air power is used against military and industrial targets after the political window opens. The corridor drop stops being a two-day story. Then you are not trading Iran. You are trading spare capacity everywhere else, strategic stocks, and the chance that other producers cannot or will not fill the hole fast enough. The rationing speech, in that path, was the early warning that Tehran already expected a long hit.
- Freeze path: carry insurance risk, do not fade every quiet week.
- Narrow deal path: sell fear premium slowly, keep a residual geopolitical toehold.
- Step-up path: liquidity vanishes first in products and freight, then in flat price.
None of these requires you to admire either government. They require you to notice that both have described a world in which compromise is optional and endurance is policy.
The Iraq Angle Deserves Its Own Line Item
Neighbor effects get a paragraph in most notes and a chapter in real life. Iraq imports power and gas linkages, political patience, and a set of commercial habits built in easier years. A Tehran that is cutting its own complexes to feed industry is a Tehran with less slack to subsidize anyone else. Baghdad feels that as price, as outage risk, and as factional noise.
For portfolio purposes the point is correlation. A Hormuz shock and an Iraq instability shock are not independent dice. They share a wire. If you are long regional risk through a single ETF and calling it diversified, this week is a reminder that the wire is live. Currency stress on one side of the border has a habit of becoming fiscal stress on the other.
I would rather hold that as a qualitative overlay than pretend to model militia incentives. Qualitative does not mean soft. It means you do not add risk into the same weekend the rial and the grid are both in the speech.
Reading Official Sentences Without Getting Recruited
Both capitals are speaking in complete sentences again, which is better than silence and worse than clarity. Prepared for a balanced agreement. No progress until the nuclear file moves. Red lines intact. Strait controlled. Strait no longer the lever. Exports near zero. Flow down 60 percent. Endure hardship. Stand up.
A useful habit is to sort sentences into operational and theatrical. Operational sentences change a schedule, a cargo, a megawatt, or a premium. Theatrical sentences change a mood. The rationing list is operational. The endurance line is theatrical with operational intent, because it lowers the political cost of the list. The export-zero claim is theatrical until trackers agree. The 3.8 million barrel figure is operational enough to check against ship data. The thirteen-vessel cluster is operational whether or not anyone claims credit.
Do that sort every morning and the speech stops jerking your book around. You will still be wrong sometimes. You will be wrong less often than the feed.
What Households Are Being Asked To Finance
It is worth sitting with the human side without turning it into a sermon. Cutting electricity is not an abstract elasticity. It is a clinic running warm, a bakery shifting hours, a student losing the evening. Closing a sports hall is a small thing until it is the only cool public room in a neighborhood. Governments know this. They ask anyway when they believe the alternative is a broken export machine and a louder crisis later.
Markets do not price dignity. They price whether the ask is accepted. If compliance is high, industrial uptime holds and the squeeze can be prolonged. If compliance fails, you get informal leakage, generator diesel demand, and a second fuel problem on top of the first. Either outcome is information. The speech is the start of the test, not the result.
There is a cynical trade hiding in that test. Prolonged household cuts that successfully protect export plants are, perversely, a reason the stalemate can last. Failed cuts that darken industry are a reason the leadership may need a diplomatic off-ramp sooner. Watch which buildings actually go dark.
Positioning When Both Sides Expect To Wait
If the freeze is the base case through the vote, the error is treating every down day in crude as all-clear. Insurance and freight can stay bid while flat price chops. Options that cover a gap move into late November are not a view on who is right about the strait. They are a view on the calendar both sides have already hinted at.
I prefer expressed risk to vague worry. That can mean a defined option structure around a Gulf-heavy crude basket, a freight proxy if you can trade one cleanly, or simply less gross exposure into weekends when incident risk clusters. It does not mean a permanent long bias. Path two exists. Relief rallies on even a procedural meeting will be sharp, because positioning in fear trades gets one-sided fast.
Size for the path you cannot sit through. If a step-up would force you to sell the worst print, you are already too big. The rationing story is a duration story. Duration punishes people who only prepared for a headline.
Weekend check: incidents, corridor flow, rial, official precondition, election clock. If four of five worsened, do not add risk on Monday's open.Crude, I know. Also cheaper than discovering your hedge was a tweet.
The Production Cycle They Are Trying Not To Break
Return to the phrase that opened the domestic ask. Do not allow the production cycle to be damaged. In an oil state, that cycle is wells, gas plants, refineries, petrochemicals, ports, and the power that ties them together. Damage it and you lose the thing sanctions are trying to shrink, faster than sanctions alone would. Protect it and you can argue, internally, that endurance is working.
That is why leisure complexes are on the chopping block and export plants are not. It is an allocation. Investors should copy the logic even if they reject the politics. Follow the megawatts. If industry is shielded, the leadership still thinks barrels and products can be monetized somehow. If industry goes dark too, the cycle they named has already slipped.
Secondary indicators help. Smuggling anecdotes. Floating storage. Discounts versus similar grades. Port agency chatter. None of these is a press release, which is why they are useful. The official line will keep saying control or lost control depending on the microphone. The cycle will tell you which sentence was for show.
A Fair Agreement Is A Phrase, Not A Term Sheet
Balanced and fair are doing a lot of work in the public offer. Fair to whom, measured how, verified by which inspectors, paid in which relief? None of that is on the table in the remarks we have. What is on the table is a conditional. If the other side stays inside legal frameworks, agreement is not impossible. Diplomats say versions of this when they want the door visible and the hallway empty.
The matching conditional from the other direction is just as empty of detail. Progress on the nuclear file, then progress elsewhere. No sequence, no interim steps, no mention of what a first gesture would even be. Two conditionals facing each other are a stalemate with good grammar.
Markets can live with good grammar for a while. They cannot live with it once ships burn and grids are being triaged. The grammar is the ceiling on hope. The incidents and the rationing are the floor under risk. Trade the floor until the grammar grows verbs.
Why This Episode Feels Different From Older Gulf Scares
Older scares often had a single lever. A mine, a seizure, a rhetorical threat to close the channel, then a quiet reopening once face was saved. This one has stacked levers. Sanctions that already rebuilt trade routes. A currency break. A public rationing plan. A nuclear precondition. A cluster of disabling attacks. An election clock. A claim, from both sides, that the old Hormuz bargain no longer describes reality.
Stacked levers fail differently. You can settle one and still be trapped by another. Even a tactical pause in ship attacks would leave the nuclear file and the rial where they are. Even a modest sanctions waiver would leave the grid speech unexplained unless barrels actually start moving. That is why I am reluctant to call the next calm a resolution. Calm is a weather report. Resolution is a cargo list.
There is also a credibility hangover. If earlier weeks of light contact were a choice, as some maritime readers now argue, then restraint is a policy tool, not a shortage of tools. Policy tools get reused. Anyone selling volatility because a few days went quiet is volunteering to be the next example.
A Practical Watchlist For The Next Several Weeks
You do not need a situation room. You need a short list you will actually check.
- Confirmed incidents against commercial hulls, and whether ships are disabled or merely warned.
- Independent corridor flow versus the 3.8 and 9.3 million barrel markers already in circulation.
- Any softening, or hardening, of the nuclear-first precondition.
- Evidence that cultural sites actually closed, which would confirm the rationing ask is real.
- Rial stability and any new cracks in Iraqi power or fuel supply.
- War-risk premium quotes, not just flat crude.
- Language about timing relative to the November vote and the weeks after it.
Seven items. If you track only the flat price, you will be late. The flat price is the argument. These items are the evidence.
The Mistake Of Treating Hardship As A Bluff
It is tempting to file the endurance line under propaganda and move on. Sometimes that is right. Propaganda that asks people to sit in the dark is expensive propaganda. Leaders spend it when cheaper lines have stopped working. I would not build a whole book on that instinct, but I would not fade it either.
Bluffs get walked back quickly once the lights stay on and the sports halls stay open. Real programs show up in municipal notices, generator sales, and factory shift changes. Give it a fortnight. If the only darkness is rhetorical, mark the speech down. If the darkness is scheduled, mark the squeeze as something the state is willing to administer, not merely describe.
That distinction changes the left tail. A bluff ends when called. An administered squeeze ends when it fails or when a deal pays it off. Failure is disorderly. Deals, on this file, have not been quick. The left tail is fatter than a normal Gulf headline week.
Where Equities, Credit, And Crude Stop Sharing A Brain
Crude can rally on route fear while airline equities and chemical credits sulk. Regional banks with trade-finance exposure do not trade like Brent. A long-only investor who owns a bit of everything will feel this as a wash and miss the rotation underneath. The wash is not safety. It is two pains canceling on a spreadsheet.
If you run a multi-asset book, separate the questions. Is the corridor impaired? That is freight and sour diffs. Is the producer fiscally cornered? That is currency, domestic austerity, and any sovereign-linked credit you still hold. Is the political clock pointing at a step-up? That is index volatility into late November, not just energy beta. Answer them separately or you will hedge the wrong leg and call it discipline.
I have made that mistake in smaller scares, hedging the barrel and leaving the credit. The credit moved first. It usually does when the story is sanctions and currency rather than a pure outage.
What Would Actually Change My Mind
A mind worth having should say what would flip it. Mine flips if independent tracking shows corridor volumes back near the recent weekly average for more than a brief bounce, and if disabling attacks stop rather than pause. It flips toward a deal path if both sides describe a sequence, not a precondition. It flips toward the step-up path if official timing language hardens after the vote, or if port approaches become practically unusable for neutral flags.
Rationing alone does not flip me. Rationing plus a restored export machine would be a surprise worth respecting, because it would mean the squeeze was absorbed. Rationing plus a still-choked machine means the speech was accurate. Accuracy from a stressed capital is not comfort. It is a map.
Until one of those flips prints, the base case stays unpleasant and slow. Stalemate, household cuts, a contested strait, and a calendar that both sides seem willing to use. You can trade around that. You should not romance it.
The Part The Daily Recap Always Rushes Past
Recaps will tell you the talks are stuck, the president wants sacrifice, and oil wobbled. Fine. The part they rush is the allocation inside the sacrifice. Power for industry. Darkness, if needed, for leisure. Fuel disciplined so the cycle survives. A neighbor already wobbling. A waterway whose status is now a duel of sentences. A vote abroad that may be functioning as a truce line neither side signed.
That bundle is the article, not the wiggle in the front-month contract. If you remember only one thing into the next session, remember that Tehran has started explaining austerity as strategy while Washington has started explaining the strait as yesterday’s lever. Strategies and levers get tested. The test, this month, runs through hulls, grids, and a ballot that has nothing to do with either coastline and everything to do with timing.
I do not know which sentence breaks first. I know which evidence I will trust when it does. Not the fairest adjective. Not the firmest red line. The cargo that moves, the building that closes, and the ship that either reaches port or does not. Everything else is a speech. Speeches set the mood. Those three set the price.
Sit with the rationing ask a second longer than the tape wants you to. A government that tells its own public to fund a stalemate with electricity is telling you the stalemate is not a pause on the way to a photograph. It is the policy, until a costlier policy replaces it. Price it that way, and the next quiet morning will not feel like permission.
You must gain control over your money or the lack of it will forever control you.


Zcash Price Prediction For October After The Pullback

Energy Transfer Stock: Income And Growth In One Holding
Related Articles
Why Berkshire’s Stock Dip Signals Investor Concerns
Berkshire Hathaway's stock dips as earnings falter and buybacks stall. What’s next for the conglomerate, and should investors worry? Dive into the details...
Trump Cracks Down on TV Drug Ads Shaking Billions
Imagine flipping through TV channels only to see drug ads suddenly spilling all the gritty details on side effects. Trump's latest move is shaking up the pharma world, but what does it mean for your health and the media giants relying on those billions?

Cboe Binary Options Relaunch Targets Polymarket Rivalry
Cboe is quietly gearing up to bring back binary options in a big way, aiming straight at the explosive growth of prediction markets like Polymarket. But can a traditional exchange really pull retail traders away from decentralized platforms? The details might surprise you...