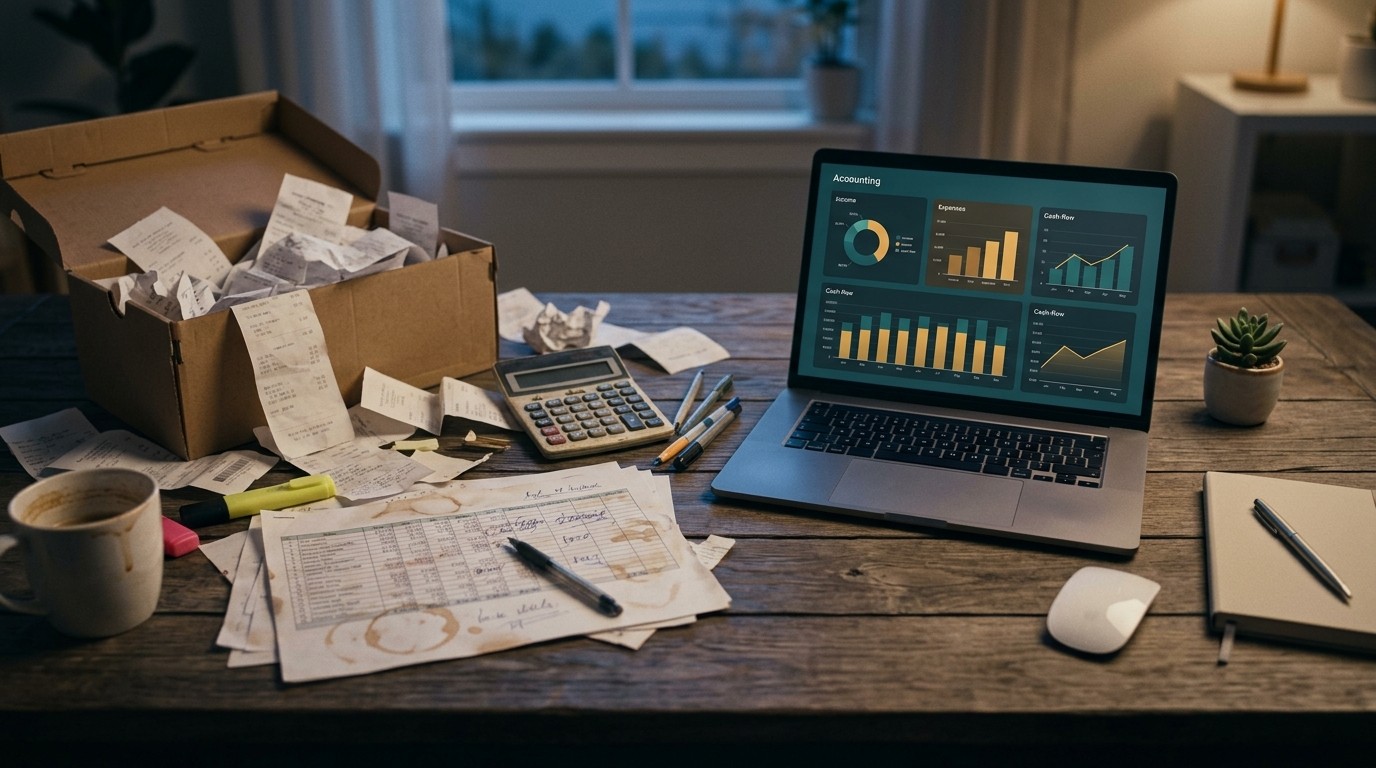

I still remember the Tuesday a friend slid a laptop across a café table and said, almost embarrassed, that she had spent the weekend reconciling March. Not filing taxes. Not planning a hire. Just matching bank lines to a spreadsheet she no longer trusted. The coffee went cold. The tab for that month was already wrong by a few hundred dollars, and she could not say where. That is usually how the conversation starts. Not with a grand strategy meeting. With a quiet suspicion that the books are holding the business back.
Manual bookkeeping can be perfectly honest work. A notebook, a tidy spreadsheet, a folder of receipts. Plenty of freelancers and tiny shops run that way for a year or two and sleep fine. The trouble is not the method. The trouble is the moment the method stops matching the business, and almost nobody notices on the day it happens. You notice later, when a customer claims they paid, when a contractor asks for a form you cannot find, or when tax season turns into a scavenger hunt.
The Quiet Point Where Spreadsheets Stop Being Enough
There is no universal invoice count that flips the switch. I have watched a one-person studio outgrow paper faster than a five-person shop with simple billing. Complexity, not headcount, is the real trigger. Once money moves through more than one channel, once you owe sales tax, once someone else needs to see the numbers, a personal system starts leaking time.
Accounting software is not a personality upgrade. It is a place where invoices, bank activity, receipts, and reports live in the same current. Done well, it cuts duplicate entry and shows cash before the account runs thin. Done badly, it is just an expensive spreadsheet with extra buttons. The difference is timing and honesty about what you actually need.
If any of the scenes below feel familiar, you are probably past the cute phase of manual books. You do not need a large company, a formal entity, or a finance degree. You need a system that can grow without asking you to become a part-time clerk.
You Are Sending More Invoices Than You Can Babysit
A handful of invoices a month is manageable. You remember who is late. You nudge them with a short note. Then the list stretches. A deposit here, a partial payment there, a client who pays the old invoice number. Suddenly you are the collections department and the bookkeeper, and neither job is getting your best hour.
Good software builds the invoice from items you already use, tracks what is open, and can nudge balances without you rewriting the same polite email. That is not glamorous. It is the difference between guessing at cash and seeing it. Late money is not only annoying. It is a planning problem. You cannot hire, buy stock, or take a slow month if you do not know what is actually coming in.
Cash you have invoiced is not cash you can spend. Until it lands, it is a story you are telling yourself.
I have found that owners underestimate how much mental space open invoices occupy. You check the bank at odd hours. You replay a call. Software will not make a slow payer faster by magic, but it will stop the chase from living only in your head. Estimates, recurring bills, and a clean record of who owes what turn a fuzzy pipeline into something you can act on.
There is a softer benefit too. Clients take a consistent invoice more seriously than a one-off attachment with a slightly different layout each month. Professional does not mean stiff. It means the number, the due date, and the way to pay are obvious.
People Are Starting To Get Paid By You
The first contractor feels simple. You send a transfer, save a note, move on. The second one asks about a form. The third wants hours tied to a project. By the time you have a small crew, payroll is no longer a side task. Hours, direct deposit, benefits, and payroll taxes each have a deadline, and missing one is more expensive than the software you avoided.
Accounting tools that pair with payroll can track time, push deposits, and keep the tax side from becoming a separate mystery. Assigning hours to a client or job also makes invoicing less of a guess. If you bill for labor, that link is worth more than any dashboard color.
- Hours that never quite match the invoice
- A contractor paid from the wrong account
- Tax deposits you meant to schedule and did not
- Benefits or reimbursements living in a side spreadsheet
- No clean record when someone asks what they earned
You can still run a tiny team on manual books. Plenty do. The cost shows up as evenings, not as a line item. Perhaps the most interesting part is how quickly owners describe payroll as the thing that finally broke the old system. Not growth. Not ambition. Just the fear of getting someone’s pay wrong.
An Accountant Already Has A Foot In The Door
Even a once-a-year tax preparer changes the job. They need figures they can trust, and you need to share those figures without handing over the keys to everything. Emailing a workbook and hoping the version is current is a ritual many owners quietly hate.
Permission levels solve a real awkwardness. Your bookkeeper sees the ledgers. A partner sees reports. A seasonal helper does not wander into payroll. Plans differ, but the idea is the same: access is a setting, not a leap of faith. Cloud access also means the preparer is not waiting on a zip file you build at midnight.
In my experience, the relationship gets better when the file is boring. Boring means reconciled. Boring means receipts sit next to the expenses they support. Boring means fewer “can you resend March” messages. That is a professional courtesy in both directions.
The Books Grew Teeth While You Were Busy
Complexity arrives before the office does. You collect sales tax in two states. You hold inventory that is not just “stuff in the closet.” You own equipment that should be depreciated instead of dumped into one expense line. You need to know which client ate the travel budget. A spreadsheet can hold all of that. It just will not hold it kindly.
Software is built to fold those details into reports you can actually read. A profit view by project. A stock count that does not depend on your memory. A depreciation schedule that does not live in a tab named FINAL_v7. Tax reporting gets cleaner because the categories were chosen in February, not reconstructed in April.
| Pressure point | What manual books do | What software should do |
| Sales tax | A side tally you update when you remember | Track taxable sales and what you owe |
| Inventory | A list that drifts from the shelf | Tie stock movement to sales and cost |
| Equipment | One big purchase line | Spread cost over useful life |
| Projects | Color coding and hope | Hours and costs by client or job |
| Mileage and travel | A notes app and gas slips | A log you can defend later |
None of those rows require a huge company. A maker who ships across state lines can hit three of them in a single quarter. If your spreadsheet has tabs that only you understand, that is not a system. That is a dialect.
Receipts Are Still A Physical Problem
The shoebox is a cliché because it keeps winning. Paper fades. Thermal slips go blank. A photo on your phone is better, until the photo is buried in a camera roll named with today’s date and nothing else. Rising expenses make the mess louder. More vendors, more subscriptions, more “I’ll categorize that later.”
Modern tools let you snap a receipt and match it to a charge you already imported, or create the entry if the charge is not there yet. The better ones do not ration how many images you can keep. That matters in a heavy month. A digital receipt next to the transaction is also what a reviewer wants when a deduction gets a second look.
Matching is where a bit of automation earns its keep. Rules and pattern tools can suggest a category. You still approve the odd ones. I would not hand the whole ledger to a guess. I would happily stop typing the same office-supply vendor by hand every Friday.
The Rest Of The Business Already Left The Notebook
Point of sale, a shopfront, payroll, card payments, a marketplace. If those tools talk to each other and your books sit outside the conversation, you are typing the same sale twice. Duplicate entry is where errors like to live. A transposed digit. A refund that never made it back to the sheet. A payout that includes fees you forgot to split out.
A connected ledger pulls bank and card activity and can take in sales from the places you already sell. The practical test is simple. If you close the laptop and still wonder whether yesterday’s card batch hit the books, the ecosystem is split. Widely used platforms link to banks, card issuers, and a long list of commerce and payroll apps. The count matters less than whether your stack is on the list.
Connection is not the same as wisdom. A feed can import junk if categories are sloppy. Still, starting from the bank instead of from memory is a kinder place to reconcile. You are checking a match, not rebuilding the month from scratch.
Tax Season Has Become A Second Job
Manual books feel fine in July. They feel cruel in March. You are paging through months of lines, hunting a deduction you are sure you earned, and hoping the profit figure is not a rounding accident. Year-round software does the unglamorous work early: import transactions, reconcile, flag likely write-offs, and keep a current profit and loss view.
Stored receipts and shared access mean a preparer can review without a scavenger hunt. Exporting what they need should be a click, not a weekend. That is the real pitch. Not a prettier chart. Fewer nights spent proving a number you already lived.
A calmer year-end usually looks like this:
  Bank feeds reconciled monthly
  Receipts attached when the charge hits
  Sales tax set aside, not guessed
  Payroll filings already filed
  A profit view you opened before December
According to practitioners who sit with owners every spring, the painful files are rarely missing talent. They are missing a cadence. Software will not file for you unless you set that up. It will stop the cadence from depending on memory.
What “Ready” Actually Feels Like
Readiness is less dramatic than ads suggest. You are ready when a routine task keeps slipping, when a second person needs the numbers, or when a mistake would cost more than a subscription. You are also ready when you are tired of being the only one who can explain the sheet. That last one is easy to dismiss. It is also how businesses get stuck when the owner takes a week off.
You are probably not ready if you have a dozen transactions a month, no tax complexity, and a system you genuinely enjoy. Forcing software onto a hobby-scale ledger can be theater. The tool should remove work. If it adds a login you resent, wait.
- Count the hours you spent on books last month, honestly
- List the places money enters and leaves
- Note anything you could not answer in five minutes
- Ask what a preparer would request tomorrow
- Price the tool against those hours, not against zero
That fifth step is where people get cute. They compare software to free. Free was never free. It was your evening. If those evenings are cheap and pleasant, keep them. If they are tense, the math has already shifted.
A Plain Look At What The Software Should Cover
Plans vary, and prices move. A limited discount is common when vendors want you in the door. Ignore the banner and look at the jobs. You want expense and income tracking that happens as money moves, invoicing, payment acceptance, bill tracking, basic reports, and a way to handle contractors. Mileage, estimates, and deduction hints are useful once travel and taxes matter. Payroll is often an add-on. Treat it as its own decision.
Categorization should be assisted, not mystical. Bank and card links are table stakes. So are connections to the payment tools you already trust. Browser access plus a phone app matters if you snap receipts in a parking lot. Security is not a slogan. Look for encrypted connections, protected logins, and the ability to limit what each user sees. Scanning and server protections are the background. Permissions are the part you will actually use.
Availability across a normal browser and the major phone stores sounds minor until you are away from the desk. The books should travel with the business, not wait at home in a file only one computer opens.
The Migration Without The Melodrama
Switching feels bigger than it is. You are not rewriting history from the founding year unless a preparer asks for it. Most owners start at a clean month, bring in open invoices and unpaid bills, and connect the bank. Old spreadsheets stay as an archive. They do not need to become a religion.
Pick a start date. Reconcile the bank to that morning. Enter what customers still owe and what you still owe vendors. Then stop entering the same sale in two places. The overlap week is where people create duplicates and then blame the tool. Give the old sheet a retirement date and mean it.
A clean start date beats a perfect historical import. Perfect is how migrations stall.
– A bookkeeper who has cleaned up too many half-moves
Categories deserve an hour before you import a flood of transactions. If you invent twenty versions of “misc,” the reports will lie politely. Mirror the categories your preparer already uses. Future you will send a quieter thank-you.
Mistakes That Make The New System Feel Worse
The first mistake is connecting every app on day one. Start with the bank and invoices. Add the shopfront when the core ledger behaves. The second is ignoring reconciliation because the feed “already brought it in.” A feed is a suggestion until you match it. The third is letting automation categorize a personal charge as a business one because the rule was lazy.
Another trap is buying the largest plan because the comparison chart looked serious. If you do not hold inventory or run projects, you may not need those modules yet. Upgrade when a real limit appears. Downgrading later is annoying. Overpaying from week one is just quiet.
And then there is the shared login. Do not do it. Separate users, limited rights, and a record of who changed a bill. It feels fussy until someone edits a paid invoice and nobody knows why the customer is confused.
Cash, Deductions, And The View You Actually Need
Owners say they want reports. What they want is a Tuesday answer. Can I cover payroll? Which job made money after materials? What is sitting in unpaid invoices older than thirty days? Software earns the fee when those answers are a filter, not a reconstruction.
Deduction tracking is similar. The write-off is not born at tax time. It is born when you tag the charge and keep the proof. Mileage, home-office costs where they apply, contractor payments that need year-end forms: these are easier if the habit is monthly. A highlight that says “this might be deductible” is a prompt, not a ruling. You, or your preparer, still decide.
I like a short monthly close more than a fancy annual one. Match the bank. Glance at uncategorized. Send the two late invoices. That rhythm is what makes April boring, which is the highest compliment books can receive.
Who Can Stay Manual A Little Longer
A side project with one client, paid by a single transfer, and almost no expenses can live in a sheet. A hobby that might become a business next year can too, if you are honest about the date. The risk is nostalgia. People keep the old method because it worked when the business was smaller, then act surprised when it fails at the new size.
There is also a temperament piece. Some owners like the tactile check of a register. Fine. Keep a review habit inside the software. Do not keep a second set of books “just in case” unless you enjoy finding conflicts. One ledger. One truth. Arguments with yourself are expensive.
How To Choose Without Getting Sold
Trial the workflow, not the homepage. Create an invoice. Connect a bank in read mode if you can. Snap a receipt. Invite a fake user and see what they cannot touch. Export a simple profit view. If those five actions feel clumsy, the feature list does not matter.
Ask where data lives if you leave. Ask how payroll is priced once you add a person. Ask whether sales tax is included or a puzzle. Support quality shows up on a Tuesday when a feed breaks, not in a tour video. Recent small-business surveys keep finding the same complaint: tools that look complete until the odd workflow appears. Test your odd workflow.
Price the year, not the promo month. A steep introductory cut is nice. The renewal is the real number. Put that next to the hours you listed earlier. If the tool returns even a few of those hours, and catches one missed invoice, it has a case.
A Week-One Habit That Actually Sticks
Day one is setup, not heroics. Chart of accounts trimmed to what you use. Bank connected. Opening balances checked. Day two is open invoices and bills. Day three is receipt capture on anything new. By the end of the week you should have reconciled once, even if the period is short. That single match teaches the screen better than a tutorial.
Tell anyone who touches money about the new path. A partner who still drops receipts in a kitchen bowl will undo the system with kindness. A shared folder or a simple capture habit beats a lecture. The tool is only as current as the last person who met a vendor.
Weekly close, small version: match bank + clear uncategorized + chase two invoices + file new receiptsThat line is intentionally dull. Dull is sustainable. Grand bookkeeping reforms die in week three.
When The Switch Pays For Itself
Payback is rarely a single dramatic save. It is a late invoice that got a reminder and arrived. A fee you split correctly so profit was not inflated. A sales-tax set-aside that prevented a ugly surprise. An hour on Thursday that went to a customer instead of a column. Stack those and the subscription stops looking like overhead.
There is a confidence return too. Quoting a job is easier when you know what the last three actually cost. Saying no to a discount is easier when the margin is visible. I have watched owners get braver with pricing once the books stopped being a fog. That is not a feature on a comparison chart. It might be the point.
Questions Worth Asking Before You Commit
Will this file talk to the bank I actually use? Can my preparer log in without seeing payroll if I want that wall? What happens to receipt images if I cancel? How are contractor forms handled at year end? Can I tag costs to a job without a workaround that only one employee understands?
If the answers are vague, keep looking. The market is crowded, which is annoying and useful. You are allowed to want boring reliability. Flashy forecasting can wait until the bank match is trustworthy.
One more question, the human one. Who will open this every week if you do not? If the answer is nobody, the software will become a museum of last quarter. Assign the habit. Even a thirty-minute Friday block beats a heroic cleanup.
Staying In Control After The Move
Software can tempt you to stop looking. Do not. A monthly glance at uncategorized transactions, duplicate vendors, and unusual spikes keeps the automation honest. Rules drift. A new supplier gets filed under the old one’s name. A refund lands in income instead of reducing an expense. Five minutes of skepticism is part of the system.
Separate personal and business money if you have not already. No tool fully saves a mixed account. It only makes the mix more visible, which is progress, and also a little humiliating the first time you see the grocery line in the ledger. Fix the account. Then let the software do its job.
Reports are for decisions, not for decoration. If a chart never changes what you do on Monday, hide it. Keep the profit view, the cash view, and the aging list of who owes you. Everything else can earn its place later.
A Practical Close For Owners Still On The Fence
You do not need a registered empire to justify the switch. You need friction that repeats. More invoices than you want to chase by hand. A person on payroll or a contractor who needs a clean record. A preparer who should see the file without a scavenger hunt. Sales tax, stock, equipment, or project costs that no longer fit a casual sheet. Receipts multiplying. Other tools already running the sale. A tax season you dread in January.
Hit one of those and you can still cope. Hit three and the spreadsheet is a hobby you are financing with your weekends. The earlier the system can flex, the less dramatic the next hire, the next state, the next busy season feels. That is the unsexy promise, and it is the one I trust.
Start smaller than your anxiety suggests. A clean month. Connected accounts. Receipts on the charges that matter. A preparer invited with limited rights. Then let the old notebook retire without a speech. The business will not applaud. It will simply ask fewer panicked questions, which, if you have lived inside a messy ledger, is applause enough.
If the café version of this story is already yours, you are not behind. You are on time. The books were trying to tell you something. Listening is the whole job.