
I still remember the first time I tried to send money to a cousin overseas with a regular bank app. The screen asked for a purpose code, a branch identifier, and a fee that looked like a parking ticket. Twenty minutes later the transfer was “pending,” which is banking language for “maybe Thursday.” So when a phone maker says dollar stablecoin transfers will live inside the wallet already on the device, my first reaction is not excitement. It is suspicion. Convenient tools have a habit of hiding the awkward part three menus deep.
Late October is the window Samsung has put on the calendar. Eligible Galaxy owners in the United States are supposed to gain Samsung Wallet USDC transfers across a footprint the company puts at 82 million devices. That is not a niche beta tucked inside a developer build. It is a consumer surface large enough to change how ordinary people first meet a stablecoin, even if most of them never say the word out loud.
What Actually Lands On The Phone
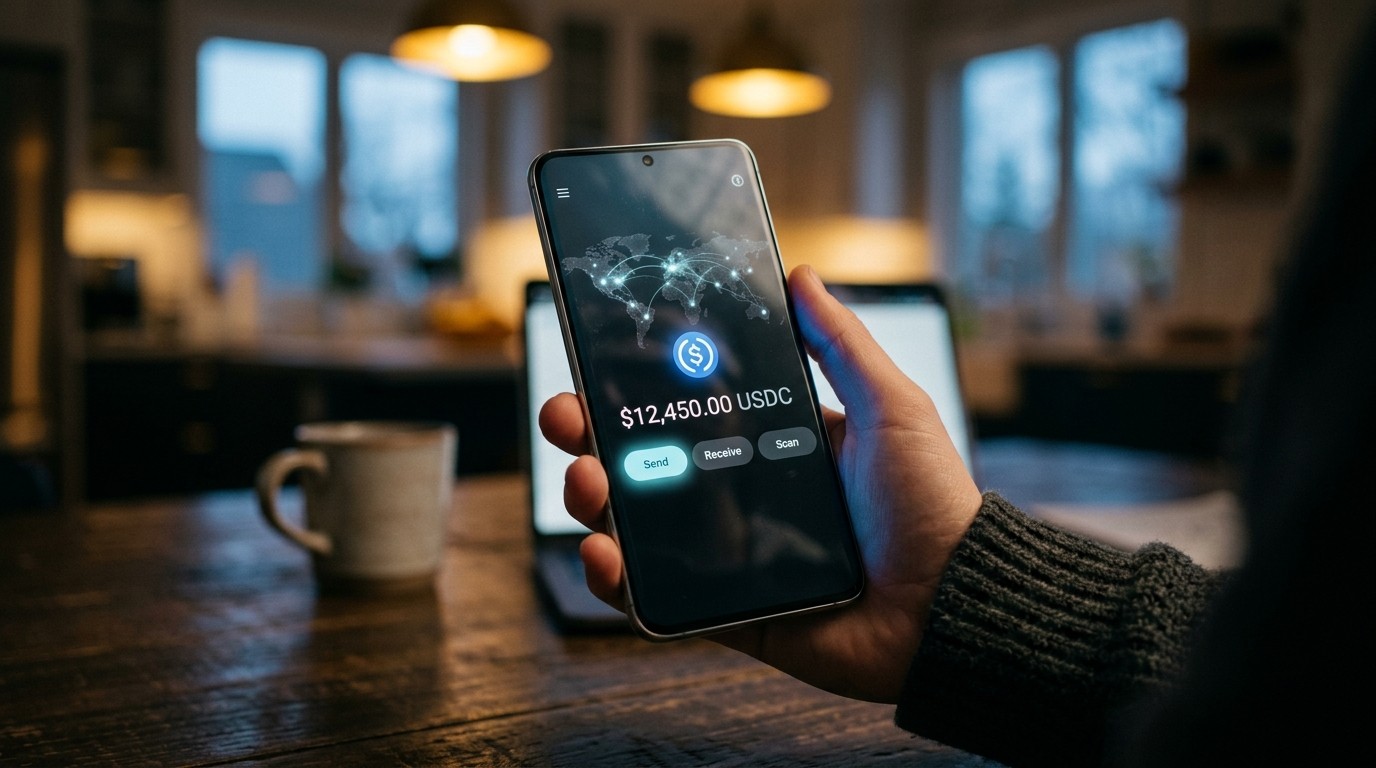
The pitch is simple enough to fit on a receipt. Open the wallet you already use for cards and tickets. Buy or hold USDC. Send it to a compatible crypto wallet, or push value toward a bank account in another country so the recipient gets local currency. No separate crypto app. No private keys sitting in a notes file. Biometric approval on a registered Galaxy device before the money moves.
Woncheol Chai, who runs Samsung’s digital wallet team, framed it as something that should feel as ordinary as the wallet already on the phone. I buy the instinct. People do not want a second identity just to pay a landlord in another time zone. They want the same thumb they use to unlock the screen. Whether the product earns that trust is a different question, and it will not be settled by a launch paragraph.
Sending money abroad should feel as convenient as using the wallet already on your phone.
Woncheol Chai, head of Samsung’s Digital Wallet Team
USDC is the first stablecoin in the flow, and Samsung has said it will show up as the default dollar stablecoin when someone taps the buy option. That choice matters more than it looks. Defaults become habits. A default dollar token inside a phone wallet is a distribution decision, not a technical footnote.
Two Paths, Two Very Different Promises
Wallet-to-wallet and wallet-to-bank are not the same product wearing different clothes. Treat them that way and you will misread the fee story.
On the crypto-wallet path, Samsung says eligible users can send USDC to compatible wallets without a Samsung transfer fee. Completion is expected in seconds, with the usual caveat that networks get moody. The recipient’s wallet or exchange can still charge its own toll. I have watched “free send” turn into a paid receive often enough to keep a pencil near the screen.
On the bank path, the recipient in a supported country is meant to see local currency land in an account. They do not need to hold cryptocurrency or install a wallet. Samsung has pointed to more than 60 countries. It has not, in the announcement material, published the full country list or a clean fee card for those bank legs. Applicable charges can vary by destination. That sentence is doing a lot of work.
- Wallet sends: no Samsung transfer fee, seconds in normal conditions, counterparty fees still possible
- Bank payouts: local currency for the recipient, no crypto wallet required, destination fees can differ
- On-ramps and off-ramps: move between ordinary money and USDC through the supported payment stack
- Access: inside Samsung Wallet, no separate cryptocurrency application for the core flow
Fiat on-ramps and off-ramps sit underneath both paths. Eligible users are supposed to move between conventional money and USDC without building their own bridge. That is the part that makes this feel like payments infrastructure rather than a trading widget bolted onto a phone.
Who Holds The Dollars
Samsung is not asking you to babysit a seed phrase. That is the selling point, and it is also the trade. Someone else holds the asset.
Bastion is the cross-border payment framework. Coinbase is the official sub-custodian. USDC tied to the service is meant to sit in Coinbase Prime Vault. Bastion is described as a licensed stablecoin infrastructure and custody provider under U.S. regulatory oversight. Biometric checks on registered Galaxy devices are the user-facing lock before a transfer starts.
I like the honesty of a custody model when it is named out loud. A lot of consumer crypto still pretends you are sovereign while a help desk resets your access. Here the arrangement is institutional: a licensed operator, a prime vault, a phone biometric. You are a customer of a service, not the sole keyholder of a bearer asset. For rent money, that may be the correct shape. For someone who wanted censorship resistance, it is the wrong product, and pretending otherwise helps nobody.
There is history in the cap table, which is worth knowing before you treat the partnership as a cold procurement. Samsung Next had already been among Bastion’s investors. In September 2025, Coinbase Ventures led a $14.6 million round that also included Samsung Next, Sony Innovation Fund, a16z crypto, and Hashed. That round took Bastion’s total funding above $40 million. Capital ties do not prove the pipes will work. They do explain why these names keep appearing in the same sentence.
The Chains Under The Counter
Solana and Sui are named as technical partners for the blockchain infrastructure behind the service. Lily Liu, president of the Solana Foundation, called the integration the kind of adoption Solana was built for, and argued that stablecoins are becoming a way to move money outside traditional cryptocurrency apps. Alec Lovett, who leads infrastructure products at Coinbase, treated Samsung’s reach as a distribution milestone for USDC.
This level of adoption is what we built Solana for.
Lily Liu, president of the Solana Foundation
Perhaps the most interesting aspect is how little the end user is supposed to care which chain moved the dollar. If the product works, Solana and Sui stay in the press note and disappear from the thumb. If it stutters, those names will suddenly matter a great deal, because network conditions are explicitly part of the timing story.
A Year Of Warming The Seat
This October window did not appear from a blank slide. In October 2025, Samsung Wallet folded Coinbase services into the Galaxy ecosystem for roughly 75 million U.S. users. Eligible customers could trade and stake through the wallet, with promotional Coinbase One benefits attached. Samsung Pay had already become a funding option inside the Coinbase app, so money could move toward an exchange account from the phone’s payment surface.
Native stablecoin support was then flagged at Samsung’s Galaxy Unpacked event in July 2026. At that stage the company had not named the stablecoin, the launch week, or the infrastructure partners. The late-October plan fills those blanks: USDC first, Bastion and Coinbase on custody, Solana and Sui on rails, U.S. Galaxy devices as the opening map.
That sequence is how phone platforms usually eat a feature. First a partner tile. Then a balance. Then a send button that no longer feels like a detour. I have found that the dangerous moment is the second step, when the balance looks like cash and people stop asking what backs it.
A Patent Sitting Next To The Launch
On October 6, reporting described a U.S. patent application from Samsung for a digital asset wallet that uses smart contracts to authorize transactions without each device handling private keys directly. Phones, computers, wearables, and even home appliances could, in the proposed design, take part in managing a shared wallet. Samsung has not said this system will ship in any product.
Read it as a sketch, not a roadmap. The commercial service launching this month already avoids user-managed keys by putting custody with Bastion and Coinbase. The patent imagines a different trick: shared control across devices, authorized by contract logic. Those can coexist. They can also stay unrelated forever. Patent filings are how large hardware companies keep options warm. I would not budget around a refrigerator co-signing a transfer.
Payments At The Counter, Still A Maybe
Beyond transfers, Samsung is considering stablecoin payments at online merchants and physical stores. The picture it has floated is a tap at participating retail locations. No launch date. The feature remains under consideration, which is corporate for “we like the sentence and have not finished the arguments.”
Store payments are a harder product than a remittance button. A send to a wallet can fail in private. A tap at a checkout fails in a line, with a cashier and a stranger watching. Merchant acceptance, refunds, tax treatment, and what happens when the biometric hiccups all have to be boring before they are impressive. I would rather they ship the transfer path cleanly than rush a tap-to-pay story that stalls at the register.
Geographic expansion is tied to local rules. The first stablecoin service is limited to eligible U.S. Galaxy users. Samsung has linked the October timing to a U.S. regulatory framework for stablecoins. It has not announced a Samsung-branded stablecoin. USDC stays the opening asset. More detail on eligible devices, destinations, and extra capabilities is expected as the launch gets closer.
How The Pieces Fit On A Single Screen
If you strip the logos off, the stack looks like this. A phone wallet is the door. A regulated custody pair holds the token. Two high-throughput chains are named as plumbing. A bank-payout network is supposed to translate dollars into local currency on the far side. Biometrics are the human lock. Fees are split between “Samsung does not charge on wallet sends” and “everyone else might.”
| Piece | Role in the flow | What the user should notice |
| Samsung Wallet | Entry point on eligible U.S. Galaxy devices | No extra crypto app for the core send |
| USDC | First and default dollar stablecoin | Balance that is meant to track a dollar |
| Bastion | Cross-border payment framework | Mostly invisible if payouts clear |
| Coinbase Prime Vault | Sub-custody of the USDC | Institutional holding, not a self-custody key |
| Solana and Sui | Named blockchain infrastructure partners | Speed and hiccups, not a brand you tap |
| Bank recipients | Local currency in 60-plus countries | No wallet required on their side |
| Biometrics | Approval on a registered device | A thumb or face check before money leaves |
Tables like that are tidy. Real transfers are not. A recipient bank can reject a name mismatch. A wallet address can be one character wrong and still look plausible. A “supported country” can exclude the specific corridor you actually use. The announcement left the country list and the bank-fee detail unpublished. Until those land, the 60-country line is a headline, not a route map.
Why 82 Million Devices Is The Real Headline
Crypto products love user counts that describe signups. Phone products count hardware that is already in pockets. Eighty-two million U.S. Galaxy devices is a distribution number, not a promise that 82 million people will send USDC in week one. Still, distribution is the scarce ingredient. Most stablecoin apps spend years begging for a home-screen icon. Here the icon is the wallet people already open for a boarding pass.
That is why partners talk about milestones. A dollar token that clears inside a mass-market phone wallet does not need the recipient to share a culture. It needs the sender to trust the screen and the receiver to trust the deposit. Everything else is implementation.
I keep coming back to a smaller number from last year: about 75 million U.S. Galaxy users touched by the earlier Coinbase integration. The new figure is devices, not necessarily active wallet users, and the gap between “device can” and “person did” is where these launches usually shrink. If even a thin slice tries a cross-border send, the volume will show up in corridors that banks still price like a luxury.
Fees, In Plain Language
Samsung’s no-fee claim is narrow, and narrow claims are the ones worth keeping. No Samsung transfer fee on sends to compatible crypto wallets. That does not erase network costs if a route passes them through, and it does not bind the receiving venue. Bank transfers are a separate aisle. Destination fees may apply. Nobody has published a full schedule in the material that accompanied the announcement.
A practical way to think about it:
- Check whether the recipient is a wallet or a bank. The fee logic splits there.
- On a wallet send, assume Samsung’s own transfer fee is zero and then ask what the other side charges.
- On a bank send, assume a destination cost until a schedule says otherwise.
- Watch the spread on the buy and sell of USDC. On-ramps hide margin in the rate, not only in a line called fee.
- Save the confirmation. “Seconds” is a target, not a warranty.
Spreads deserve their own sentence. People fixate on the transfer fee because it has a name. The price at which dollars become USDC, and USDC becomes local currency, can cost more than a labeled fee and still look clean on a receipt. If you only compare the transfer line with a bank wire, you can congratulate yourself while the rate did the real work.
Security That Fits In A Thumb
Registered device. Biometric authentication. No user-held private key. That trio is the security story Samsung is willing to tell. It blocks the classic failure of a seed phrase photographed onto a cloud backup. It creates a different failure: the account, the device registration, and the custodian become the attack surface.
Phone biometrics are good at stopping a stranger who picked up an unlocked myth. They are weaker against a coerced thumb, a compromised Samsung account, or a support flow that can be talked into a reset. Custody adds professional controls and professional concentration risk. Coinbase Prime Vault is a serious room. Serious rooms are also single places where a policy change, a freeze, or an outage touches every balance at once.
None of that is a reason to sneer. It is a reason to know what you bought. Self-custody and custodial wallet transfers solve different fears. Mixing the slogans is how people get surprised.
A simple mental model before you send:
  Device trust  -> is this Galaxy registered to you
  Identity trust -> can the account be recovered by someone else
  Custody trust -> who can freeze or delay the USDC
  Route trust   -> wallet address or bank details, checked twice
What Recipients Actually Experience
The kindest design choice in the announcement is aimed at the person who did not ask to learn any of this. A bank recipient in a supported country is supposed to receive local currency without installing a wallet or holding a token. That is how remittances actually get used. The sender can be curious. The receiver usually wants rent, tuition, or a medical bill, in the currency the landlord already accepts.
Wallet recipients are a different crowd. They already have an address. They may care which chain the USDC arrives on, whether the venue credits it automatically, and what memo or tag is required. Samsung’s “compatible” label will do the filtering, and compatibility lists have a talent for excluding the one wallet your brother uses. Ask before you send. A test amount is not cowardice. It is how adults move money.
Timing will feel magical until it does not. Seconds is plausible on a quiet high-throughput network for a wallet credit. Bank payouts live on local clearing hours, name checks, and weekend calendars. If someone promises you that a Friday night bank leg in a second country will feel like a text message, they are selling a mood.
Regulation As The Starting Gun
Samsung has tied the October rollout to a U.S. framework for stablecoins being in place. That is the grown-up reason a hardware company would put a dollar token in a mass-market wallet. Consumer brands do not enjoy inventing their own monetary policy. They prefer a token with a known issuer, reserve rules they can point at, and a custodian already inside the regulatory conversation.
The company has not said it will issue a Samsung stablecoin. Good. A phone maker printing its own dollar is a different argument, with different conflicts. Sticking with USDC keeps the brand on distribution and experience, which is the part Samsung actually knows how to ship.
International expansion stays conditional. Each market has its own licensing, foreign-exchange, and consumer rules. A feature that is boring in the United States can be restricted, taxed differently, or simply unavailable two borders away. If you are reading this from outside the opening market, treat the 82 million figure as a U.S. device pool, not a promise that your Galaxy will grow a send button on the same week.
Where This Sits Against Ordinary Transfers
Bank wires and card remittances are slow in familiar ways. You know the fee is rude. You know the weekend is closed. You know the reference number will be asked for twice. Stablecoin routes are fast in unfamiliar ways. The failure modes are address errors, venue holds, and a support desk that speaks blockchain while you are trying to speak rent.
Samsung is trying to sand those edges by keeping the flow inside a wallet, naming a custodian, and offering a bank exit so the far side can stay in local currency. That is a credible shape for a consumer product. It will win corridors where the traditional fee is embarrassing and the recipient can take a bank credit. It will lose corridors where the destination bank is fussy, the amount is tiny, or the user needed the money to be a bearer asset nobody can pause.
In my experience, the first month of a feature like this is dominated by edge cases the demo never showed. A middle name. A wallet that wants USDC on a chain the send button did not offer. A biometric that fails after a screen protector change. The teams that publish a country list and a fee card early will spend less time in comment sections. The announcement, as it stands, still owes both.
Questions Worth Asking Before The Last Week Of October
Launch week will answer some of this. It will not answer it if nobody asks.
- Which exact Galaxy models and software versions count as eligible, not just the 82 million pool
- The country list for bank payouts, including any states or regions carved out
- A fee and spread schedule for buys, sells, wallet sends, and bank legs
- Which chains a wallet recipient should expect, given Solana and Sui are both named
- What “compatible wallet” excludes
- How freezes, recalls, and mistaken sends are handled once custody is in the loop
- Whether store payments stay a concept or get a date
I would also want a plain explanation of recovery. If the phone dies, does the balance follow the Samsung account, the Coinbase relationship, or a support ticket. Custodial products live or die on that paragraph. A biometric on a registered device is a lock. Recovery is the spare key, and spare keys are where stories go wrong.
A Note On Habits, Not Hype
There is a temptation to call every phone integration a turning point. Most are not. They are options. Options become infrastructure when a person uses them twice without narrating it. The second send is the one that matters. The first is curiosity. The second is a bill.
USDC already moves large sums between firms that do not need a Galaxy phone to do it. What changes here, if it works, is the on-ramp for someone who would never open a dedicated exchange. That person does not care that Solana’s president likes the adoption story. They care that a parent in another country saw the money before the weekend.
Chai’s line about convenience is the right test. If the flow feels like the wallet, people will stay. If it feels like a crypto detour wearing a Samsung skin, they will retreat to the wire they already resent. Skin is easy. Feel is not.
Partners, Incentives, And The Quiet Conflicts
Coinbase gains a distribution pipe for USDC and a deeper seat inside Galaxy after last year’s trading and staking integration. Bastion gains a flagship consumer corridor and a custodian relationship it can point to. Solana and Sui gain a chance to be the invisible rail under a household brand. Samsung gains a cross-border story that does not require it to become a bank overnight.
Incentives that line up can still produce a product you should use carefully. Samsung Next’s earlier investment in Bastion means the vendor was not a stranger. That can speed integration. It can also soften skepticism inside the building. Outside the building, you are allowed to stay skeptical until payouts clear on a Tuesday.
Lovett’s comment about global reach is fair as far as it goes. Reach is not usage. Usage is not profit. Profit is not trust. The sequence only looks inevitable in a keynote.
What I Would Do With A Small Amount First
This is not advice dressed as a product review. It is the habit I use whenever a familiar app grows a money button.
I would confirm eligibility on my own device rather than trust a headline count. I would buy a small slice of USDC and look at the rate against a dollar, not only the fee line. I would send a test to a wallet I control, then a test toward a bank account I can afford to see delayed. I would read the recovery screen before I need it. I would ignore any promise of in-store taps until a merchant I actually visit is on a list.
If the test bank leg arrives in local currency without the recipient installing anything, the product has earned a second try. If the country I care about is missing, the 60-country claim is someone else’s map. Both outcomes are useful. Only one of them is a reason to move rent.
The Part That Still Feels Unfinished
Samsung has a date window, a device pool, a token, a custody pair, two chain partners, and a bank-payout ambition. It does not yet have, in public, the dull documents that make money products feel safe: countries, fees, device cuts, chain defaults, error handling. Dull documents are how you tell a launch from a trailer.
I am willing to be impressed. A wallet send without a Samsung fee, landing in seconds, with the recipient free to stay in a normal bank account, would be a genuine improvement on a lot of corridors I have used. I am not willing to pretend the improvement is already measured. Measurement starts when strangers who do not read launch notes try to pay a school fee.
Until then, hold the story at the size it has earned. A major phone wallet in the United States is about to treat USDC as a default dollar rail for transfers, under named custody, with an eye on shops later and other countries if rules allow. That is a large door opening. Walking through it still requires looking at the floor.
A Closer Look At The Buy Button
Defaults are quiet tyrants. When USDC appears as the dollar stablecoin on the buy path, most people will not comparison-shop issuers inside a phone wallet. They will accept the token the screen offered, the way they accept the default tip percentage in a taxi app. That is not irrational. Comparing reserve attestations at a bus stop is a hobby, not a payment flow.
The responsibility therefore sits with the companies that chose the default. Samsung chose a widely used dollar token and a prime-custody arrangement rather than a house coin. That is the conservative version of this idea, and conservative is a compliment in payments. Still, a default can concentrate usage so hard that alternatives never get a fair tap. If a second stablecoin arrives later, it will have to fight a habit, not an empty menu.
I would watch the wording on that buy screen more carefully than the keynote quote. “Dollar” and “stable” are doing emotional work. The legal and reserve reality lives in disclosures people skip. A good wallet puts the skippable part one tap away, in language a non-specialist can finish. A weak wallet buries it under a partner logo and a progress spinner.
Cross-Border Is A Product, Not A Slogan
Moving value across borders sounds like one feature. It is a stack of small humiliations that each have to be removed. Name order. Character limits. Purpose-of-payment menus that assume you are a corporation. Weekend cutoff times. A recipient bank that wants a local phone number. Currency that arrives as the major unit and confuses everyone by a factor of a hundred.
Stablecoin middle legs remove some of those humiliations and invent others. The Samsung design tries to hide the middle from the recipient by paying out local currency. That is the right empathy. It only works if Bastion’s framework and the local payout partners have already swallowed the humiliations. Users will not see that labor. They will see a deposit or a delay. Delays need a human sentence, not a status code.
Sixty countries is a wide net. Wide nets snag odd cases. A country can be supported and a particular bank inside it can be awkward. If you are sending to a credit union, a mobile-money wallet that is not a bank, or a joint account with a naming quirk, assume you are the odd case until a test proves otherwise. The announcement did not claim every account type on earth. Readers will hear that claim anyway. Try not to.
Hardware Brands And Money Are An Uneasy Marriage
Phone makers have flirted with payments for years because the device is already the thing people reach for. Cards, tickets, transit, identity. A stablecoin balance is a logical next tile and a cultural leap. Tiles can be removed in a software update. Money that left the phone cannot.
That asymmetry should make the interface stricter than a loyalty stamp card. Confirmation screens should repeat the destination in boring detail. Bank sends should show the currency the recipient is expected to receive, not only the USDC leaving. Wallet sends should show the chain if more than one is possible. Speed is a feature. Ambiguity is a defect, even when the animation is lovely.
Samsung’s broader wallet already trains people to tap for small things. Extending that muscle memory to cross-border value is powerful and slightly dangerous. Muscle memory does not read country lists. Design has to slow the thumb at the exact moment the amount stops being a coffee.
What Success Would Look Like In Six Months
Not a viral clip of a transfer completing in four seconds. That clip will exist either way. Success looks duller. A published fee card that matches what users are charged. A country list that does not shrink quietly. Support articles that explain a held payout without telling the sender to “check the hash.” A second stablecoin only if the first path is already boringly reliable. Store payments only after refunds work.
Failure has a look too. A launch limited to a subset of the 82 million with no clear reason. Wallet sends that are free and bank sends that are opaque. A custody freeze that users learn about from a forum. An in-store demo that no merchant can repeat. I hope the first list is the one we are writing about in spring. Hope is not a control, which is why the test transfer still comes first.
There is room for this to be quietly important without being revolutionary. Quietly important is how payment habits actually change. Revolutionary is how slide decks talk. I will take the deposit that arrived.
Putting The October Window In Proportion
Last week of October is soon. Soon is not the same as ready, and ready is not the same as finished. Samsung has been walking toward this since the Coinbase tile, the Unpacked hint, and the Bastion relationship. The patent is a side door that may never open. The shop tap is a later chapter.
If you only remember one distinction, remember wallet versus bank. Fee-free, in Samsung’s wording, belongs to the compatible wallet send. Local currency without a crypto app belongs to the recipient bank path, with destination costs still in play. Custody sits with Bastion and Coinbase Prime, not in a phrase you wrote on paper. Solana and Sui are infrastructure names, not buttons you need to love. Biometrics are the check. Regulation is why a phone company is willing to do this in the United States first.
The rest is weather. Networks speed up and slow down. Banks close. Defaults shape behavior. Eighty-two million devices is a doorframe, not a crowd. Walk through with a small amount, a saved confirmation, and a little less romance than the launch deserves. Convenience is the promise. Clearing is the proof.
Before you send: destination type, amount, currency received, fee line, spread, recovery path.That checklist is unglamorous. So is money that arrives. I’ll take unglamorous.