
I kept rereading the financing line, the way you reread a restaurant bill when the tip math does not sit right. Overnight bank funding, plus four percentage points, paid by a fund that only wants twice the daily move in a memory-chip stock. That is not a crypto yield product dressed up in new clothes. That is the quiet, slightly unglamorous work Wall Street banks have done for years, and a firm better known for a payments token just walked into the room and asked for a seat.
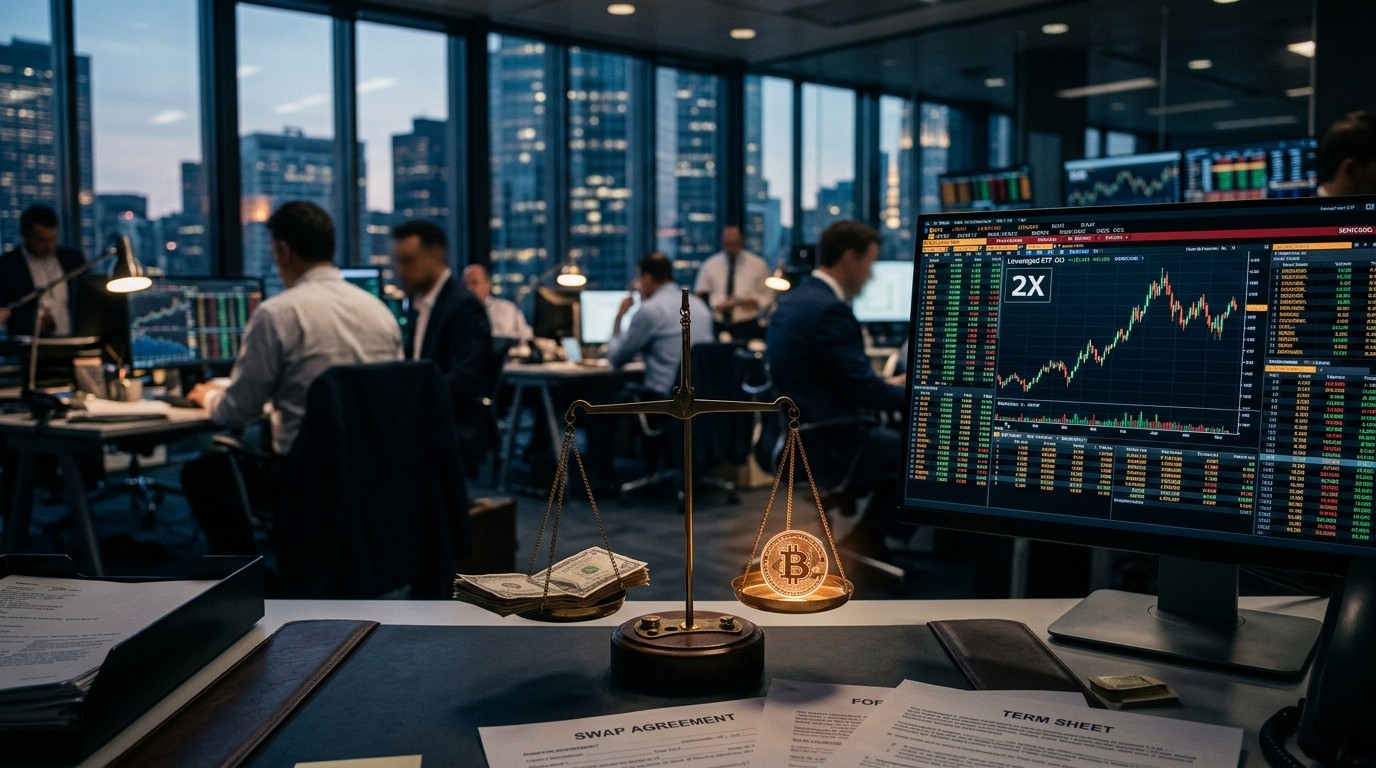
Ripple Prime is financing leveraged exchange-traded funds through stock-swap arrangements. One of the products on the other side of that arrangement is a fund built to deliver twice the daily performance of Sandisk shares. The fund pays a rate tied to the overnight bank funding benchmark, then adds four full percentage points. If you have ever wondered who actually gets paid when a 2x ticker looks effortless on a brokerage app, this is part of the answer.
Perhaps the most interesting part is how ordinary the mechanics are. No new blockchain ritual. No promise that the token will settle the trade by Friday. A brokerage supplies economic exposure, a fund pays financing, and the spread is the business. I have found that the deals which actually move an industry rarely arrive with a drumroll. They arrive as a line item.
Why A Crypto Name Is Sitting In A Bank Seat
Leveraged ETFs are a strange corner of public markets. They promise a multiple of a single day’s return, usually two or three times, on a stock or an index. They do not promise that multiple over a month, a quarter, or a year. The reset happens every session. Volatility, path, and compounding do the rest, and plenty of holders learn that lesson the expensive way.
To hit the daily target, a manager often does not buy two dollars of stock for every dollar of assets. The cleaner route is a total return swap. The brokerage agrees to pay the economic return of the shares. The fund agrees to pay a financing charge, plus whatever else the contract spells out. The brokerage then hedges, typically by owning the stock or offsetting the risk somewhere else. On paper it is simple. In practice it ties up balance sheet, collateral, and people who know how a borrow market behaves on a bad afternoon.
That last part is why the big banks owned this lane. They already had the stock inventory, the prime-brokerage clients, the regulatory capital, and the habit of pricing a spread when everyone else was busy watching the headline move. A new entrant does not beat them with a slogan. It beats them, if it beats them at all, by having capital, a license, and a client who would rather not wait in the old queue.
The Sandisk Deal Is A Price Tag, Not A Slogan
The reported arrangement around the Tradr 2X Long SNDK Daily ETF is useful because it is specific. The fund wants twice Sandisk’s daily performance. Ripple Prime stands on the financing side. The rate is the overnight bank funding benchmark plus four percentage points.
Four points is not a rounding error. On a large book it is a real revenue line. It is also a clue about risk. Single-name leverage, especially in a stock that can gap, is not priced like financing a broad index. Borrow can tighten. The hedge can slip. A name tied to memory chips can reprice on one supply headline before the swap desk has finished its coffee. I would not treat that spread as greed. I would treat it as the market saying the position is lively.
A leveraged fund does not borrow glamour. It borrows balance sheet, and someone has to charge for the inconvenience.
Financing costs move with the asset, the structure, and the bargaining power on each side. A liquid mega-cap index swap will not look like a single-stock deal on a name with a thinner borrow market. The Sandisk example is one window, not the whole shop. Still, it tells you the business is already live enough to have a posted rate, not a slide-deck concept.
What The Fund Actually Receives
Under a typical stock swap, the fund receives the agreed return of the reference shares, subject to the contract. Dividends, corporate actions, and the daily reset all have to be handled cleanly, or the ETF’s published objective starts to drift from what shareholders think they bought. The brokerage, meanwhile, manages its own exposure. Buy the shares. Offset with other trades. Post collateral. Revisit the hedge when volume dries up.
Ripple’s role here is the financing and derivatives side. The ETF sponsor still owns the strategy. That distinction matters. If the product disappoints over a choppy month, that is mostly the math of daily leverage, not a verdict on the swap counterparty. If the counterparty cannot perform, that is a different problem, and it is the one regulators and risk committees actually lose sleep over.
Daily Reset Is Where Retail Gets Surprised
Worth slowing down on this, because the marketing line and the holding-period reality are not the same sentence.
A fund seeking twice the daily move can finish a volatile week nowhere near twice the stock’s weekly move. Up 5, down 5, up 5 again does not stack into a tidy multiple. Each day the exposure is reset. The fund is constantly re-levering into a path, not compounding a static bet. Traders who live in this product know that. A lot of newer holders do not.
- The target is a multiple of one session, not of a month.
- Volatility decay is a feature of the math, not a hidden fee someone forgot to disclose.
- Financing cost sits underneath the headline multiple and quietly eats carry.
- A single-name product can gap harder than an index product with the same leverage label.
- The swap counterparty is part of the plumbing, not the investment thesis on the stock.
I have sat through enough “why is my 2x fund only up 6 percent” conversations to know the reset is the whole story. Anyone writing about this business without saying that out loud is selling a cleaner version than the market delivers.
How The Swap Desk Earns Its Keep
Strip away the ETF wrapper and the economics look like an old prime-brokerage trade. Client wants exposure. Desk provides it. Client pays a spread over a funding benchmark. Desk hedges, watches collateral, and hopes the name does not become impossible to borrow on the exact day the client adds size.
The four-point add-on over overnight bank funding is the visible piece. There can be other charges in a real contract: break fees, dividend adjustments, wider pricing if the hedge is messy. None of that needs to be scandalous. It needs to be priced so the desk still wants the trade after a rough week. Banks have done this forever. The novelty is the letterhead.
Where This Sits In The Market’s Plumbing
Leveraged products are a small slice of the ETF universe by count of sober long-term holders, and a much larger slice by noise. They pull stock borrows, options liquidity, and swap capacity into names that are already busy. When a new financing counterparty shows up, it does not create demand for Sandisk. It changes who gets paid to warehouse that demand.
That is a narrower claim than “crypto is taking over Wall Street,” and it is the one I trust. Capacity is the product. Spread is the price. Everything else is branding.
A Short Map Of The Trade
| Piece of the trade | Who carries it | What can go wrong |
| Daily leverage target | ETF sponsor and portfolio team | Path dependency over multi-day holds |
| Stock-swap exposure | Prime brokerage counterparty | Hedge slippage, borrow stress, gap risk |
| Financing rate | Paid by the fund to the desk | Spread too tight to survive a volatile name |
| Collateral and margin | Both sides, under the contract | Calls arriving faster than cash |
| Shareholder outcome | The end holder | Confusing a daily multiple with a long bet |
Look at that middle row again. That is the job Ripple Prime just took a piece of. Not the stock pick. Not the marketing of the ticker. The exposure, the hedge, and the fee.
The Acquisition That Made The Desk Possible
None of this appears out of a white paper. Ripple bought its way into institutional brokerage by acquiring Hidden Road for $1.25 billion. The deal was announced in April 2025 and closed that October, when the firm was renamed Ripple Prime.
Hidden Road already cleared and financed across asset classes for trading firms. The pitch, then and now, is the unsexy one: one relationship for clearing, financing, and market access, instead of five logins and four credit officers. Reported clearing activity sat around $3 trillion a year before the deal, and the business was later described as having roughly tripled from the announcement to the period after close. Figures like that deserve a raised eyebrow until you see the audited trail, but the direction is hard to miss. This was not a side project stapled to a token treasury.
After the close, the brokerage pushed further into conventional securities alongside digital assets. That sequence matters. You do not finance a U.S. stock ETF swap from a crypto-only desk. You need equity plumbing, and you need it bored and reliable.
Delta One Was The Dress Rehearsal
In August 2026 the firm launched a Delta One business. The product set is total return swaps on U.S. listed stocks, market indexes, and digital assets. Clients get economic exposure without holding the asset directly. The desk handles the swap, the financing, and the collateral.
Leveraged ETF financing is the same instrument pointed at a different client. A hedge fund wants Nvidia exposure without tying up the full cash outlay. An ETF sponsor wants twice Sandisk for a day, reset tomorrow, financed today. Same family of contract. Different reason for signing it. If you were looking for a moment where the strategy stopped being theoretical, Delta One was it. The ETF line is the follow-through.
The firm has also described the equity derivatives effort as financing and clearing, not a proprietary trading book and not a market-making desk. I like that framing, with a caveat. Every swap desk has an inventory problem the moment the hedge is imperfect. “No prop desk” is a business choice. It is not a magic shield against market risk.
Capital Came Before The Bragging Rights
Financing other people’s leverage is a balance-sheet sport. Before the ETF push, Ripple Prime raised $275 million in August 2026 through a private placement of senior unsecured notes sold to institutions. Proceeds were tagged for working capital and general corporate purposes as the U.S. brokerage expanded financing, clearing, and trading. KBRA put a BBB rating on the notes. Piper Sandler led the placement. Maturity, coupon, and the investor list were not disclosed, which is normal and also annoying if you like to underwrite stories from the outside.
That note deal followed a $200 million facility in May from funds managed by Neuberger Berman, structured around client demand rather than as a plain corporate IOU. The stated use was margin across digital assets, equities, fixed income, and foreign exchange. Stack the two and you get access to as much as $475 million of financing capacity, in different wrappers. Not bank-scale. Enough to matter in a niche, and enough to get a first ETF mandate.
Capital stack, as disclosed:
  $275 million senior unsecured notes (August 2026, BBB)
  $200 million demand-based facility (May, Neuberger Berman funds)
  Combined access: up to $475 million
  Regulatory net capital cited: more than $1 billion
Regulatory net capital above $1 billion, cited alongside the Delta One launch, is the number I would circle. Notes and facilities fund growth. Net capital is what lets a broker actually intermediate. Without it, the four-point spread is a fantasy.
Clients, Not Coins, Are The Real Scoreboard
The brokerage has pointed to more than 300 institutional clients: hedge funds, proprietary trading firms, liquidity providers. Services run through clearing, settlement, financing, and cross margining. That client list is the moat, if there is one. A swap desk with no flow is just a spreadsheet with opinions.
Earlier in the same week as the ETF reports, the firm expanded an agreement with Brevan Howard, the hedge fund group managing about $35 billion. The expanded relationship covers prime brokerage, clearing, and financing across traditional and digital markets. Alan McGroarty, the group’s chief operating officer, framed the platform as a way to improve trading operations and capital efficiency. That is COO language, which is to say it is about workflow and funding, not about a token price.
The relationship is older than the brokerage add-on. Funds tied to Brevan Howard affiliates joined a $500 million strategic round in November 2025, when Ripple marked itself at $40 billion. Other names in that round included investors affiliated with Fortress Investment Group and Citadel Securities, plus Pantera Capital, Galaxy Digital, and Marshall Wace. Strategic investors are not the same thing as swap clients. Still, it is hard to build a prime business while the people who allocate institutional capital refuse to return your calls. Some of them are already on the cap table.
Licenses First, Narratives Second
The U.S. regulatory footing predates the close of the Hidden Road deal. In April 2025 the firm obtained a FINRA broker-dealer license covering additional fixed-income brokerage, clearing, and financing. The next month it introduced over-the-counter, cash-settled cryptocurrency swaps for U.S. institutions through a U.K. entity overseen by the Financial Conduct Authority.
I keep coming back to that order of operations. License, then product, then a louder market. Crypto firms have a habit of reversing it. The ones that last in brokerage usually do not.
- Secure the broker-dealer permissions that let you touch the product.
- Buy or build a desk that already clears real flow.
- Add equity swaps once the credit and ops teams can support them.
- Only then take a financing mandate from an ETF that resets every day.
Skip a step and the four-point spread becomes a headline you regret. Follow the steps and you are, boringly, a broker.
Stablecoins Are Nearby, Not In This Trade
Ripple Prime has folded Ripple USD, the RLUSD stablecoin, into institutional services so eligible clients can post it as collateral. There is also a stated plan to shift some post-trade activity onto the XRP Ledger. Useful context. Easy to overread.
The leveraged ETF financing arrangements have not been identified as using RLUSD or XRP. That absence is the story, not a footnote. A stock-swap book for a U.S. listed product lives inside broker-dealer rules, custody chains, and funding benchmarks that predate any ledger. Collateral experiments can sit beside that book. They do not have to be the book. In my experience, the firms that blur those lines in press materials are the ones risk committees circle in red.
The interesting experiment is not whether a coin can touch the trade. It is whether the desk can run the trade without needing the coin at all.
Market structure note, paraphrased from the way desks actually talk
If RLUSD later shows up as eligible margin on an equity swap, that will be a second article. Right now the revenue line is old-fashioned funding spread. Pretending otherwise flatters the brand and muddies the risk.
XRP Barely Flinched, And That Tells You Something
When the financing news circulated, XRP was trading near $1.40 and down more than 5 percent over 24 hours. Technical dashboards leaned bearish, something like seven sell signals against five buy signals, depending on whose screen you trust. I do not worship those scoreboards. I do notice when a corporate expansion fails to catch a bid in the token.
Why would it? The ETF swap does not require XRP to function. Holders who price every brokerage headline as a demand shock for the token are negotiating with a story, not with the contract. A cleaner read is that Ripple is building fee income that does not need a rising token to justify the desk. Token holders can still benefit if the parent grows, distributes, or simply looks sturdier. They do not get an automatic claim on a Sandisk financing spread.
That gap between corporate progress and token reaction is going to keep frustrating people. It should. Conglomerates and coins do not mark to market on the same clock.
What Banks Lose If This Sticks
Do not picture a vault door swinging open. Picture a financing committee that used to have three phones to call, and now has four. Banks will not vanish from leveraged ETF swaps because a newer broker won a Sandisk mandate. Balance sheet, prime relationships, and the ability to internalize a hedge across a huge stock inventory are still enormous advantages.
What they can lose is the presumption. For a decade, if you launched a 2x single-stock product, your first calls were the usual names. A credible alternative changes the quote. Even a slightly worse operational fit can be useful if it keeps the incumbent honest on spread. Four points over overnight funding is rich enough that a second bid matters.
There is a cultural piece too, and I say this carefully. Bank desks have spent years telling crypto firms they were not serious about market structure. Some of that criticism was earned. Some of it was turf. A FINRA broker with a billion-plus in net capital, a hedge fund client managing tens of billions, and a live ETF swap is harder to wave away in a credit meeting. Not impossible. Harder.
Risks The Press Release Will Not Lead With
Every new financing counterparty arrives with the same invisible luggage. Here is the luggage.
- Hedge slippage. Providing the return is easy in a quiet tape. It is a different job when the stock halts, gaps, or becomes hard to borrow.
- Concentration. A flashy first mandate in one name is not a diversified book. One ugly Sandisk week should not define the desk, but it can define the quarter.
- Capital elasticity. Notes and a facility are not an infinite warehouse. Client demand can outrun funding, and then the spread you wanted becomes the trade you decline.
- Operational maturity. ETF sponsors care about corporate-action handling and morning files as much as they care about price. A missed reset is a reputation event.
- Narrative bleed. If clients or commentators assume the crypto stack is inside the equity swap, a problem in one business gets blamed on the other.
None of these are exotic. They are why this work stayed with banks. The open question is whether Ripple Prime’s ops culture, inherited in part from Hidden Road, is dull enough to do the job. Dull is a compliment in clearing.
How A Financing Spread Actually Compounds
People hear “four percentage points” and jump to a fantasy revenue number. Slow down. The spread applies to the financed exposure, not to the entire ETF market, and not every day looks like the day the mandate was signed. Utilization moves. Clients renegotiate. A desk that wins flow by being slightly cheaper will not hold four points forever.
Still, run the intuition. Financing a few hundred million of single-name leverage at a multi-point spread is meaningful for a broker that is still proving the equity line. It is a rounding error for a global bank. That mismatch is the strategic point. Ripple does not need to take the whole street. It needs a book large enough to justify the desk, the capital, and the people who answer the phone when a creation basket looks off.
I would rather see three boring mandates renewed than one loud one that never repeats. Renewal is the only review that counts.
Who Should Care, And Who Can Ignore It
If you hold the leveraged Sandisk product, you should know your financing counterparty exists and what you pay them, at least in outline. You should not rebuild your thesis around them. The stock, the daily reset, and your holding period still dominate the outcome.
If you allocate to crypto tokens, this is a parent-company story with a weak short-term link to price. Useful for judging whether the business is becoming a broker or remaining a narrative. Weak as a reason to buy the dip on a Tuesday.
If you work at a bank desk that prices these swaps, you already know why it matters. A new bid in the stack changes the conversation with the sponsor, even if you keep the trade. Especially if you keep the trade.
A Cleaner Way To Think About The Whole Push
Step back from the ticker. Ripple spent 2025 buying a prime broker, closing the deal, and inheriting flow. It spent 2026 raising notes, launching equity swaps, deepening a relationship with a multi-strategy hedge fund, and taking at least one leveraged ETF financing mandate at a spread wide enough to notice. Alongside that, it kept a stablecoin collateral option and a ledger plan that, so far, sit next to the equity business rather than inside it.
That is a brokerage build-out. It is not a raid, and it is not a rebrand of the token. Calling it a challenge to Wall Street is fair only in the narrow sense that a new counterparty is challenging incumbents for a fee pool they assumed was theirs. Fair. Also incomplete, unless you mention capital, licenses, and the daily grind of hedges.
The phrase I keep using with readers who want a simpler moral is this: watch the renewal, not the announcement. A first Sandisk swap is a foot in the door. A second name, a third sponsor, a spread that survives a volatile quarter, those are the signs the door stayed open. Banks have lost niches before, usually slowly, usually to firms that were willing to do the unfashionable work at a price the client would sign.
Questions Worth Asking Next
A few of them are still open, and pretending otherwise would be sloppy.
- How many ETF sponsors are actually live, versus one disclosed example?
- Does the four-point spread hold once a second broker bids the same name?
- Will single-stock leverage stay the focus, or does the desk migrate toward index products where the hedge is kinder?
- How much of the $475 million financing stack is already spoken for by margin clients?
- If post-trade experiments move to a ledger later, which pieces move, and which stay in traditional custody on purpose?
I do not have private answers. Anyone who claims to, from the outside, is guessing with confidence. The public record is enough to say the business is real, the fee is visible, and the token was not required for the trade to exist.
What I Would Watch On A Desk Like This
If I were underwriting the story rather than summarizing it, the checklist would be stubbornly plain. Net capital trend, not a single cited figure. Client count that keeps growing after the launch headlines fade. A mix of names so one semiconductor gap cannot define the P&L. Evidence that ETF operations, the morning files and the corporate actions, are boring. And a clear wall between stablecoin collateral experiments and the equity swap book until someone can explain the legal path in one page.
Glamour fails that checklist on purpose. The financing business is supposed to feel like a utility. The moment it feels like a campaign, I get cautious. Campaigns slip on resets. Utilities invoice.
Desk health, roughly: capital coverage + hedge quality + repeat mandates - narrative bleedNot elegant. Useful. You can apply it to a bank desk too, which is sort of the point. The standard did not change because the logo did.
The Part Holders Keep Skipping
There is a temptation, especially in crypto circles, to treat every institutional contract as latent demand for the associated token. Sometimes that link is real. A payments corridor that settles in a specific asset is one thing. A stock swap priced off an overnight bank funding benchmark is another. Mixing them flatters a chart and insults the contract.
Holders can still care. A parent with fee income, regulated entities, and hedge-fund clients is a different risk than a parent with a treasury and a story. Fee income can fund product, employ people, and reduce the need to sell tokens into weakness. It can also distract management, soak up capital, and create reputational ties to products, like daily-reset leverage, that blow up in public for reasons that have nothing to do with the broker. Both outcomes fit inside the same press cycle. Only the next few quarters separate them.
So when the price shrugs, I do not read it as the market “missing” the news. I read it as the market refusing to pay today for a financing spread it does not own. That refusal can be wrong. It is not confused.
A Note On Leverage Itself
Nothing in this build-out makes a 2x fund a better long-term holding. The product was a trading tool before Ripple touched the financing, and it remains one. Path dependency does not care who intermediates the swap. A calm uptrend can flatter the multiple. A choppy range can punish it even when the underlying stock finishes flat. Financing cost makes the punishment a little worse, which is another reason the spread belongs in the conversation and not only in a footnote for professionals.
If you use these funds, size them as trades. If you do not, the financing news is industry structure, not a signal to open a position in a memory stock you had not researched. I would rather be dull on that point than helpful in the wrong direction.
Where The Story Goes If It Works
Success here looks quiet. More sponsors. A mix of single names and indexes. Spreads that compress a bit because competition showed up, and a book that still clears its cost of capital. Cross-margining that actually lets a multi-asset client use equity and digital exposure in one relationship without a quarterly surprise. Maybe, later, collateral options that include a stablecoin for clients who want it, clearly optional, clearly disclosed.
Failure looks loud. A hedge that gaps, a client dispute over a reset, a capital raise that signals the first stack was not enough, or a slow fade where the Sandisk mandate remains the only example anyone can cite. Brokerage businesses die in the fade more often than in the explosion. The explosion gets the article. The fade gets the asterisk a year later.
I lean toward the quiet path being available, not guaranteed. The licenses are in place, the client logos are real, and the instrument is one the street already understands. That is a better starting point than most crypto-adjacent expansions I have watched. It is still a starting point.
Banks will not hand over the lane. They will reprice, bundle, and remind sponsors how many other services sit on the same relationship. Some sponsors will stay for that bundle. Some will split the financing just to keep a second phone number alive. Both reactions count as impact. Only one of them shows up as a lost mandate in a bank’s internal review.
Either way, the four points over overnight funding are already doing their job. They tell you the trade is priced like risk, not like a demo. For a business trying to be taken seriously in a room that has ignored it, that is the right kind of sentence to be in.