

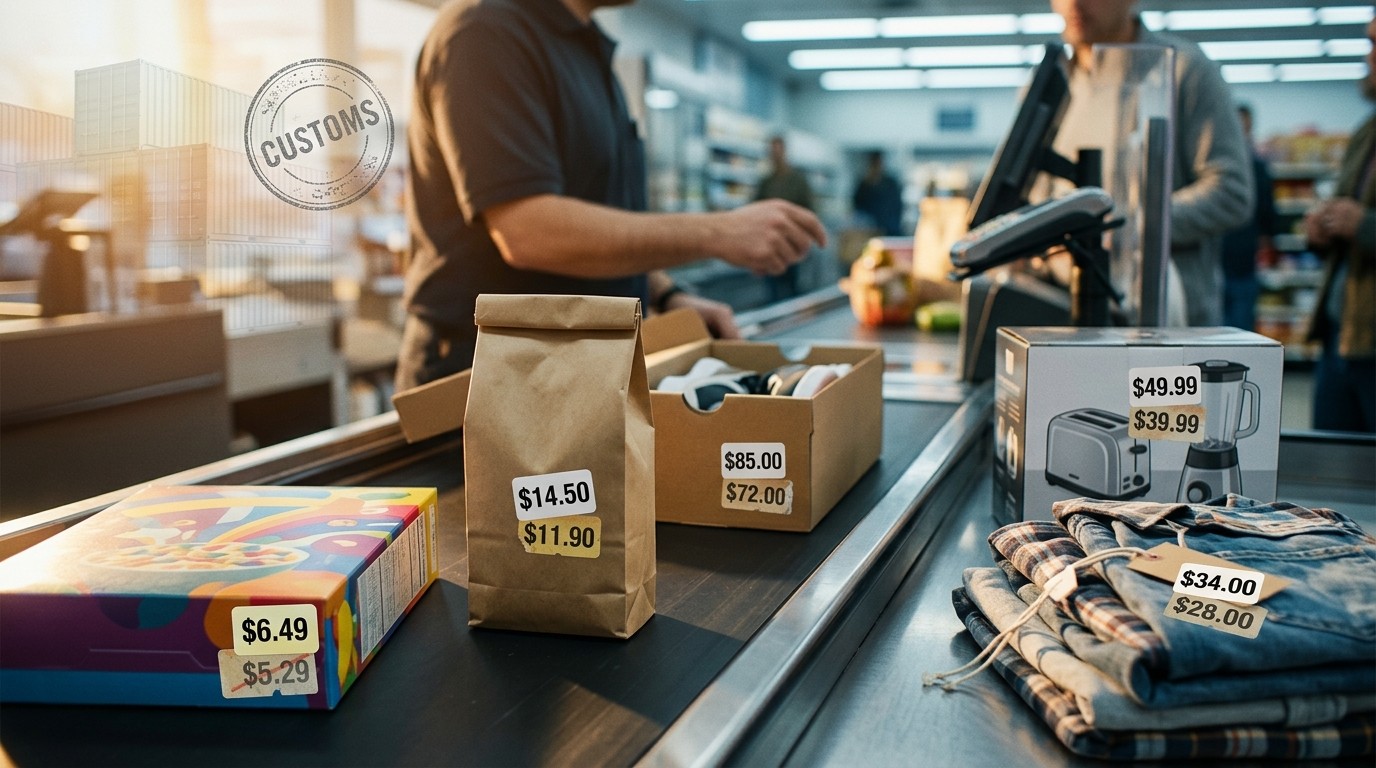

I kept waiting for the receipt to feel lighter. Coffee, a basic appliance, a pair of shoes that used to sit in the same aisle at the same price for months. The story going around kitchens and group chats was simple: once the supply snarls eased, everyday goods would drift down. They did not. A fresh look at a wide basket of products says the missing decline was not a mystery of demand. It was mostly the bill attached at the border.
Researchers tracking 67 kinds of goods found that, by February, prices in that sample sat about 2.9 percentage points higher than they would have without the levies rolled out in 2025 and early 2026. Strip those charges out, and the same basket would have slipped by nearly 1 percent. That is not a rounding error on a single receipt. It is the difference between a quiet disinflation in stuff you can hold, and a year that still felt sticky at the shelf.
What the Price Gap Actually Measured
The work is narrower than a headline inflation print, and that is why it is useful. It does not try to explain rent, medical care, or the cost of a haircut. It looks at goods, the category where imported inputs and finished products meet a cash register. Within that slice, the team compared what happened with what a counterfactual path suggested would have happened if the new charges had never landed.
I have found that people argue past each other on this topic because they are staring at different clocks. One person remembers a single dramatic announcement. Another remembers the slow rewrite of a supplier contract three quarters later. The research sits in the second clock. It asks what the basket looked like after firms had time to reprice, reroute, and decide who would eat the extra cost.
The authors did not publish the full shopping list behind those 67 categories. That is frustrating if you want to map the finding onto your own cart. It is also typical of this kind of study, which cares more about the average response than about naming a brand of toaster. Still, the direction is hard to miss. Goods that were supposed to cool off stayed warm.
A Counterfactual That Is Easy to Picture
Think of two parallel aisles. In one, the levy exists. In the other, it does not, and everything else, demand, wages, freight, the weather on shipping lanes, stays as close as the model can manage. The gap between those aisles is the estimate. By February, that gap was 2.9 points. The no-levy aisle was not flat. It was slightly cheaper than the year before, by almost a full percent.
Perhaps the most interesting aspect is how ordinary that missing decline would have felt. Shoppers do not celebrate a 1 percent dip. They notice it as a small mercy: the same box costs a little less, or the sale price sticks around. Losing that mercy, and adding nearly three points on top, is how a policy that sounds abstract becomes a weekly argument about the grocery total.
Tariffs have a larger and more drawn-out impact on consumer prices than the direct effect alone would suggest.
Central bank research team
That line is the heart of the paper, and it is worth sitting with. A levy is not a light switch on a price tag. It is a shock that travels through contracts, inventories, and the quiet math of what a domestic factory pays for parts.
How Much of a Levy Shows Up Later
The team put a simple rule of thumb next to the bigger result. For each percentage point rise in the average tariff, consumer goods prices were higher by roughly a quarter of a percent a year later. A quarter. Not one for one. Not zero. Somewhere in the messy middle, which is where most real pricing lives.
If you have ever watched a retailer absorb a cost for a season and then nudge the tag after the holiday window, you already know this rhythm. Pass-through is partial, lagged, and uneven. Some categories move fast because the product is imported finished and the margin is thin. Others move late because the import is a component buried inside a domestic assembly line.
Direct Charges and the Knock-On Bill
Roughly two-thirds of the tariff-related price impact came straight from the levies themselves. The rest came from knock-on effects. Domestic firms that buy imported parts and materials do not get a free pass just because the final product carries a local label. When the input costs more, the finished good often follows, sometimes with a delay that makes the cause harder to see.
I keep coming back to that split because it answers a common objection. People say, fairly, that a border charge should not touch a product made down the road. Sometimes it does not. Often it does, once you open the bill of materials. Steel, chips, fabric, packaging, a motor, a fastener. The border is closer to the factory floor than the marketing copy suggests.
- About two-thirds of the measured price effect traced to the levy itself
- The remaining third came from upstream costs inside domestic production
- The full consumer impact ran longer than the first invoice at the port
- Annual goods-price growth in the sample peaked at the start of 2026
- Elevated prices were still expected to linger into 2027
None of that requires a conspiracy. It requires ordinary firms protecting a margin, and ordinary shoppers with fewer substitutes than they would like.
Who Actually Paid the Increase
There was a loud claim, repeated often, that companies would swallow the extra cost rather than hand it to shoppers. The research does not say that claim was pure fiction. It says the swallow was incomplete. Around 26 percent of last year’s tariff increases ended up in higher prices. The other three-quarters stayed somewhere else: in supplier concessions, in thinner margins, in delayed investment, in a quieter product line.
Twenty-six percent can sound small if you wanted a scare story, and large if you wanted a free lunch. I read it as a partial pass-through with a long tail. The share that reaches the tag is the part you can photograph. The share that does not is still a cost. It just shows up as fewer discounts, slower wage bumps at a supplier, or a model that never gets refreshed.
| Finding | What the sample showed | Why it matters at home |
| Price gap by February | About 2.9 points higher with levies | The basket did not get the decline that was otherwise in train |
| No-levy path | Nearly 1 percent lower | Goods disinflation was real, then interrupted |
| Later response | Roughly 0.25 point of price per 1 point of tariff | Pass-through is partial and delayed, not instant |
| Share reaching tags | About 26 percent of the increase | Firms absorbed most, shoppers still paid a visible slice |
| Timing | Peak growth early 2026, drag into 2027 | The receipt effect outlasts the headline announcement |
Tables flatten a messy year. They also stop the argument from floating. The numbers are estimates, not scripture. They are still the clearest map we have of this particular episode.
Why the Estimate Was So Hard to Pin Down
Economists had expected levies to lift prices. The fight was over size and speed. Policy kept shifting. Rates were announced, paused, revised, aimed at one set of partners and then another. Companies do not publish a clean diary of how they set a tag. Some eat a cost to hold market share. Some raise the tag and blame freight. Some do both in different regions.
That fog is why a structured counterfactual matters. Without it, every price move gets claimed by whoever is talking. A hot summer, a strike, a chip shortage, a sale that ended. The study tries to hold those other forces steady enough to see the levy. It will not satisfy anyone who wants a single villain for every dollar. It should satisfy anyone who wants a measured gap.
In my experience, the public debate skips this step. It jumps from the press conference to the anecdote. A carton of eggs is not a tariff story. A blender with an imported motor might be. Sorting those is dull work. It is also the only way the claim stays honest.
The Peak, and the Long Aftertaste
Annual price growth in the tracked goods peaked at the start of 2026. That timing fits a lagged pass-through. Firms do not reprice the morning a decree lands. They work through inventory bought at the old cost, then reset. By the time the peak shows up in the data, the political argument has often moved on.
The aftertaste is the part households will notice longer. The same research expects consumers to pay elevated prices into 2027 because of the policy. Not because every rate stays at its highest setting. Because price levels ratchet. A tag that stepped up does not always step back down when the legal basis changes. Retailers like a higher reference price. Suppliers like a contract that already cleared.
A price level is sticky in a way a growth rate is not. Once the shelf has reset, getting the old number back is a separate fight.
That is my reading, not a line from the paper. It matches what the lag structure implies. Growth can cool while the level stays inconvenient.
Courts, Refunds, and the Rate That Remained
In February the high court struck down many of the levies, and retailers began seeing billions in refunds. That sounds, on a headline, like a full rewind. It was not. The policy did not vanish. Alternative measures stayed in view, and products from many countries often still faced charges around 10 percent. In plenty of cases that was well below the earlier round. It was not zero.
Refunds help the firms that paid the original bill. They do not automatically reprint last year’s shelf label. A shopper who paid the higher price in the autumn does not get a quiet credit in the spring. The legal win and the household experience travel on different schedules. Anyone budgeting weekly feels the second one.
Would a clean repeal have pulled goods prices back toward that missing 1 percent decline? Maybe partly, and slowly. The research is about the path that actually ran, not a promise about the next statute. Still, a lower residual rate is not the same thing as no rate. Ten percent is a real wedge on a thin-margin import.
What Partial Pass-Through Hides
If only about a quarter of the increase reached the consumer price, where did the rest go? A few places, none of them glamorous.
- Exporters trimmed their own prices to keep the order, eating part of the levy abroad
- Importers and retailers cut margin, especially where a rival could switch suppliers
- Some volume simply did not happen: a sku dropped, a promotion cancelled, a redesign delayed
- Domestic substitutes gained a little pricing power without matching the full foreign hike
The fourth item is the sneaky one. You do not need the imported good itself to get more expensive for the aisle to feel tighter. A local alternative can drift up because the outside option got worse. Shoppers call that greed. Economists call it the competing price. Both can be true in the same week.
I have watched small retailers do this without a spreadsheet sermon. They see the landed cost, they see what the chain across town is charging, and they pick a number that does not lose the Saturday crowd. That number is rarely the full levy. It is rarely zero either.
Goods Versus the Rest of the Basket
It helps to keep the boundary straight. This finding is about goods, not the whole cost of living. Services, shelter, and insurance have their own engines. A household can feel squeezed by rent even in a year when toasters cool off. The reverse happened here in the sample: goods that had room to ease did not ease.
That distinction matters for anyone reading a single inflation number and deciding the story is over. Aggregate prints mix categories that move for different reasons. A goods-specific gap can be large while the headline looks merely firm. Or the headline can look hot for reasons that have nothing to do with a customs form. Mixing them up is how bad policy arguments get born.
A simple way to hold the result:
  Sample: 67 goods categories
  Gap by February: about +2.9 points versus no-levy path
  No-levy path: nearly -1 percent
  Later rule of thumb: ~0.25 price point per tariff point
  Direct share: about two-thirds
  Knock-on share: about one-third
  Share of increase in consumer prices: about 26 percent
  Expected drag: into 2027
Pin that card to the argument. It will not settle every dinner-table fight. It will stop the fight from inventing numbers.
How a Household Actually Feels a 2.9 Point Gap
Percentages float. Carts do not. Take a goods spend that runs a few hundred dollars a month on the kinds of items in a broad sample: clothing replacements, small electronics, pantry staples that travel, household basics. A gap of nearly three points is not a new car. It is the sale that never arrived, repeated. Over a year it becomes a trip not taken, a repair delayed, a savings transfer that stays hypothetical.
Lower-income households spend a larger share of income on goods with thin substitutes. They also have less room to wait for a restock at a better price. So the same percentage gap is not the same experience. That is not a footnote. It is the distribution hiding inside an average.
Does that mean every family paid exactly 2.9 points more on every item? No. Some paid more, some switched brands, some bought less. The average still moved. Averages are how we talk about a country. Receipts are how we live in one.
The Substitution Story, and Its Limits
A standard reply is that people just buy something else. Sometimes they do. A different country of origin, a plainer model, a store brand. Substitution is real, and it is one reason pass-through is not 100 percent. It is also bounded. You cannot substitute your way out of a category if the whole category reset. You can only trade down inside it.
Trading down has a quality cost that price indexes catch only partly. The shirt lasts fewer washes. The appliance has a shorter warranty. The coffee is fine until it is not. Those losses do not always show up as inflation. They show up as irritation, which is harder to chart and just as real.
Perhaps that is why the political claim and the research claim keep missing each other. One side counts the dollars that moved. The other counts the options that shrank. Both are describing the same aisle.
Inventories Delayed the Pain, Then Delivered It
Early on, a lot of product was already in warehouses at the old cost. That created a grace period. Tags did not jump the week the policy did. Commentators treated the grace period as proof that nothing would happen. Then the warehouses turned over.
The peak in annual goods-price growth at the start of 2026 lines up with that turnover. It is the least dramatic part of the story and the most predictive. If you want to know when a border charge reaches a shopper, ask how many months of stock the category holds. Apparel is not steel. A phone charger is not a sofa. The lag is a feature of the product, not a flaw in the theory.
Firms that front-loaded imports before a rate rose bought themselves time. They also pulled demand forward, which can make the next quarter look soft for reasons that have nothing to do with the shopper losing interest. Reading those quarters without the stock story is how people declare a policy costless, then act surprised a year later.
Margins Are a Shock Absorber With a Limit
Retail margins absorbed a large share of the hit. That is what the 26 percent figure is telling you, read from the other side. Absorption is not infinite. A chain can run a thinner margin for a season if volume holds and the capital markets stay calm. A smaller seller often cannot. The same levy is a nuisance to one balance sheet and a closing sale to another.
I do not think that unevenness gets enough airtime. National averages flatten it. The shop that survives by a few points of gross margin does not experience a partial pass-through as a technical result. It experiences it as a choice between raising the tag and cutting hours. Either choice lands on someone.
There is a temptation to treat margin compression as a free offset, a way the economy “handles” a levy without households noticing. Compression is noticed by the people whose pay depends on it. It is just noticed off the consumer price index.
Currency, Freight, and the Other Moving Parts
A fair reader will ask what else was moving. Exchange rates can cushion a levy if the exporter’s currency weakens. Freight rates can fall and mask a charge, or rise and pile on. Energy costs leak into plastics and transport. The study’s job was to isolate the tariff piece from that crowd. No isolation is perfect. The direction, a goods basket that would have eased and did not, is robust enough to take seriously.
If freight had collapsed at the same moment, some of the levy could have hidden inside a cheaper voyage. Shoppers would still have missed the decline they were due. Hiding is not erasing. The counterfactual is the right question: not “did prices explode,” but “did they fall when they otherwise would have.”
That framing is less useful for a slogan and more useful for a budget. Explosions are rare. Missed declines are common, and they compound.
What a 10 Percent Residual Rate Still Does
After the court decision, many imports faced something nearer 10 percent than the earlier, steeper schedule. People heard “lower” and filed the issue away. Lower than a peak is not the same as harmless. Run the paper’s own rule of thumb loosely in your head. A quarter of a percent of price per point of tariff, a year out, is not nothing at 10 points. It is a couple of points of goods prices if the relationship holds, before you even add the knock-on channel.
I would not treat that back-of-envelope as a forecast. The relationship was estimated on a specific episode, with specific evasion options and specific demand. A stable 10 percent is easier for firms to plan around than a rate that lurches. Planning can mean smoother pass-through, or smarter sourcing that blunts it. We will know which when the next year’s tags are in.
The honest interim statement is simpler. The steepest version was knocked back. A meaningful wedge remained. Prices that had already reset were not required to apologize.
Refunds Are a Corporate Event First
Billions in refunds sound like a consumer victory if you stop at the verb. Follow the noun. The money goes back to the firms that paid the duty. What they do next is a business decision. Some will fund promotions, because competition forces them. Some will rebuild margin that got crushed. Some will sit on cash because the next rule is unclear.
Shoppers should not budget for a refund that has their name on it. They should watch promotions in the categories that were most exposed, and not assume the old price is a right. Legal repayment and retail generosity are different instruments.
There is a reasonable case that some of the refund will leak into lower tags where rivals are fierce. There is an equally reasonable case that it will not, because the reference price already moved and demand did not collapse. Both can show up in different aisles of the same store. That is annoying. It is also how retail works.
Reading the Finding Without a Team Jersey
Trade policy collects true believers. One camp treats any levy as a tax on families and stops there. Another treats any complaint about prices as an attack on domestic production. The research does not sign either jersey. It says the goods basket was materially higher than a no-levy path, that pass-through was partial, and that the effect runs longer than the direct invoice.
You can believe targeted trade measures sometimes serve a strategic aim and still accept that shoppers paid for this round. Those are not contradictory sentences. They are a cost-benefit problem with the cost now better measured. Pretending the cost was zero was always the weak move. Pretending the only thing that matters is the cost, with no other objective on the table, is the mirror-image weak move.
I would rather see the argument conducted with the 2.9 point gap in view. It disciplines both sides. It stops the “companies will eat it” promise from surviving contact with a receipt. It also stops the claim that every price in the economy is a customs story.
What Shoppers Can Actually Watch
You cannot audit a research sample from the checkout line. You can watch a few practical signals that rhyme with it.
- Whether sale depth in imported household goods returns to older patterns or stays shallow
- Whether store brands stop undercutting the names they used to trail by a wide gap
- Whether small appliances and basics get redesigned into cheaper specs instead of cheaper prices
- Whether promotional calendars slip, especially after inventory bought at the high rate clears
- Whether a 10 percent residual charge gets quoted openly by sellers, or folded into a new “everyday” tag
None of those is proof. Together they tell you if the level is sticking. A growth rate can fall while every one of those signals stays tight. That is the 2027 problem the paper flags, translated into things a person can see.
Businesses Pricing Into Uncertainty
Firms hate a moving target more than they hate a known cost. A stable levy can be modeled. A levy that might be struck down, replaced, or widened cannot. Uncertainty itself pushes some of them to price for the worse case, then “forget” to walk it back if the worse case does not arrive. That is not a conspiracy. It is inventory risk management with a marketing department attached.
The court ruling reduced one kind of uncertainty and introduced another, because alternative measures were still on the table. Planning a sourcing shift takes quarters. Planning a price cut takes a meeting, and then a rival’s reaction. In that gap, tags stay where they are.
If you run a small import-heavy line, you already know the feeling. You do not reprint a catalog because a headline sounds friendly. You reprint it when the next purchase order clears at a number you trust.
The Domestic Input Channel, Up Close
The knock-on third of the effect deserves a slower look. A factory that stamps, sews, or assembles in the country still buys from abroad. When those purchases cost more, the manager has the same menu as the retailer: absorb, reprice, reformulate, or drop the sku. Reformulating sounds clean. It often means a cheaper component, which is a quality choice dressed up as a supply-chain choice.
This channel is why a “buy local” label is not a full shield. Local can mean final assembly. It can mean a brand with a domestic headquarters. It rarely means every gram of the product started and ended inside one border. The more tangled the bill of materials, the more a levy on inputs behaves like a levy on the finished good, just with worse paperwork.
Shoppers are not wrong to feel misled when a domestic brand rises with an import charge. They are incomplete if they think the brand invented the increase. The charge arrived in a crate of parts. The brand decided not to swallow all of it.
A Year Later, the Quarter-Point Rule
The quarter-point response per tariff point, measured a year on, is the kind of number that should humble forecasters. It says the world is not a textbook with instant full pass-through. It also says the world is not a press release in which consumers are spared. Partial and delayed is the grown-up description.
Use it as a scale, not a law. Categories differ. A commodity with a public price might move faster. A branded good with a sticky tag might move slower and then stick harder. The average hides that spread. The average is still the right first cut when someone claims the effect was either total or imaginary.
Rough scale, not a forecast:
1 point of average tariff
  → about 0.25 point higher goods prices a year later
Direct channel ≈ two-thirds of the consumer impact
Input channel ≈ one-third
Share of the levy increase seen in prices ≈ 26 percent
If a future round is larger, do not multiply blindly and call it science. Do notice that the last round already left a mark you can describe without adjectives.
Why “Would Have Fallen” Is the Right Verb
Inflation debates obsess over whether prices rose. Goods debates, in a cooling cycle, should obsess over whether prices fell. The sample was on a path to decline. The levies interrupted it. Saying “inflation was caused by tariffs” is close, and slightly sloppy. Saying the decline that was due did not arrive, and a gap of 2.9 points opened instead, is closer to the evidence.
That wording also explains the mood. People expected relief in stuff. Relief is a decline, not a slower increase. Missing relief feels like a broken promise even when the index never spikes. The research gives that feeling a number.
I suspect this is why the finding will outlast the news cycle. Households remember the year the thing was supposed to get cheaper and did not. They do not remember the speech.
What Would Change the Picture From Here
A few developments could still bend the path the paper sketches into 2027. None of them is guaranteed.
- A durable cut in residual rates, followed by actual tag reductions rather than fatter margins
- A sourcing shift that replaces exposed inputs without a quality drop shoppers reject
- Softer demand that forces promotions deeper than firms currently plan
- A currency move that cheapens the import bill enough to offset the remaining wedge
- Competitive entry in categories where one or two sellers have been happy with the new level
Notice what is missing. A court headline, by itself, is not on the list. Legal status matters only if it changes the cost a buyer actually pays and the price a seller actually posts. The chain from ruling to receipt is long. Anyone selling certainty about next spring’s tags is selling something the data do not yet support.
A Cleaner Way to Talk About the Episode
Here is the version I would actually use, if the goal is to be understood rather than to win a clip. A broad set of goods was on track to get a bit cheaper. Levies imposed in 2025 and early 2026 left that set about 2.9 points higher by February than the no-levy path. Without the charges, prices in the study would have eased by nearly 1 percent. Roughly two-thirds of the consumer impact was direct, the rest ran through domestic users of imported inputs. About a quarter of the tariff increase showed up in prices. The pressure peaked as 2026 began and was not expected to vanish in 2027. Later, many of the original levies were thrown out, refunds started, and a lower residual charge, often near 10 percent, remained in view.
That paragraph has no slogan in it. It is still the whole story. You can add a value judgment after it. You should not replace it with one.
The useful question is not whether a levy can ever be justified. It is whether the price you were promised, the one where companies simply absorb the cost, survived contact with the shelf.
On this evidence, it did not. Not fully. Not quickly. Not in a way a careful shopper would miss.
Living With a Higher Reference Price
Reference prices are stubborn. Once a blender “costs” a new number, the old number starts to look like a discount rather than a baseline. Retailers know this. They would rather offer 15 percent off a higher tag than restore the prior tag and call it normal. Shoppers who track unit prices catch the trick. Shoppers who track the percent-off badge do not.
The drag into 2027 is partly this psychology, partly contracts, partly the residual rate. Unwinding it takes either competition or a cost drop large enough to make the old tag profitable again. Competition is local and uneven. A cost drop depends on policy, currency, and freight, none of which a household controls.
So the practical stance is dull, which is usually a sign it is right. Assume the level sticks until the tags prove otherwise. Treat a promotion as a data point, not a new era. And separate the goods story from rent, care, and insurance, or you will blame the wrong cause on the wrong Tuesday.
Where the Estimate Can Still Be Wrong
No counterfactual is a photograph. If the model underweighted a simultaneous demand surge, some of the gap is not the levy. If firms would have raised tags anyway after years of volatile costs, the no-levy path is too kind. If evasion and rerouting were larger than measured, the consumer hit is overstated. These are real caveats. They are not a license to set the result aside.
The honest range is wider than a single 2.9. The honest center is still above zero, and on the side of a missed decline. Anyone selling a precise-to-the-tenth story is overconfident. Anyone selling a zero story is ignoring the best map we have.
I would update my view if a later cut of the same method, with the post-ruling rates fully in the sample, showed the gap closing fast. Until then, the shelf is the scoreboard.
Putting the Receipt Next to the Policy
Trade measures get argued in the language of factories, leverage, and fairness. They are paid in the language of receipts. This round’s receipt, for a wide goods basket, was a missing decline of nearly 1 percent and an extra gap of about 2.9 points by February, with a tail that researchers still see running into 2027. Firms ate most of the increase. Shoppers ate enough to notice. Domestic products were not a bunker, because parts cross borders even when brands do not.
The later legal knock-back changed the forward rate more than it rewrote the past tag. Refunds repaired some corporate cash flows. They did not mail a credit to everyone who paid the higher price. A residual charge near 10 percent is a calmer policy than the peak. Calm is not free.
If you want a single takeaway, take the verb. Goods prices would have fallen. They did not. The distance between those two sentences is the cost, and it is still sitting in the aisle.



