

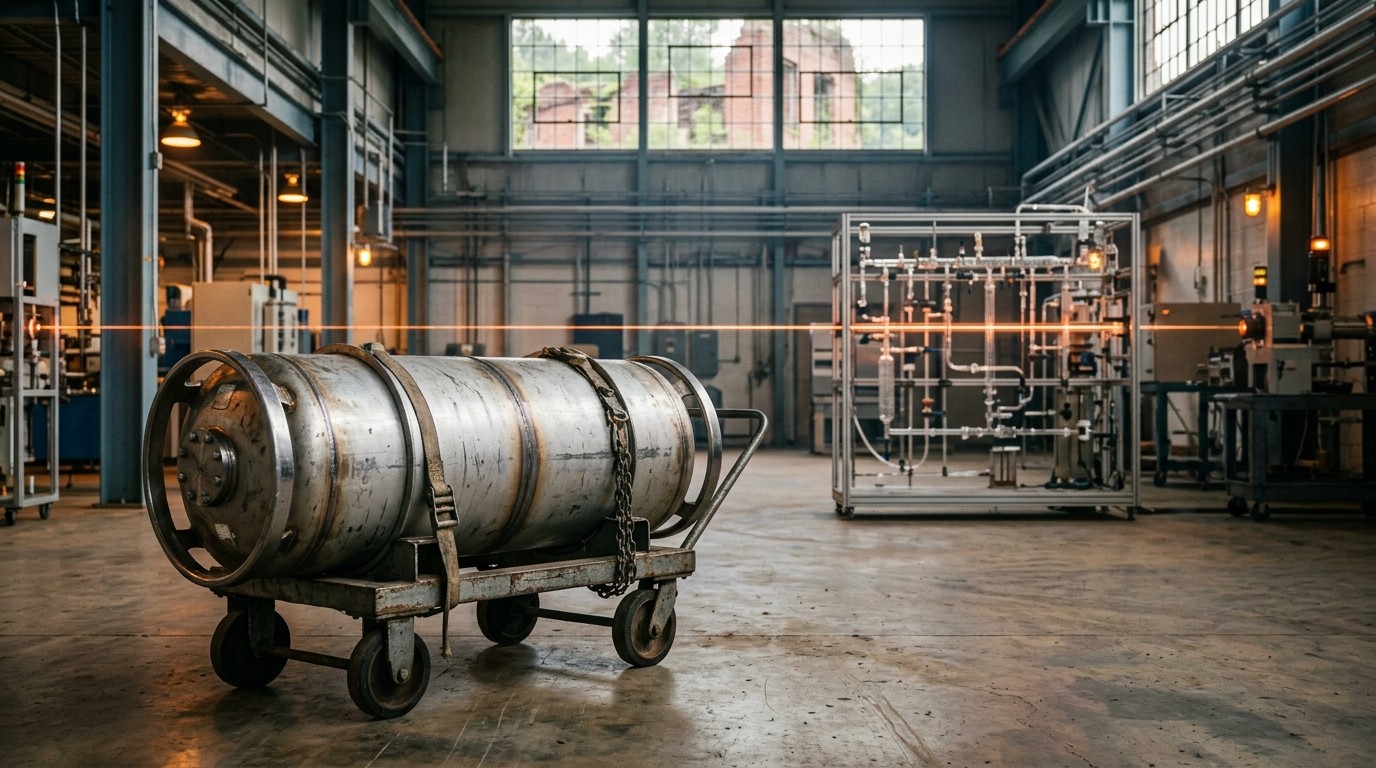

I keep coming back to a clumsy comparison a reactor developer used last spring, the one about a beautiful new car and an empty gas station. It stuck with me because it is almost too plain for an industry that loves acronyms. You can design the sleekest power module on a slide deck, raise the money, and still stall if nobody can hand you the right fuel at the right assay. Last week that same circle of companies bought a licensed place to handle the back end of the cycle. This week a cylinder showed up at the front. Uranium hexafluoride, the industry’s awkward workhorse gas, is now on site at a demonstration loop in Oak Ridge. That is a small physical fact with a large story attached.
Why a Single Cylinder Changes the Conversation
Press releases in nuclear are cheap. Licensed material on a floor is not. A privately held laser enrichment company, in which a listed microreactor developer is both shareholder and strategic partner, has accepted its first shipment of uranium hexafluoride at a demonstration test loop in Oak Ridge, Tennessee. The building sits on the footprint of the old K-25 gaseous diffusion plant, a cornerstone of the wartime effort that first taught America how to separate isotopes at scale. Uranium is back on that ground. This time it is supposed to meet a laser, not a cascade of porous barriers.
I have watched enough “first gas” announcements to stay skeptical. Still, the timing is hard to ignore. A week earlier the listed partner paid for an NRC-licensed deconversion site in New Mexico. Put the two moves next to each other and you stop seeing a reactor story with a fuel footnote. You start seeing a fuel story that happens to own reactor designs. Whether that reading survives contact with regulators, physics, and a financing market is the open question. The cylinder does not answer it. It does make the question real.
Perhaps the most interesting aspect is how ordinary the object is. A steel cylinder. A paperwork trail. A quantity small enough that the supplier had to invent a shipping procedure, because the normal trade moves much larger lots for a handful of giant customers. That detail says more about the American fuel chain than any slogan about a renaissance. The system was built for a few big plants. Everyone else has to beg a custom process just to run a test.
What Actually Arrived, and What It Is For
The shipment feeds a process the company calls CRISLA-4G, short for Chemical Reaction by Isotope Selective Laser Activation. The idea, in plain language, is selective excitement. Infrared lasers tune to a molecular vibration that one uranium isotope absorbs more readily than the other. Once those molecules are nudged into a different chemical state, they can be pulled aside. The rest of the gas stays put. If it works at useful throughput, you get enrichment without the forest of centrifuges that dominate the trade today.
Management says the feedstock lets the team start proof-of-concept runs, tune the process, qualify materials, commission the UF6 systems, and test the loop as a whole. That is a lot of verbs for one cylinder. It is also the honest sequence. Hardware on a bench is a prototype. Hardware breathing licensed uranium gas is a different animal, with corrosion, seals, accountability, and the slow discipline of nuclear materials control.
The chief operating officer noted that the gas arrived in just under a year after the State of Tennessee granted a radioactive material license on December 23, 2025. In this industry, under a year from license to first feedstock is brisk. It is not magic. It is a narrow license, a small quantity, and a team that treated logistics as part of the engineering. I have found that investors skip that part. They price the laser and forget the cylinder valve.
Over the past two years the hardware has been engineered and integrated. The feedstock is what lets the team optimize the laser process over the coming months and push the system toward a technology readiness level of 5 on the nine-step scale used by defense and energy agencies.
Company president and co-founder, paraphrased from the shipment announcement
Translation, stripped of ceremony: the machines are built, the uranium is in the building, and the next stretch is about proving the laser separates isotopes the way the patents describe. Technology readiness level 5 means a component validated in a relevant environment. It is the middle of the staircase. A commercial plant sits at the top, level 9. The company’s own fine print says realistic cost numbers wait on a later pilot. Anyone selling you a levelized cost from a test loop is selling a mood.
A Short Tour of the Laser Idea
Enrichment is the act of raising the share of uranium-235 above the 0.7 percent nature provides. Most power reactors want something near 3 to 5 percent. Many advanced designs want high-assay low-enriched uranium, often shortened to HALEU, which lives between 5 and 20 percent. Weapons sit far above that line. The commercial problem is not mystery. It is separative work, measured in SWU, and the plants that can deliver it without a foreign flag on the contract.
Centrifuges spin the gas until the lighter isotope drifts. Diffusion, the old Oak Ridge method, pushed gas through barriers until a slight bias added up across thousands of stages. Lasers try to skip the brute force. Hit the right molecule, change it, collect it. Lower power, in theory. Smaller footprint, in theory. A cost curve that bends harder than steel rotors, in theory.
Theory has a graveyard. The federal AVLIS program was shelved in 1999 after the enrichment company of that era walked away. A rival laser route, built around a different physical trick, has been in development for more than a decade and is still not a commercial plant. The molecular, lower-power approach now on the Oak Ridge floor is not the same machine. It is also not exempt from the same joke the industry tells itself: laser enrichment is always a few years away. I do not find that joke funny anymore, but I do not ignore it either.
What I will grant this team is sequence. License first. Site second. Hardware integrated. Then gas. A lot of would-be enrichers are still upstream of that sequence, arguing about flowsheets while the waiver clock on Russian material runs down. Being early to a cylinder is not the same as being early to cash flow. It is earlier than a rendering.
The Island, the Budget, and the Clock to 2030
The test loop is the appetizer. The executive chairman, who also founded the listed reactor company, tied the shipment to a commercial site on a 206-acre parcel the firm calls its island, inside the old K-25 zone. That parcel is the base for a project it brands around fuel. The numbers attached to it are not modest.
In January the company laid out a plan to invest about $1.38 billion in a commercial-scale laser plant in Oak Ridge. The land itself, a former industrial island, was bought for $8 million. A funding round of $17 million came in heavily oversubscribed, roughly 240 percent, and lifted total capital raised to about $64 million. Groundbreaking is aimed at 2026, subject to licensing and permits. Initial commercial operations are aimed at before 2030. That date sits right where several demand models expect a Western uranium and enrichment squeeze to stop being theoretical.
For pace, look backward two years. A seed round in August 2024 raised $11.88 million. The listed partner wrote a $2 million check into it. Two years later there is a state license, a site, a nine-figure plant sketch, and a first cylinder. Nuclear time usually moves like cold honey. This stretch did not. Speed is not proof. It is a change in the prior.
- Seed capital in August 2024, with a small check from the listed partner
- State radioactive material license in late December 2025
- Land assembled and a commercial budget published in the billion-dollar range
- First uranium hexafluoride accepted at the demonstration loop
- Groundbreaking targeted for 2026, first commercial output targeted before 2030
None of those bullets is a cascade of cash. Together they are a company that has left the pure-concept stage. The gap between $64 million raised and $1.38 billion required is the part spreadsheets hide if you only stare at the headline. Bridging that gap means licenses, offtake, maybe public money, and a pilot that does not embarrass the patents.
How the Two Companies Are Tied
The listed firm does not own the laser company outright. The tie is closer than a casual supply contract and looser than a subsidiary. They are related parties through common ownership and shared officers and directors. A collaboration agreement from November 2024 names the laser firm as the preferred supplier of enriched uranium hexafluoride to the reactor developer.
The economic sketch from that agreement is the line the market keeps skating past. The parties intend that enriched gas would be provided to the reactor company at no cash cost, then fabricated and sold, with the enricher paid through a profit-sharing deal still to be written. Read that twice. Free feedstock is not free. It is a claim on margin that has not been negotiated in public. If the split is generous to the private company, public shareholders own a thinner slice of the fuel rent than the narrative implies. If the split is generous to the listed firm, the private investors who funded the laser will have questions. Related-party optics are not a side issue. They are the issue, once the physics works.
Under that same agreement, the listed company’s job was to build the capabilities on either side of enrichment: deconversion and fabrication. That is the job it went and bought a piece of, days before the cylinder arrived. The sequence looks planned. It also looks like two boards with overlapping names marking their own homework. Independent directors approved the 2024 deal. Approval is a process. It is not a price.
The Other End of the Pipe
Deconversion is the unglamorous sibling of enrichment. Enriched uranium hexafluoride is a gas in a cylinder. Fuel is a solid, usually an oxide, pressed and sintered into pellets, loaded into rods. Getting from gas to solid means stripping the fluorine and handling it without creating a new waste problem. Fluorine recovery is not a slogan. It is chemistry, corrosion, and a license that takes longer than a pitch deck.
Last week the listed company paid $13.5 million for an NRC-licensed deconversion site near Hobbs, New Mexico, in Lea County. The license is described as running on a 40-year term. Thirty miles away, more or less, sits the country’s only commercial enrichment plant, a European-owned centrifuge facility at Eunice. Geography is not strategy, but it is not nothing. A deconversion pad in the same basin as the existing enricher, paired with a laser bet in Tennessee, is a map someone drew on purpose.
Fabrication sits in a HALEU-focused fuel subsidiary. Transport sits in a secured-services acquisition of about $13 million that, almost as a side effect, made the listed company revenue-generating overnight. Reactors sit in three names: a campus project whose construction permit is already in technical review with the regulator, a second design, and a space-oriented concept that is more option than near-term cash. An integrator was named in early September to help carry the commercial enrichment plant from drawing to site.
Lay the boxes in a row and the pitch becomes visible.
- Enrichment by laser, now with real gas in a Tennessee loop, and a commercial plant still on paper
- Deconversion and fluorine recovery under a long NRC license in New Mexico
- Fuel supply and fabrication through a dedicated subsidiary
- Transport through an acquired services arm
- Reactors, from a campus unit in review to later designs
A week ago the top box was a license and an empty loop. This morning it has feedstock. The New Mexico box has a license and a purchase agreement. Neither box is a factory turning cash. Both are further along than a footnote in a reactor S-1. In my experience, markets price the reactor and treat fuel as a vendor problem until the vendor problem becomes the whole multiple.
Enrichment Is the Choke, Not the Reactor Drawing
None of this matters if fuel is easy. It is not. A senior energy official put the point without poetry recently: a nuclear rebuild does not happen without fuel. The United States has one commercial enrichment plant. Waivers that still let Russian material into the system expire in January 2028. Separative-work prices sit at highs that would have looked absurd a decade ago. That is the backdrop, and it is tighter than the reactor headlines suggest.
Large new reactors make the pinch worse before small ones do. Sell-side energy strategists, looking at a roughly $120 billion package of new large units tied to a partner country, warned that those plants are likely to deepen an expected uranium supply deficit around 2030. Eight gigawatts of fresh demand, landing on a Western chain that is already short, and not one small modular unit has to switch on for the math to hurt. Add advanced reactors that want HALEU, and the enrichment problem stops being a commodity chart. It becomes a licensing and capital chart.
One bank’s supply and demand sketch, after lifting demand for small reactors and leaving mine output alone, shows uranium oxide demand crossing supply in 2026 or 2027 and not crossing back. The gap widens after 2030 as mine supply peaks and rolls over. By the mid-2040s the same sketch has demand roughly triple available supply. Models like that are not scripture. They are a way of saying the cushion is gone. Secondary supply, underfeeding at enrichers, and inventory draws have been hiding the hole. Those hides do not last forever.
| Pressure point | Where it stands | Why it matters for a laser bet |
| Commercial enrichment in the US | One operating plant, foreign-owned centrifuges | Any domestic alternative has a policy tailwind |
| Russian material waivers | Expire January 2028 | A hard date, not a vibe |
| SWU pricing | At or near record levels | High prices fund new capacity, if it can be built |
| Mine supply vs reactor demand | Models show a cross in 2026-27 | Enrichment cannot invent uranium, but it sets who captures margin |
| HALEU for advanced designs | Scarce outside limited programs | Laser and centrifuge hopefuls are all fishing the same pond |
I keep a simple rule for these tables. If every row points the same way, the trade is crowded and the disappointment will be specific. The rows do point the same way on scarcity. They do not point the same way on which technology collects the rent. Centrifuges are boring and proven. Lasers are elegant and unproven at commercial scale. Boring has a lead. Elegant has a story. Stories get multiples until the loop either separates or does not.
Washington’s Checkbook, and Who Was Left Holding a License
Scarcity is why public money is moving. In January the energy department awarded about $900 million each to three enrichment efforts, a domestic centrifuge operator, a newer centrifuge venture, and a European fuel group with US plans, plus $28 million to the longer-running laser project. The Oak Ridge laser firm, despite being one of six companies picked in December 2024 for a low-enriched uranium acquisition program, received nothing in that round.
That snub is easy to overread. Program awards follow milestones, cost share, and a committee’s taste for technology risk. A private laser loop with no uranium in it was a harder sell than a centrifuge line with a pedigree. Getting real hexafluoride into a real loop is the most direct way to change the conversation the next time the checkbook opens. It is not a guarantee of a grant. It is a removal of the easiest objection.
Policy tailwinds cut both ways. A domestic enricher that works will be treated as infrastructure. A domestic enricher that stalls will be treated as a lesson. I would not underwrite a stock on the hope of the next award cycle. I would underwrite, if at all, on whether the coming months produce separation data a skeptical engineer can respect. Awards follow data more often than decks admit.
What Can Still Go Wrong
Lasers have a history, and pretending otherwise is how people lose money with a clean conscience. The government already spent billions on one laser route and shelved it when the commercial partner quit. Another laser route has burned a decade and is still pre-commercial. A different molecular approach does not inherit those failures automatically. It does inherit the burden of proof. “Around the corner” has been said in this niche since before some of today’s analysts had a desk.
Readiness level 5 is a hallway. The phase-two pilot, a commercial license from the nuclear regulator, and the $1.38 billion financing all sit further down the hall. The laser company is pre-revenue. Pre-revenue plus a related-party supply deal plus a public stock that trades like a single-reactor call option is a mix that rewards narrative and punishes delay. Delays are the base rate in fuel-cycle construction, not the exception.
Then the governance point, which I would not bury. Common ownership and shared directors will draw scrutiny once profit-sharing terms are real. The 2024 agreement went through independent directors. Fine. The market will still want the split, the transfer price if any, and the conditions under which “no cost” feedstock survives a capital raise. If you own the listed shares, you are indirectly long a private company’s execution and directly exposed to a contract you have not seen finished. That is a position. It is not a free option.
- Physics risk: the loop may not hit target assay or throughput
- Scale risk: a demonstration is not a plant, and plants eat capital
- License risk: state material license is not a commercial enrichment license
- Funding risk: the gap from tens of millions raised to over a billion planned
- Contract risk: profit share with a related party is still unwritten
- Competition risk: centrifuge awards already have the larger public checks
None of those is a reason to sneer. They are a reason to size the bet like a technology option, not like a utility. People who need the fuel in 2028 cannot wait on a 2030 hope. People who can wait might still prefer the boring centrifuge if it is the one with offtake. The laser path wins only if cost and energy per separative unit really do break the centrifuge curve. That claim is the whole company. It has not been demonstrated in the only room that counts.
A Fair Reading of the Bull Case
The bull case does not need romance. It needs a chain. Western enrichment is concentrated. Russian supply is being written out of contracts on a dated waiver. Advanced reactors, if even a fraction of them get built, want a fuel form today’s commercial plant was not designed to flood the market with. A team that owns, or contractually sits on, enrichment, deconversion, fabrication, and transport can charge rent at more than one gate. Reactor startups that show up with a design and a PowerPoint will pay that rent or slip their schedules.
There is also a pace argument I find harder to dismiss than I expected. From an $12 million seed to a state license, a site, and gas in the loop inside two years is not how fuel-cycle projects usually behave. Some of that speed is the privilege of being small and private. Some of it is Oak Ridge, a town that already knows what a uranium cylinder looks like. Some of it may be luck with a supplier willing to write a new procedure for a small lot. Speed compounds if the next gate opens. It means nothing if the laser does not separate.
The listed stock, in this reading, is mislabeled. It trades like a single campus reactor with a long review. The filings and the purchases describe a stack: a preferred call on a private enricher, a licensed deconversion pad, a fabrication arm, a transport business that already bills, and reactor options on top. Stacks get rerated when one more box fills in. The enrichment box filled in, narrowly, this week. Rerates are not obligated to be prompt. They often arrive late, after the obvious headline, which is why the people who read the cylinder news carefully tend to be the ones already in the name.
What the Coming Months Can Actually Prove
Management has pointed at optimization results over the coming months and a push toward readiness level 5. That is a testable sentence. Either the loop produces a measurable shift in isotope ratio under conditions an outside engineer would accept, or it produces a smoother press release. I know which one I will be watching. Assay, throughput, energy per unit of separative work, materials that survive fluorine, and a materials-accounting story that does not wobble. Those are the numbers. Adjectives are optional.
A pilot plant is the step after that, and the company has said economic predictions get realistic only then. Good. Anyone quoting a future SWU price from a test loop is auditioning. The commercial license is another step, slower than state materials permission, and rightly so. Financing is the step that will sort tourists from builders. A billion-plus plant does not get built on a $17 million round, however oversubscribed.
Near-term scoreboard, not a forecast:
  Feedstock on site: done
  Loop commissioned on UF6: in progress
  Isotope shift data: the real headline
  Readiness level 5: claimed target, not a trophy yet
  Pilot plant: still ahead
  Commercial license and financing: still ahead
If you want a habit rather than a hot take, pin that list. Cross a line only when a primary document crosses it. Shipment accepted is a line. Separation demonstrated is a different line. I have been early on fuel-cycle stories before and paid for the gap between those lines in time, not always in price. Time is the expensive part if you are waiting on a reactor that needs fuel.
Oak Ridge, Memory, and the Point of Doing This Twice
There is a symbolic layer I do not want to lean on too hard, because symbolism does not separate isotopes. Still. K-25 was diffusion, vast and power-hungry, a monument to doing a hard thing with the tools of the 1940s. The buildings are mostly gone. The footprint remains, and a small team is asking a laser to do a cousin of the same job with less brute force. That rhyme is good marketing. It is also a reminder that the site has seen confident technologies before.
Diffusion worked. It was just too hungry to survive once centrifuges matured. Centrifuges work. They are capital heavy, slow to multiply, and politically concentrated. A laser that worked at scale would be a third chapter, not a rewrite of the first. The honest hope is narrower than the slogan: a domestic separator that uses less energy, fits a smaller site, and can be licensed in a country that forgot how to add enrichment capacity. Hope is not a flowsheet. The flowsheet is now allowed to meet gas.
Local knowledge matters more than the postcard. Oak Ridge still has machinists, health physicists, and a regulatory muscle memory that most American towns do not. A demonstration loop benefits from that. A billion-dollar plant will test it. Neighbors who remember diffusion will have opinions about fluorine, traffic, and jobs. Those opinions become permits. Permits become schedules. Schedules become the difference between “before 2030” and “sometime next decade.”
How This Sits Next to the Rest of the Fuel Queue
It is worth placing the laser bet in a queue, not on a pedestal. Centrifuge expansions at the existing American plant are the default supply. A revived domestic centrifuge line has the largest public award and a history, including a stall, that investors already know. A second centrifuge venture has money and a technology claim of its own. The older laser project has a smaller award and a longer scar. European capacity can serve allies and still leave the United States import-dependent. Russian capacity is being legislated toward the exit, with a waiver tail into early 2028.
Into that queue walks a private molecular-laser effort with a state license, a first cylinder, a related listed partner, and no January award. That is a challenger, not an incumbent. Challengers get the upside if the physics is kind and the capital shows up. They also get ignored by utility fuel buyers until a pilot has run long enough to put in a contract. Utilities do not buy press releases. They buy delivery windows.
Could the listed partner’s reactors be the first customer, effectively, through the profit-share sketch? Yes. That is both a feature and a circularity. A fuel chain whose anchor offtake is a reactor that is itself pre-revenue is a closed loop of hope. Outside offtake, from a utility or a fuel broker with a book, would break the circle. I have not seen that contract. Until it exists, the demand story is internal.
Pricing the Stock Like a Stack, Not a Single Reactor
Public markets are bad at stacks. They are good at one number: a reactor, a mine, a software seat. A company that buys a transport business, a deconversion license, and a preferred seat at a private enricher will be modeled as whichever piece the last headline described. Last week’s headline was the New Mexico license. This week’s is the cylinder. Next month it may be a campus review milestone. The underlying object is the same stack.
A practical way to hold it, if you hold it at all, is to separate the cash from the option. The transport arm can bill. That is cash, small, and real. The reactor review is an option on a construction permit, then an option on an operating license, then an option on a customer. The deconversion site is an option on a chemical plant that already carries a license others would spend years seeking. The laser relationship is an option on separation, struck at a profit share nobody has published. Add the options. Do not multiply them. Multiplication is how these stories get silly.
Dilution sits under all of it. A commercial enricher at the stated budget, a fabrication line, and a reactor build do not get funded by the current share count. Every box that fills in can also mean a raise. Related-party deals make those raises louder, because new investors will price the contract they cannot see. If you dislike that mess, the name is not for you. If you think fuel scarcity reprices the mess, size it like you might be early by years.
The Gas Station Line, Taken Seriously
Back to the clumsy comparison, because it earns its keep. A reactor without fuel is a parked car. A fuel chain without a reactor is a station waiting on traffic. The interesting claim this week is that one group is trying to own the station, the truck, the pump, and a few of the cars. Most peers are still in line, hoping a vendor has product when their permit arrives. Being in line is rational if the vendor is reliable. Building the line is rational if you believe the vendor will not be there.
I lean toward the second belief on enrichment, and toward caution on who collects the rent. The scarcity is not a blogger’s invention. One domestic commercial plant, a dated waiver, record separative-work prices, and demand models that break above supply before the end of this decade are a public record. The identity of the winner is not. It might be the centrifuge incumbent, expanded. It might be a funded centrifuge newcomer. It might, less probably, be a laser that finally does what lasers have promised since the 1990s. A first cylinder moves that last possibility from fiction to experiment. Experiments fail. That is why they are worth running.
A week ago the enrichment link was a license and a loop with no uranium in it. Today the loop has feedstock, and a licensed site waits at the other end of the chain. The promise of cheap, efficient separation is still a promise. The object in the building is not.
Jay Yu, wearing both hats, framed the private company’s goal as leadership in cost-effective, energy-efficient enrichment. Leadership is a result, not a press line. The result needs months of loop data, then a pilot, then a license, then money at a scale the cap table has not seen. Investors who need a catalyst this quarter should look elsewhere. Investors who think the fuel rent outlasts the reactor fundraising cycle have a cleaner setup than they did seven days ago, and a longer list of ways to be wrong.
Questions Worth Asking Before the Next Headline
A few questions cut through the noise better than another rendering of the island. What assay shift does the loop show, and at what energy cost per separative unit? Who signs the data, an internal team or an outside lab? When does the profit-share term sheet get a number, and who votes? How much of the New Mexico license is usable on day one versus a starting point for amendments? What does the transport arm actually earn, and is it related-party revenue or outside revenue? Does any utility, national lab, or fuel buyer appear as a counterparty, or is demand still internal?
I would also ask a plainer one. If the laser underperforms, does the listed company still have a business, or does the stack fold back into a reactor developer waiting in the same fuel line as everyone else? The deconversion license and the transport revenue survive a failed laser. The preferred-supplier story does not. Knowing which pieces are independent is the difference between a fuel thesis and a single point of failure with extra steps.
None of this is a recommendation to buy or sell. It is a map of what changed when a cylinder crossed a threshold in Tennessee. Maps are useful. They are not the territory, and the territory in enrichment has embarrassed confident maps before. The next honest update is not a groundbreaking photo. It is a separation result. Until that result exists, the gas station has gas in the back room, and the pump is still being tested.
If the result lands cleanly, the conversation shifts from “can they get uranium on site” to “can they get uranium apart,” which is the only conversation that was ever going to matter. If it lands messy, the New Mexico license and the transport invoices will still be there, and the laser chapter will join a long shelf. Either outcome is information. This week merely made the experiment possible. That is rarer, in this niche, than another promise that the corner is close.



