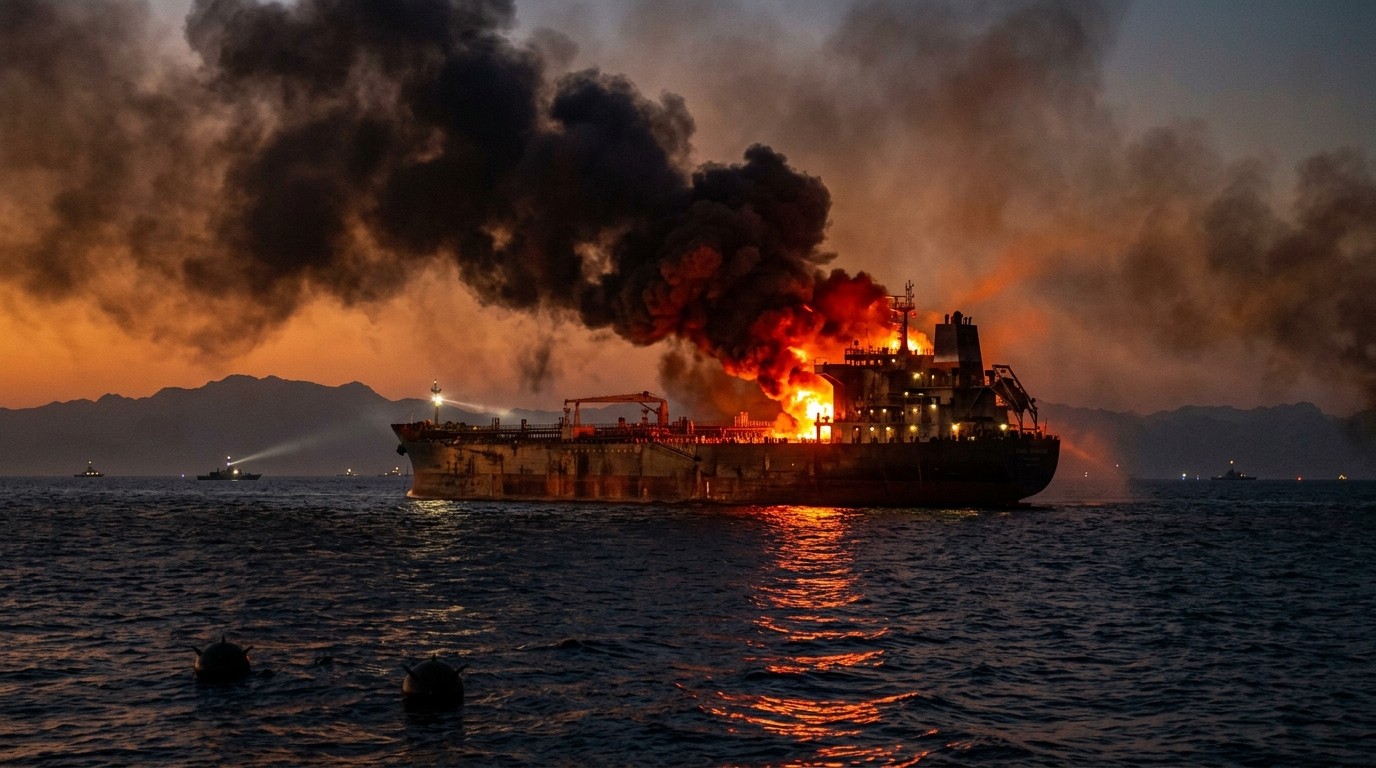

Late last night the reports started filtering in again, and this time they felt heavier than usual. Heavy explosions in the southern stretch of the Strait of Hormuz, Iranian sources claiming oil tankers had struck mines, and within hours markets were already reacting. I’ve been watching these waters for years, and the pattern feels familiar yet somehow more deliberate now. When the U.S. president publicly rules out military action until after November, it creates a window, and Tehran appears ready to test how wide that window really is.
A Night Of Explosions And A Sudden Oil Drop
According to Iranian state channels, several vessels hit mines in the southern passage during the late evening hours Tehran time. The language was careful: “violating oil tankers” striking devices already laid in the area. Whether every claim holds up under independent scrutiny remains an open question. In the past some similar announcements proved overstated. Still, the timing is hard to ignore.
Just hours earlier, a clear statement had gone out: no attacks on Iran before the midterm elections. Oil prices, which had been climbing on the back of earlier tanker incidents, reversed course almost immediately. The drop was sharp enough to catch many traders off guard, even if prices remained higher on the day overall. Markets hate uncertainty, but they also hate the sudden removal of a potential catalyst.
In my view, that public pledge did more than calm some nerves. It signaled a temporary ceiling on escalation, and adversaries tend to notice ceilings. Within the same news cycle, Iranian officials were already talking about continued proposals exchanged through intermediaries. One side says the door is still open. The other side keeps laying more hardware in the water. The contrast is striking.
Attacks Moving Beyond The Narrow Strait
What stands out this week is the geographic shift. For months most incidents stayed concentrated inside the familiar choke point. Now reports describe strikes farther afield. One vessel was hit roughly fifty nautical miles north of Qatar’s tip, deep inside the Persian Gulf. Multiple projectiles. Casualties reported. The location itself matters. It sits hundreds of kilometers west of the traditional transit corridor.
A second incident near the UAE coast remains less confirmed, yet satellite and maritime channels picked up a fire roughly thirty nautical miles east of Fujairah. If verified, it would mark a clear expansion of the operational area. Ships that once felt relatively safe once they cleared the strait itself now face risk across a much broader stretch of water.
This looks like a deliberate message. When record volumes of traffic continue under naval escort and transit protocols, the response is to widen the threat zone rather than simply intensify pressure inside the narrowest point. Any vessel suspected of trying to slip past designated corridors becomes a potential target. The practical effect is higher insurance costs, longer routing decisions, and more nervous crews.
When the danger zone expands beyond the traditional choke point, every captain and every charterer has to recalculate the entire voyage.
I’ve spoken with people who follow these routes daily. The change in tone is noticeable. What used to be a high-risk transit through a defined corridor is turning into a broader regional hazard. That shift carries real commercial weight.
The Midterm Calculus And Military Options
Behind the public statements sits a quieter planning process. Options for limited strikes have been prepared. Timelines discussed. The possibility of action before the November vote has been on the table. At the same time, the political cost of renewed large-scale operations is obvious. Oil prices tend to spike on major escalation headlines, and higher fuel costs rarely help at the ballot box.
The current pause in direct strikes has lasted several weeks. That stretch of relative quiet coincides with the final stretch of campaign season. Many assumed the quiet would hold through election day. The preparation of options suggests the assumption may not be ironclad. Yet the public declaration of no attacks before the midterms changes the immediate risk calculation for everyone watching the region.
Iranian officials, for their part, continue to insist negotiations have never fully closed. Proposals move through mediators. Amendments are offered. Trust remains low on both sides. One recent assessment suggested Iranian leadership remains deeply suspicious of any sudden shift in tone, remembering previous surprises. That suspicion itself becomes a factor in how aggressively maritime pressure continues.
Wider Regional Flashpoints Adding Pressure
While attention stays fixed on tankers, other developments keep the overall temperature elevated. In Saudi Arabia, a ballistic missile strike on Riyadh’s main international airport was claimed by Iran-aligned forces in Yemen. Footage later circulated showing damage to a stationary aircraft. Separate reports spoke of fires and smoke near major energy facilities further east. Each incident feeds the same broader sense of instability.
Traffic through the strait itself has not stopped. Commercial volumes, including large crude cargoes, continue to move under naval oversight. Official statements reject any claim that the waterway is closed or fully controlled by one side. The practical reality on the water is more complicated. Ships still sail, yet every voyage now carries extra layers of risk assessment, routing adjustments, and insurance premiums.
Perhaps the most interesting aspect is how the two tracks run in parallel. On one track, diplomatic channels remain open enough for proposals to circulate. On the other, the operational tempo of maritime incidents keeps rising. The combination creates a strange kind of managed tension rather than outright rupture.
What The Oil Market Is Really Pricing
Oil reacted first and fastest to the no-strike pledge. That reaction tells you something important. Traders had been building in a higher probability of near-term military action. Removing that probability, even temporarily, took some of the risk premium out of the price. Yet the underlying physical risk to shipping has not disappeared. If anything, the expansion of attack zones increases the chance of a major disruption that would force prices higher again.
Look at the recent weekly tally. Multiple attacks on oil, gas, and product tankers around the strait in a single seven-day period. Crew injuries reported on more than one vessel. These are no longer isolated events. They form a pattern that insurers and charterers cannot ignore. Higher costs eventually feed into the delivered price of energy, even if the headline crude number softens for a day or two.
- Insurance premiums for Gulf transit have already climbed
- Some operators add armed security or alter routes
- Voyage times lengthen when ships take wider arcs
- Crews face elevated psychological pressure
- Any single successful hit on a very large crude carrier could change the tone overnight
In my experience, markets can shrug off gradual increases in friction for longer than most people expect. What they cannot shrug off is a sudden loss of a key loading or transit point. The current strategy of spreading risk across a wider area raises the odds of exactly that kind of sudden loss.
Negotiations That Never Quite Die
Despite the kinetic activity, both sides keep the diplomatic language alive. Iranian leadership has stated that proposals continue to move through intermediaries and that the negotiating table has never been fully abandoned. On the American side, mixed signals appear. One day the preference seems to lean toward pressure rather than a comprehensive deal. The next day reports surface of active work toward some form of understanding.
This ambiguity itself becomes a strategic tool. As long as the possibility of talks remains, the justification for extreme measures stays incomplete. At the same time, the absence of a clear settlement keeps the pressure campaign legitimate in the eyes of those conducting it. The result is a prolonged period of neither war nor peace, a gray zone that is particularly hard on commercial shipping and energy markets.
I keep coming back to the human element. Tanker crews are not abstract numbers. When reports mention casualties, real people are involved. Families wait for news. Companies face difficult decisions about whether to keep sailing certain routes. The strategic chessboard looks different when you remember the people actually on the water.
Possible Paths From Here
Several scenarios now sit on the table. One is continued low-level maritime pressure through the midterms, with both sides avoiding steps that would force an immediate large response. Another is a sudden incident that crosses an unspoken red line and triggers the prepared strike options after all. A third is a quiet diplomatic breakthrough that reduces the operational tempo without a formal public agreement.
None of these paths is clean. The first risks gradual normalization of higher shipping costs and intermittent supply fears. The second risks a sharp oil spike and political backlash. The third requires a level of mutual confidence that currently looks scarce. Watching which path materializes will tell us a great deal about how both capitals calculate risk in the coming weeks.
For energy markets the immediate question is simpler. How much additional risk premium belongs in the price while the midterm clock runs down? The answer will keep shifting with every new explosion report and every new public statement. Traders who treat the situation as static will likely find themselves surprised.
Practical Implications For Shipping And Energy
Ship owners and charterers already adjust. Some add extra security teams. Others prefer to wait for clearer windows of lower activity. Port calls near the expanded risk zones require fresh assessments. Refineries that depend on Gulf barrels watch inventory levels more closely. Even countries far from the region feel secondary effects through freight rates and insurance markets.
The longer this pattern continues, the more structural the changes become. Once companies rework contracts and routing assumptions, those changes do not reverse overnight even if the immediate threat level drops. That is one reason periods of elevated tension leave lasting marks on energy logistics.
| Factor | Current Effect | Potential Next Step |
| Transit Risk | Elevated across wider Gulf | Further route diversification |
| Insurance | Premiums rising | Additional war-risk surcharges |
| Oil Price | Volatile, sensitive to headlines | Sharp move on major incident |
| Diplomatic Track | Still active via mediators | Possible limited understanding |
Looking at the table above, none of the cells feel comfortable. Each carries forward momentum that could intensify or ease depending on decisions made in the next few weeks.
A Personal Observation On Timing
I’ve found that the most dangerous moments in these standoffs often arrive when one side believes the other is constrained by domestic politics. The midterm calendar is public. The desire to avoid a fuel-price spike is understandable. Yet that very visibility can invite testing. Whether the current expansion of maritime activity is such a test remains to be proven, but the coincidence of timing is difficult to dismiss.
At the same time, restraint can itself become a strategy. Keeping options prepared while declining to use them immediately preserves flexibility. It also leaves room for the other side to recalibrate. The coming days will show whether that room is used or ignored.
Energy markets, shipping companies, and regional governments all share one common need right now: clearer signals about how long the present gray zone will last. Until those signals arrive, volatility remains the safest assumption.
Why This Matters Beyond The Headlines
Every barrel that faces higher transit risk eventually shows up in the price paid by consumers far from the Gulf. Every delayed voyage tightens available supply somewhere downstream. The connection is not always immediate or linear, yet over time it becomes measurable. That is why a series of mine strikes and projectile attacks in distant waters still belongs on the front page of market analysis.
The situation also tests the effectiveness of naval presence and transit protocols. When traffic continues at high volume despite the incidents, it demonstrates a degree of resilience. When the attack zone expands in response, it shows that resilience alone may not be enough to restore normal commercial conditions.
In the end, the story is less about any single explosion and more about the cumulative effect of sustained pressure. One night of heavy blasts can be absorbed. A pattern that stretches across weeks and across a wider map becomes harder to ignore. Markets are already adjusting. The question is how far those adjustments will need to go before the underlying tension finds a new equilibrium.
For now the public commitment to delay any major military step until after the midterms has taken one immediate risk off the table. It has not removed the mines already in the water, nor the willingness to place more of them. That gap between political calendar and operational reality is where the next chapter of this story will be written.
Watch the shipping reports. Watch the price action. And watch whether the diplomatic channel produces anything more concrete than another round of carefully worded statements. The combination of those three indicators will tell us more than any single dramatic headline.
The southern Strait of Hormuz remains one of the most sensitive pieces of water on the planet. When explosions echo across it at night, and when those explosions start occurring farther from the traditional choke point, the rest of the energy world has no choice but to pay attention. The coming weeks will decide whether this period of expanded maritime pressure settles into a new normal or tips into something more consequential. Either outcome will leave its mark on oil prices, shipping economics, and the broader sense of security across the Gulf.