
Have you ever stopped to wonder just how far countries will go when their energy future feels uncertain? I found myself asking that after learning China has been sending drills thousands of meters underground, chasing oil and gas that most of us never even knew existed. The numbers are striking. State-owned operators have already pulled more than 26 million tons of oil equivalents from reservoirs sitting at least 6,000 meters below the surface in one western oilfield alone. That depth is no joke. It sits far beyond ordinary drilling, and the technical hurdles stack up fast. Yet the push continues, and it reveals a lot about how one of the world’s largest energy consumers is rewriting its own supply story.
Why Ultra-Deep Drilling Matters Right Now
Global markets keep tossing curveballs. Prices swing, supply routes face questions, and long-term contracts no longer feel as solid as they once did. In that environment, China has decided that relying so heavily on imported crude carries too much risk. The country remains the top crude oil importer on the planet, but that status is exactly what leaders want to soften. Ultra-deep formations and challenging shale plays have become central to the plan. These reservoirs demand serious money and advanced technology, yet the payoff could reshape domestic production for years.
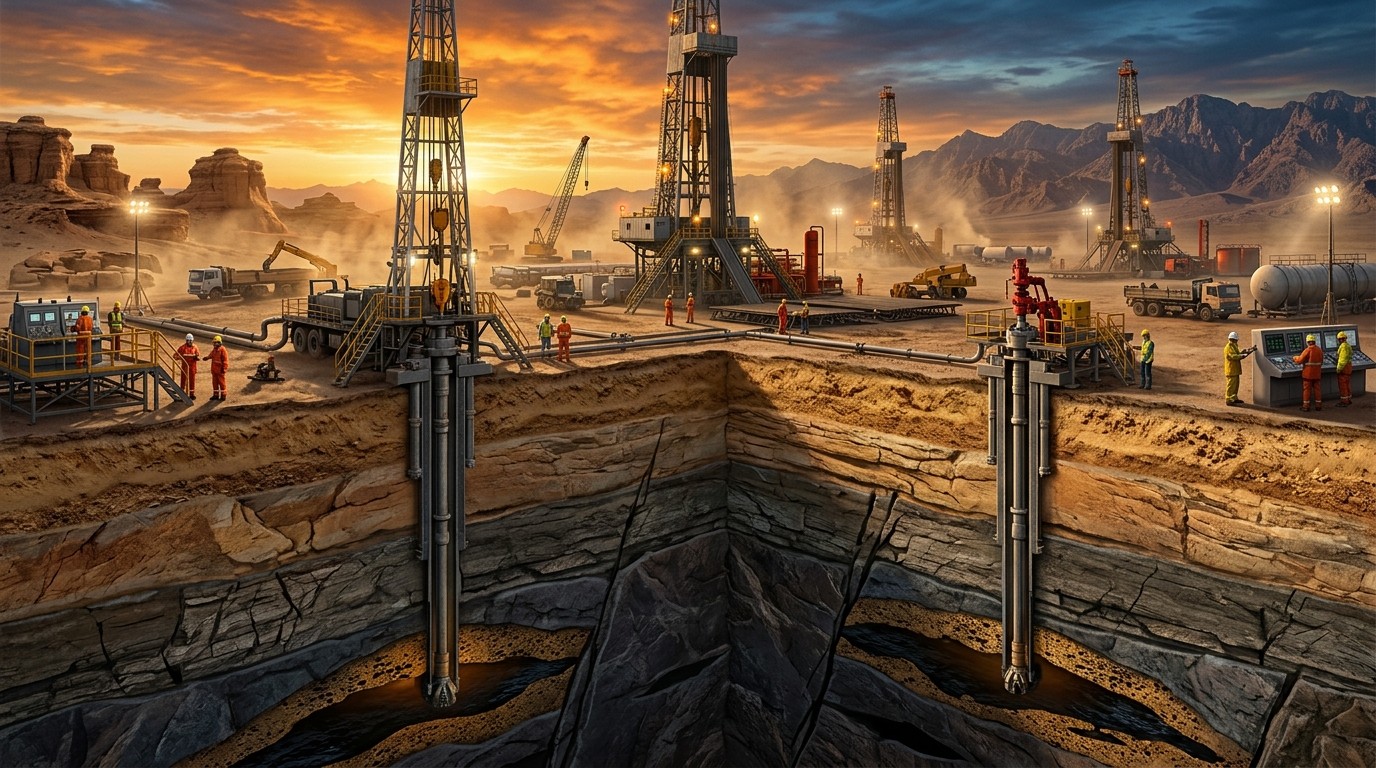
I’ve watched energy strategies evolve for a while, and this one stands out because of its sheer scale and persistence. Operators are not dabbling. They are committing to projects that would make many international companies pause. The Hade-Fuman oilfield in Xinjiang offers a clear example. It has grown into China’s largest desert oilfield and now serves as a dedicated base for ultra-deep exploration. Hundreds of wells already puncture those extreme depths. The result is steady output that feeds straight into the national supply chain.
The Scale of Production at Extreme Depths
More than 26 million tons of oil equivalents have come from those 6,000-meter-plus reservoirs. That figure alone deserves a second look. Reaching such depths means dealing with intense pressure, high temperatures, and complex geology. Equipment must hold up under conditions that ordinary wells never face. Costs climb quickly, yet the volume extracted shows the effort is delivering. PetroChina, the main player there, has drilled 485 ultra-deep wells across the field. Each one represents years of planning, specialized crews, and continuous technological upgrades.
In my view, the real story sits in the consistency. These are not one-off discoveries. The field keeps expanding its role as a production hub while also acting as a testing ground for methods that can be applied elsewhere. Desert conditions add another layer of difficulty. Sand, remote logistics, and harsh weather all complicate operations. Still, the wells keep coming online. That kind of determination signals how seriously the self-reliance goal is taken.
Shale Gas Breakthroughs in Sichuan
Oil is only part of the picture. Natural gas from ultra-deep shale is gaining equal attention. Sinopec recently secured official approval for proven geological reserves totaling 235.687 billion cubic meters at the Ziyang Dongfeng field in Sichuan province. That certification marks the creation of China’s first ultra-deep shale gas field at the 100-billion-cubic-meter level. The number is impressive on its own, but the context makes it more significant. Shale plays in China often sit deeper and in more complex terrain than many North American counterparts. Success here required patient exploration and repeated validation of reserve estimates.
Perhaps the most interesting aspect is how these efforts fit into a broader pattern. For several years now, Chinese operators have steadily certified growing volumes of shale oil and gas despite the geological headaches. Formations that once looked too difficult are gradually moving into the commercial column. The government approval process itself carries weight. Once reserves receive official validation, development plans can move forward with greater certainty and funding support.
Unlocking resources at these extreme depths requires both advanced technology and long-term commitment that few operators can match.
I keep coming back to the strategic angle. China already maintains a diversified supplier base for both oil and gas. Imports arrive from many regions. Yet the priority remains clear: raise the share of domestic production so that external shocks land with less force. Ultra-deep drilling and shale development form two pillars of that approach. Alternative energy sources continue expanding at the same time, but hydrocarbons still dominate the energy mix for the foreseeable future. Reducing exposure on that front carries practical value.
Technical and Economic Challenges of Going Deeper
Drilling past 6,000 meters is expensive. Equipment must withstand extreme pressure and temperature. Drill bits wear out faster. Well designs grow more sophisticated. Data interpretation becomes trickier because seismic signals lose clarity at those depths. All of this adds cost and time. Operators accept those realities because the alternative is continued heavy dependence on foreign crude. The trade-off looks different when energy security ranks high on the national agenda.
Logistics in remote desert locations compound the difficulty. Moving heavy machinery, housing crews, and maintaining continuous operations far from major cities requires careful planning. Yet the Hade-Fuman field has overcome those barriers enough to become a flagship project. Similar determination shows up in the Sichuan shale work. Mountainous terrain and complex underground structures have not stopped the certification of large reserve volumes. Progress may feel gradual, but the cumulative effect is becoming hard to ignore.
- Extreme pressure and temperature demand specialized materials and designs
- Remote desert and mountainous sites raise logistical costs
- Geological complexity requires advanced seismic and modeling tools
- Long lead times from exploration to first production test patience and budgets
Still, the production numbers keep rising. That fact alone suggests the technical solutions are improving and the economic case is holding up under current conditions. I’ve found that energy projects of this scale often look unviable at the start and gradually become more attractive as experience accumulates. China appears to be following that path with deliberate steps.
Broader Push for Energy Self-Reliance
The ultra-deep campaign sits inside a larger strategy. Domestic oil and gas output has received sustained attention for years. Exploration budgets stay robust. New technologies receive rapid testing. Policy support encourages operators to tackle difficult plays rather than stick only to easier conventional fields. The goal is not complete independence. That remains unrealistic for a country of this size and industrial intensity. The aim is a meaningfully higher degree of self-reliance so that import disruptions cause less economic stress.
Shale oil and gas form another important piece. Chinese basins present tougher geology than some international peers. Reservoirs tend to sit deeper. Sweet spots can be harder to identify. Yet steady progress continues. Reserve certifications keep arriving. Pilot production programs expand. Each success builds confidence and technical knowledge that can transfer to the next project. In my experience watching these developments, momentum matters. Once a few large fields prove commercial, capital and talent tend to follow more readily.
Global market turmoil adds urgency. Price volatility, geopolitical friction, and shifting trade patterns all reinforce the logic of producing more at home. Even with a wide range of suppliers, the sheer volume of imports creates exposure. Any sustained rise in domestic output eases that pressure. The 26 million tons already recovered from ultra-deep reservoirs and the newly certified shale gas volumes contribute directly to that buffer.
How Technology Enables Extreme Depth Operations
Modern drilling systems have improved dramatically. High-strength tubulars, advanced mud systems, and real-time monitoring allow operators to push deeper with better control. Measurement-while-drilling tools provide data that once required costly delays. Directional drilling techniques help reach targets more precisely even under difficult conditions. These advances reduce some of the traditional risks associated with ultra-deep wells, though they never eliminate them entirely.
Data analytics also play a growing role. Interpreting seismic information from extreme depths remains challenging, but machine learning models and improved processing techniques help identify potential reservoirs with greater confidence. Once drilling begins, continuous sensor feeds allow engineers to adjust parameters on the fly. The combination of better hardware and smarter software shortens learning curves and improves success rates over time.
I sometimes think the quiet story here is the accumulation of know-how. Each successful ultra-deep well teaches lessons that make the next one slightly easier or less expensive. Over hundreds of wells, that knowledge compounds. The Hade-Fuman field illustrates the point. What started as ambitious exploration has matured into a production base that also serves as a technology proving ground. Other basins can draw on that experience.
Implications for Global Energy Markets
Any meaningful rise in Chinese domestic output eventually shows up in import demand. The effect may not appear overnight, but the direction is clear. Lower import growth, or even absolute declines in certain years, would ripple through seaborne crude markets and pipeline suppliers. Producers that currently count on Chinese demand growth would need to adjust expectations. At the same time, successful ultra-deep and shale development could free capital and attention for other strategic priorities inside China itself.
Price impacts remain harder to predict. Global balances depend on many factors beyond one country’s production trends. Still, a sustained increase in Chinese output adds supply that would otherwise have to come from elsewhere. In tight markets that extra volume can matter. In oversupplied periods it may simply add to existing pressure. Either way, the structural shift toward greater self-reliance alters the long-term outlook for trade flows.
Investors watching the energy sector should pay attention to the technology angle as well. Companies that supply specialized drilling equipment, high-performance materials, or advanced subsurface imaging tools stand to benefit from continued activity at these extreme depths. The projects underway already demonstrate demand for solutions that go beyond standard industry practice.
| Project Area | Key Achievement | Resource Type |
| Hade-Fuman, Xinjiang | Over 26 million tons oil equivalent recovered | Ultra-deep oil |
| Hade-Fuman Wells | 485 ultra-deep wells drilled | Oil and gas |
| Ziyang Dongfeng, Sichuan | 235.687 billion cubic meters proven reserves | Ultra-deep shale gas |
Looking Ahead at the Next Phase
The current results look solid, yet the work is far from finished. More wells will be drilled. Additional shale zones will undergo evaluation. Technology will continue to evolve. The combination of policy support, operator commitment, and accumulating experience creates a foundation for further gains. Whether the pace accelerates or settles into steady progress remains an open question, but the direction feels established.
One aspect that often gets overlooked is the human element. Crews operating in remote deserts or complex mountain terrain face demanding conditions. Maintaining safety and operational discipline under those circumstances requires strong systems and experienced leadership. The fact that production continues to rise suggests those systems are functioning. Still, every new ultra-deep campaign tests them again.
I’ve found that energy transitions rarely follow neat timelines. Conventional wisdom sometimes underestimates how quickly difficult resources can become viable once the right incentives and technologies align. China’s ultra-deep and shale efforts may prove another example. The volumes already achieved and the reserves newly certified provide concrete evidence that the strategy is delivering results. Further progress will depend on continued investment and the ability to manage costs as projects scale.
Market observers will watch import statistics closely in the coming years. Any sustained moderation in crude purchases would signal that domestic gains are beginning to register at the national level. Gas production trends will matter equally, especially as demand for cleaner-burning fuels remains strong. The interplay between rising domestic output and evolving import patterns will shape regional energy dynamics for a long time.
Balancing Hydrocarbons and Broader Energy Goals
China continues expanding renewable capacity at an impressive rate. Solar, wind, and other alternatives receive substantial support. That growth does not eliminate the need for oil and gas in the near to medium term. Transportation, petrochemicals, and industrial processes still rely heavily on hydrocarbons. Raising domestic production therefore complements rather than contradicts the longer-term energy transition. It provides a more secure bridge while alternative sources scale further.
The dual approach carries practical advantages. Greater hydrocarbon self-reliance reduces vulnerability during the transition period. At the same time, experience gained in complex drilling and reservoir management can transfer to other subsurface activities, including geothermal or carbon storage projects down the road. The skills developed today may serve multiple purposes later.
In the end, the ultra-deep drilling campaign reflects a calculated response to real constraints. Import dependence creates exposure. Difficult domestic resources offer a partial solution if the technical and economic challenges can be managed. Early results from Xinjiang and Sichuan suggest the challenges are being met with enough success to justify continued effort. How far that success extends will influence energy balances well beyond China’s borders.
The story remains unfinished. New wells will bring fresh data. Reserve estimates will be updated. Production profiles will evolve. For anyone following global energy markets, these developments deserve close attention. They illustrate how determined resource development at extreme depths can alter long-standing supply patterns, one carefully engineered well at a time.
What stands out most to me is the quiet persistence. Rather than chasing only easy barrels, operators are tackling formations that demand patience and advanced capability. That choice carries costs, yet it also builds a deeper foundation of domestic supply that may prove valuable in more ways than one. As the numbers continue to accumulate, the strategic logic becomes harder to dismiss. Ultra-deep oil and gas are no longer experimental concepts in China. They are becoming part of the practical energy landscape.