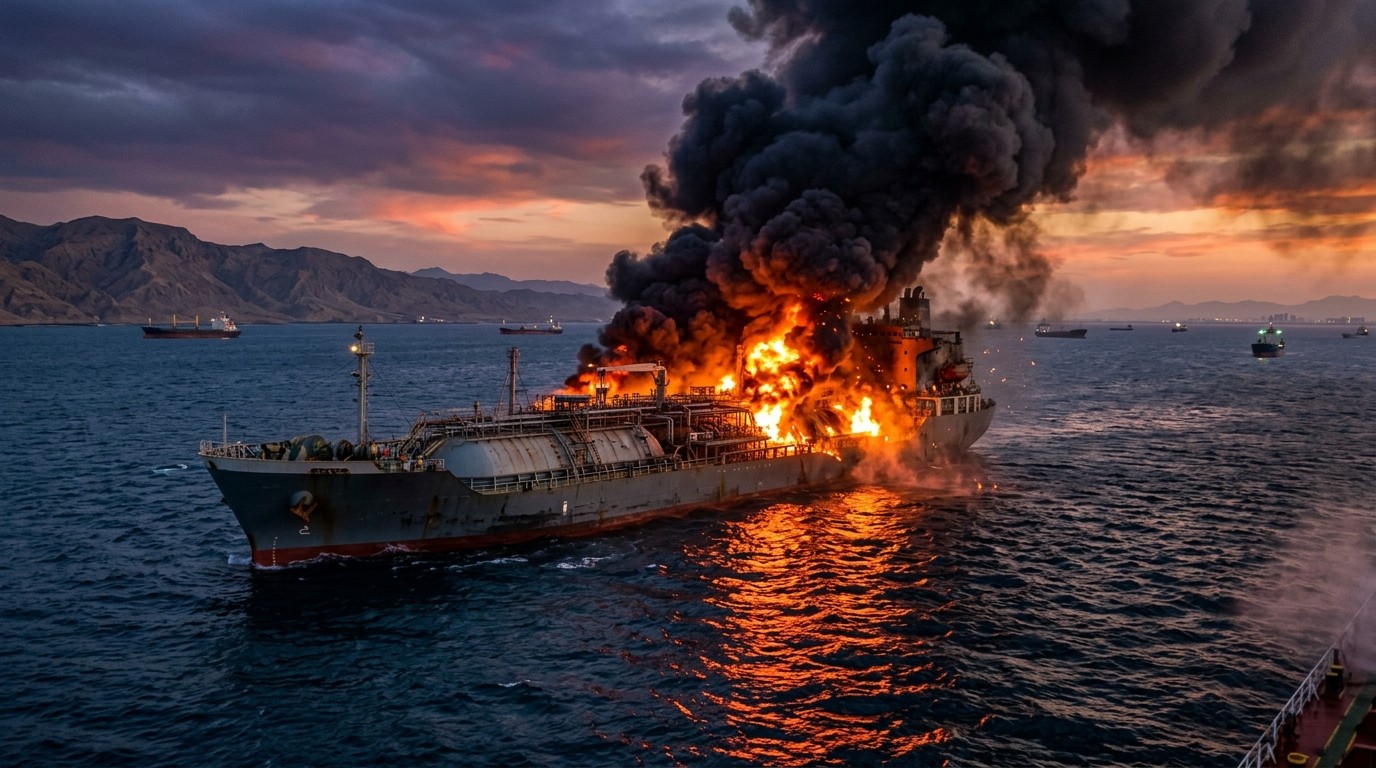

Have you ever watched oil prices twitch on a Friday afternoon and felt that familiar knot in your stomach? I had that exact feeling when the latest reports started circulating about an LPG tanker catching fire in the Strait of Hormuz. It was not just another headline. It felt like the opening scene of a much larger story that could reshape energy markets for months.
Escalating Risks Along Critical Energy Corridors
The Strait of Hormuz has always been a pressure point. Roughly a fifth of the world’s oil passes through that narrow waterway every single day. When something goes wrong there, the effects ripple far beyond the Middle East. This time the reports came in layers. First came claims that Iranian forces had struck a liquefied petroleum gas tanker. Then came separate accounts of dense mining activity in the Bab al-Mandab strait farther south. Put those two together and you suddenly have two of the most important shipping chokepoints under simultaneous stress.
I find myself returning to the same question: how much disruption can global markets absorb before the pain becomes structural rather than temporary? The answer is never simple, yet the events of the past few days force us to look harder at the details.
Reports of Mining Activity in Bab al-Mandab
Saudi-linked media described what they called a “worst fear” scenario. Engineering teams were said to be working to clear mines and improvised explosive devices from the Bab al-Mandab area. The language was careful, yet the implication was clear. Dense mining, if confirmed on a wide scale, would raise insurance costs, slow transit times, and force some operators to reconsider routes altogether.
It is worth pausing here. The Houthis have previously stated that the strait remains open for normal commercial traffic while targeting vessels they consider linked to specific countries. Localized mining near the coast during active fighting is not the same as a full closure. Still, even limited mining creates uncertainty. Ship captains hate uncertainty. So do traders watching freight rates.
In my own reading of past Red Sea incidents, the psychological effect often outlasts the physical one. Once the word “mines” enters the conversation, risk premiums climb and stay elevated longer than the actual threat. That pattern may repeat here.
The Iranian Claim of a Direct Strike
Hours after the mining reports, Iranian state media carried a statement from the Islamic Revolutionary Guard Corps. They said they had targeted an LPG tanker attempting to pass through the Strait of Hormuz “illegally.” The vessel suffered a major fire. The same statement added that any vessels committing violations outside the strait would face punishment going forward.
That second part matters. It expands the stated area of enforcement. Until now most attention stayed inside the strait itself. Broadening the warning raises the stakes for every ship operating in the wider Gulf region.
I keep thinking about the timing. Oil flows through Hormuz have been described by some officials as reaching record wartime levels. When one side claims success in keeping the waterway open while the other side demonstrates it can still hit a vessel, the contradiction itself becomes a market factor.
A Separate Incident Near the UAE Coast
Almost in parallel, maritime authorities reported another vessel struck by an unknown projectile roughly thirteen nautical miles west of Al Jazeera in the United Arab Emirates. A fire broke out and was later extinguished. The pattern of smaller, harder-to-attribute incidents has become familiar this week. Each one adds another data point without necessarily clarifying the larger picture.
These lower-profile events often get less attention than a dramatic claim of a major strike, yet they contribute to the overall sense that the region is becoming less predictable. Predictability is the quiet foundation of efficient shipping. When it erodes, costs rise for everyone downstream.
Immediate Market Reaction and Price Moves
Oil prices moved higher as the reports spread. Futures, however, showed a more cautious tone later in the session. That split reaction is telling. Spot markets respond to the fear of immediate disruption. Futures markets try to price the probability that the disruption will last.
I have watched this dynamic play out before. A sharp spike followed by a partial fade often signals that traders are still weighing political signals against pure supply risk. One of those political signals arrived quickly.
Political Signals and Timing Considerations
A clear statement from the U.S. side indicated no military action against Iran before the November midterms. That message landed like a temporary lid on rising prices. Markets hate open-ended escalation almost as much as they hate physical shortages. A firm timeline, even if only until an election, gives traders something concrete to price around.
At the same time, talk of ongoing diplomatic conversations continues. One side describes those talks as productive. The other side describes them as stalled. The gap between those two descriptions is itself a source of volatility. When official narratives diverge this sharply, markets tend to lean toward the more cautious interpretation until clearer evidence appears.
Perhaps the most interesting aspect is how political calendars now intersect with energy security. I cannot remember a period when the midterm election schedule played such an explicit role in statements about potential military options. That intersection deserves more attention than it usually receives.
Why Two Chokepoints Matter More Than One
Most analysis focuses on Hormuz alone. Adding Bab al-Mandab into the same week changes the calculation. These two waterways sit on opposite ends of the Arabian Peninsula. Disruptions in both would force a larger share of global energy trade onto longer, more expensive routes around the Cape of Good Hope or through other constrained passages.
The practical effects show up in several places at once:
- Higher war-risk insurance premiums for vessels still willing to transit
- Longer voyage times that reduce effective fleet capacity
- Increased demand for alternative loading points farther from the Gulf
- Greater sensitivity of refining margins in Europe and Asia to any further escalation
None of these effects appear overnight. They accumulate. That accumulation is what turns a series of incidents into a lasting shift in cost structures.
Historical Patterns and What They Suggest
Looking back at previous periods of tension in the same region, the market rarely prices a permanent closure. What it does price is a higher baseline level of risk. Freight rates stay elevated. Inventory buffers grow. Strategic petroleum reserves become more politically sensitive. Those adjustments can persist long after the immediate crisis fades from headlines.
I have found that the most durable market effects often come from the quiet operational changes rather than the dramatic strikes themselves. Shipping companies rewrite their risk models. Energy traders adjust their seasonal assumptions. Refiners rethink crude slate flexibility. Those behind-the-scenes shifts outlast any single fire on a tanker.
The Role of Attribution and Ambiguity
One recurring feature of recent incidents is incomplete attribution. An “unknown projectile” near the UAE coast is harder to respond to than a claimed IRGC strike. Ambiguity slows diplomatic responses and complicates insurance assessments. It also keeps the threat of further incidents alive in traders’ minds.
In my experience watching these situations, ambiguity itself becomes a form of leverage. As long as no party claims full responsibility or offers a clear path to de-escalation, the risk premium remains. That dynamic may prove more important than any single confirmed hit.
Implications for Energy Security Planning
Governments and companies have spent years talking about supply diversification. Events like these test how far that talk has translated into actual capability. Alternative pipelines, expanded storage, and more flexible refining capacity all become more valuable when chokepoints look less reliable.
At the same time, the sheer volume of oil that still moves through Hormuz means no amount of diversification can eliminate the risk overnight. The waterway remains indispensable. That reality keeps every incident relevant far beyond the region itself.
Consider the downstream effects on petrochemical feedstocks. LPG is not only a fuel. It is a building block for plastics and other materials. A sustained disruption to LPG flows would eventually show up in manufacturing costs well outside the energy sector. Those second-order effects rarely make the first-day headlines, yet they matter for longer-term economic planning.
How Traders Are Likely Adjusting Positions
In the short term, the classic response is a flight into prompt crude and a rise in volatility products. Longer-dated contracts often show more restraint until the political path becomes clearer. The midterm election calendar now sits inside that calculation. Any statement that narrows the window for military action tends to compress the risk premium, at least temporarily.
I keep an eye on the shape of the futures curve. A steepening contango can signal that the market expects near-term tightness followed by eventual relief. A flattening or inversion would suggest deeper concern about lasting supply loss. So far the reaction has stayed closer to the first pattern, but that can change quickly if further incidents occur.
The Human Factor Behind the Headlines
It is easy to discuss tankers and chokepoints in abstract terms. Behind every voyage are crews who must decide whether the extra risk premium is worth the journey. Port agents, charterers, and insurers all make parallel calculations. Those individual decisions aggregate into the larger market moves we see on screens.
When I speak with people who work in shipping, the consistent theme is fatigue with repeated tension. Each new incident adds to a cumulative sense that the region is becoming harder to operate in. That fatigue itself can influence routing decisions even when the physical threat remains limited.
Looking Ahead: Scenarios Worth Watching
Several paths remain open. One is a rapid de-escalation driven by quiet diplomacy and a mutual desire to avoid broader economic damage. Another is a series of limited, deniable incidents that keep risk premiums elevated without triggering a full military response. A third, less likely but more damaging, would involve confirmed widespread mining that forces a material reduction in transit volumes.
Markets will continue to price the probability of each path. The political calendar until November adds an extra constraint on the more aggressive options. That constraint is temporary by definition. Once the election passes, the calculation can shift again.
In the meantime, the combination of a claimed Iranian strike, reports of mining farther south, and a separate projectile incident near the UAE coast has already succeeded in one respect: it has reminded every market participant that energy security remains tightly linked to regional stability. That reminder is unlikely to fade quickly.
Practical Takeaways for Market Watchers
For anyone following energy markets, a few points stand out. First, monitor both Hormuz and Bab al-Mandab rather than treating them in isolation. Second, watch the language of official statements carefully; expansions of claimed enforcement zones matter. Third, keep the political calendar in view when assessing the likelihood of further escalation. Fourth, remember that insurance and freight costs often move before physical volumes do.
These are not dramatic insights. They are simply the practical habits that help separate noise from signal in a region where both appear regularly.
I will continue watching the next set of reports with the same mix of concern and analytical curiosity that these latest events have already produced. The Strait of Hormuz and the waters around Bab al-Mandab remain two of the most consequential stretches of ocean on the planet. When both show signs of heightened tension in the same week, the rest of the energy world pays attention. That attention is already visible in price action, and it is likely to remain for some time to come.
The story is still unfolding. Each new vessel movement, each new statement, and each new price reaction will add another layer. For now the central fact is clear: two critical shipping lanes are under unusual pressure at the same moment, and the market is responding accordingly.
What happens next will depend on decisions still being made in several capitals and on the operational choices of dozens of shipping companies. Those decisions will determine whether this week becomes a brief spike or the start of a more lasting adjustment in how the world moves its energy. Either outcome carries weight. The only certainty is that the waterways themselves remain as vital as ever.
In the end, the real test is not whether any single tanker is hit or any single mine is cleared. The real test is whether the cumulative effect of these incidents forces a durable change in risk perception across the industry. Early signs suggest that change is already underway. How far it goes is the question the coming weeks will begin to answer.