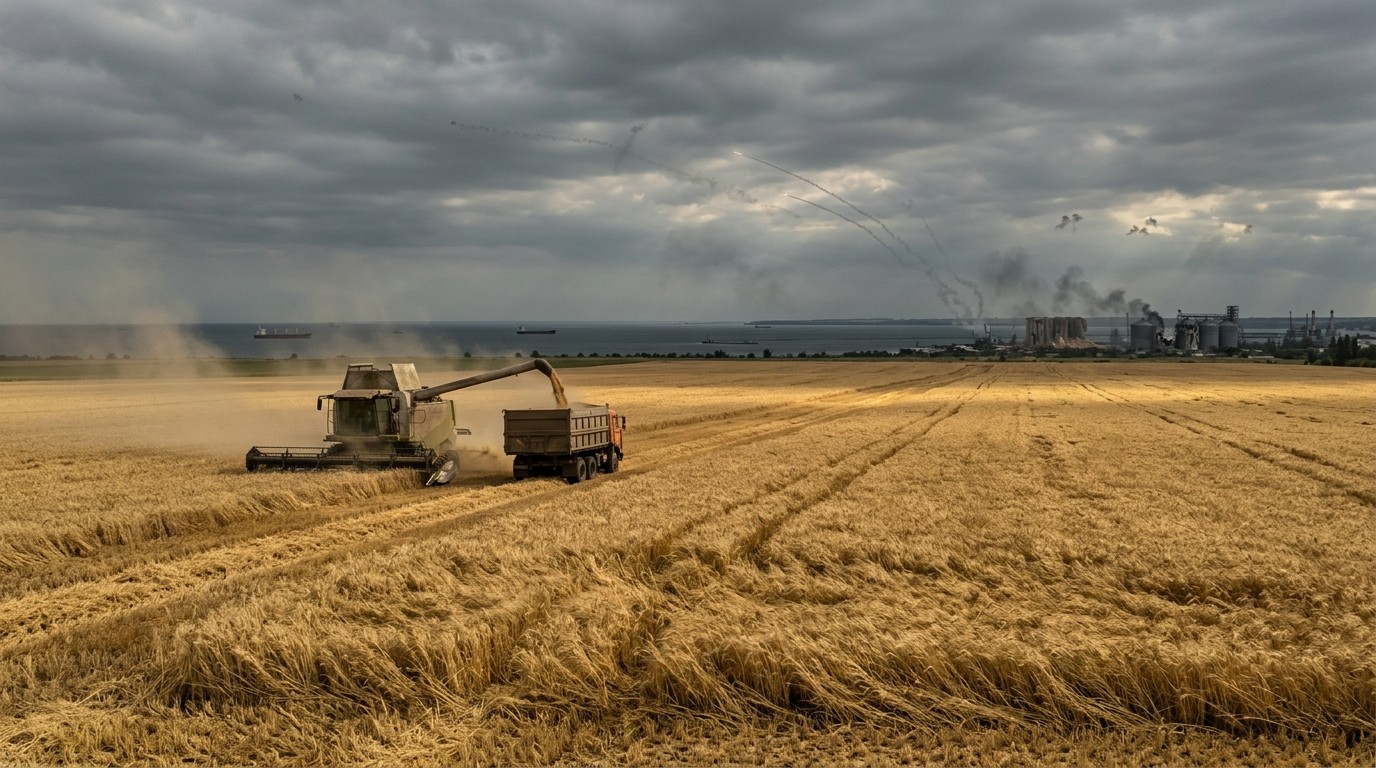

Have you ever wondered what it feels like to watch a strong harvest turn into a financial dead end overnight? Picture standing in a field in southern Ukraine, combine still warm from a solid yield of corn and sunflowers, only to realize most of that grain has nowhere profitable to go. Explosions echo a few hundred meters away. Storage bags and elevators sit full. Cash has run dry. That is the daily reality for many farmers right now, and it is starting to reshape what gets planted next season.
Why The Current Export Blockade Hits Harder Than Previous Years
Ukraine’s latest harvest looks decent on paper. Grains and oilseeds are expected to climb toward 85 million tonnes, up from around 80 million the year before. On the surface that sounds like progress. Dig a little deeper and the picture darkens fast. Carry-over stocks from last season already strain every available silo, plastic bag, and temporary storage site. Facilities that once moved product quickly now hold mountains of unsold crops. Russian drone and missile strikes on Black Sea targets intensified through the summer and into autumn, making commercial shipping nearly impossible to insure. Retaliatory hits have left Russian exports stuck as well. The result is a double squeeze on global supply lines that once moved more than half the world’s sunflower oil, nearly a fifth of its barley, and a solid share of wheat.
Around 90 percent of Ukraine’s main agricultural exports normally leave through Black Sea ports. In one recent month those shipments fell by more than half compared with the same period a year earlier. Alternative routes exist on paper—rail, road, river, even long overland paths through neighboring countries—but they remain slow, expensive, and limited in volume. Low water levels on the Danube have not helped. A key bridge has suffered damage. Eastern European neighbors resist larger transit volumes because a sudden flood of cheap grain would undercut their own producers. In my view, this combination creates a tighter bottleneck than anything seen since the full-scale conflict began.
Farmers Running Out Of Reasons To Plant
Talk to people working the land and the frustration becomes personal. One farmer in the Odesa region described how roughly 80 percent of his grain cannot be sold at a profit. After more than a decade of growing a mix of crops, he is scaling back hard. Corn and barley are off the list for next year. He is shifting toward oilseeds and niche crops that need less fertilizer and face fewer logistical headaches. Fertilizer itself remains expensive after broader regional tensions. The simple arithmetic no longer works: taxes, land rent, and operating costs keep coming while cash stays locked inside unsold inventories.
For the farmers, it’s very difficult because we need to pay taxes, we need to pay rent for land, and now we are not able to do this because we are not able to sell anything. The only crops we are able to sell are rapeseeds and sunflower seeds. But still, the volume is not enough. So why should we plant if today we have no profits at all?
Another voice from the agricultural community put it even more bluntly. If storage stays full, spring field operations start to look like a waste of time and money. Banks have stepped in with extra working capital—more than double the amount lent in the same period last year—yet that only papers over the deeper problem. Funds remain tied up in grain that cannot move. Some producers sell early at poor prices just to keep the lights on. Others with storage capacity wait and hope for better days. Both strategies carry risk.
I have found that the quiet shift in planting intentions may matter more than any single monthly export figure. When farmers deliberately cut back on the crops that once dominated their rotations, the effects ripple outward for years. Oilseeds and specialty crops help individual balance sheets in the short term, yet they cannot replace the sheer volume that wheat, corn, and barley once supplied to world markets.
Storage Pressure And The Daily Reality Of Conflict
Storage itself has become a vulnerability. Long plastic silobags stretch across fields. Tall metal elevators stand as visible targets. Every new harvest adds pressure. Meanwhile the war remains an ever-present backdrop. Farmers not currently called up for service still live and work under the constant possibility of a rocket or drone strike. One grower described sleeping while explosions occurred anywhere from 300 to 1,000 meters away. That kind of environment changes how people think about risk, investment, and the future of their land.
Labor shortages, mined fields, and earlier farm takeovers already complicated production. The current logistics collapse compounds those older wounds. International efforts to keep export corridors open have come and gone. Earlier arrangements collapsed. Overland solidarity routes through Europe remain politically sensitive and capacity-constrained. The situation inside the country now feels as severe as any point since the conflict escalated.
Global Markets Feel The Squeeze From Both Sides
Ukraine and Russia together once supplied a striking share of several key commodities. When both sides face export difficulties at the same time, the rest of the world notices. Europe is looking at a weaker corn harvest and still needs feed. The United States is also dealing with a softer corn crop. Better wheat and barley results in Canada, Australia, and Argentina, plus solid harvests in parts of the Middle East and North Africa, have provided some cushion so far. That cushion may not last through the winter if the blockade continues.
Commodity prices outside the two countries have received support from the restricted flow. Yet the flip side carries its own danger. A sudden ceasefire or reopened Black Sea corridor would release huge stockpiles of relatively cheap grain onto the market. Analysts who track these flows warn that prices in other origins could drop by several dozen dollars almost overnight. The market would flip fast and with little warning. Large inventories built up during the blockage would turn bearish for producers worldwide once the ships start moving again.
Perhaps the most interesting aspect is how low domestic prices inside Ukraine and Russia have become. That price gap intensifies the scramble for any alternative exit. Yet those alternatives remain difficult and slow from both countries. Rail and road capacity cannot match the volume once handled by deep-water ports. Land routes through the Baltic states or Georgia into Central Asia and the Middle East cover only a fraction of normal flows. Pricing remains the decisive factor. Even farmers near the western border of Ukraine still find Black Sea ports more profitable when they function. Without them, the entire system struggles.
Shifting Crop Choices And Longer-Term Consequences
Producers are already revising next year’s plans. Oilseeds and niche crops look more attractive because their prices depend less on long-haul logistics costs. Corn and barley, by contrast, suffer when transport becomes expensive or unreliable. Fertilizer availability and price add another layer of pressure. Regional conflicts beyond the immediate war zone have tightened global fertilizer markets, raising input costs at the exact moment cash flow is weakest.
- Reduced planting of high-volume grains risks lower overall output in future seasons
- Greater reliance on oilseeds may help individual farms but changes the mix available to buyers
- Storage and insurance challenges discourage long-term investment in infrastructure
- Labor and security issues continue to limit how much land can be worked effectively
These adjustments do not happen in isolation. When one of the world’s important grain regions dials back production of staple crops, importers in Asia, Africa, the Middle East, and Europe must look elsewhere. That search often means higher costs or thinner margins for everyone further down the chain. Feed buyers, food processors, and ultimately consumers feel the effects, sometimes with a lag of several months.
The Fragile Balance Of Current Price Support
Right now the blockage itself props up prices in other producing regions. That support can look welcome to farmers outside the conflict zone. Yet it rests on an unstable foundation. Any diplomatic breakthrough that restores shipping would reverse the situation quickly. Stockpiles currently trapped would enter the market and push prices lower across multiple origins. The speed of that reversal is what concerns many market watchers. There would be little time to adjust.
In my experience following these markets, the combination of strong local harvests and blocked exits creates exactly the kind of pressure that leads to sudden shifts later. Farmers who cannot sell today will plant less tomorrow. Lower planted area then reduces future supply just as global demand continues its usual growth path. The lag between those decisions and visible shortages can stretch across seasons, making the eventual impact harder to anticipate.
Alternative Routes And Their Practical Limits
People often ask whether rail, road, or river options can simply replace the Black Sea. The short answer is no, not at anything close to previous volumes or costs. Transit countries worry about their own producers being undercut. River levels fluctuate. Infrastructure damage takes time and money to repair. Overland routes through distant corridors add days and dollars that erase margins for many growers. The economics simply do not work for the bulk of the crop.
One agricultural representative stressed that Black Sea ports remain the only route that works on price for the majority of farmers, even those located far to the west. Selling across the land border into Europe looks less attractive once full logistics costs are counted. Without reliable sea access, the system does not function properly for large-scale production.
What A Prolonged Disruption Means For Food Security
Global food security has always depended on a handful of major exporting regions moving surplus efficiently. When two of those regions face simultaneous export constraints, the margin for error shrinks. Poorer importing nations feel the strain first. Higher prices for wheat, corn, barley, and vegetable oils translate into tighter household budgets and, in some places, reduced nutritional intake. Wealthier countries absorb the cost more easily but still see inflation in food categories.
The current winter period looks especially sensitive. Europe needs corn. Feed demand stays firm. Other origins can only stretch so far. If Ukrainian and Russian volumes remain bottled up, the gap has to be filled from somewhere, and somewhere usually costs more. At the same time, the threat of a sudden release of stockpiles hangs over the market like a cloud. Traders and buyers must plan for both continued tightness and the possibility of abrupt surplus.
I’ve noticed that discussions of food security sometimes stay abstract until the numbers start moving. When export figures drop by half in a single month and planting intentions shift away from staple grains, the abstract becomes concrete. The decisions being made in fields today will determine availability months from now.
Financial Strain On Farms And Supporting Institutions
Banks have increased lending to agricultural businesses, recognizing that operating expenses do not stop simply because sales are difficult. Working capital facilities have more than doubled in some recent periods compared with the previous year. Small and medium producers make up a large share of those loan books. The money helps cover immediate needs, yet it cannot solve the underlying problem of inventories that refuse to move at viable prices.
Different farms choose different paths. Some liquidate crops early, accepting lower returns to preserve liquidity. Others hold out, betting that prices will improve or that some corridor will reopen. Both approaches carry uncertainty. Rising interest costs and the ongoing need to finance autumn and spring campaigns add further pressure. When storage capacity itself becomes a military risk, the entire calculation grows more complicated.
Looking Ahead To The Next Planting Season
The coming weeks and months will reveal how far the shift in crop mix actually goes. If large numbers of farmers follow through on plans to cut corn and barley sharply, overall grain production potential declines. Oilseed expansion can offset some of the lost value for individual operations, but it does not replace the volume that global buyers have relied upon. Niche crops help diversify risk yet rarely scale to the same level.
Security conditions remain the wild card. As long as attacks on maritime targets continue, insurance stays difficult and shipping volumes stay low. Diplomatic efforts continue, yet progress has been limited. Farmers make decisions based on the reality they see in their fields and bank accounts, not on hopes for distant negotiations. That pragmatic approach is understandable. It also means the supply response may already be locked in for the next cycle.
One can hope that improved security allows ports to resume normal operations before the next major harvest. Until that happens, the pattern of full storage, thin margins, and cautious planting looks set to continue. The world still needs the grain that these regions produce. The farmers who grow it need a workable path to market. Right now those two needs remain painfully out of alignment.
Broader Market Implications And Price Volatility Risks
Commodity markets hate uncertainty, and the current situation supplies it in abundance. Prices outside the conflict zone receive artificial support from restricted flows. That support can reverse sharply if conditions change. Inventory levels that built up during the blockage would hit the market with force. Buyers who locked in higher-priced supplies from other origins could face sudden losses. Sellers who expanded production in response to elevated prices might see margins compress quickly.
The speed of any potential reopening matters as much as the fact of it. Markets can absorb gradual increases in supply. They struggle with sudden waves. Analysts familiar with these dynamics describe the possible price drop as something that could arrive with little warning. That prospect keeps many participants cautious even while current tightness supports prices.
In practical terms, the dual nature of the risk—ongoing tightness versus abrupt surplus—makes planning difficult for everyone from farm managers to government food agencies. Hedging strategies become more expensive. Inventory decisions grow more complex. The usual seasonal patterns that traders rely upon lose some of their predictive value.
Human Cost Behind The Commodity Numbers
It is easy to discuss tonnes and dollars and forget the people making daily choices under pressure. Farmers continue working land that can be struck at any moment. They manage payrolls and equipment loans while wondering whether the next truckload will find a buyer. Families live with the sound of nearby explosions as a background feature of ordinary life. The decision to plant less next season is not abstract strategy. It is a response to exhausted finances and limited options.
Supporting institutions try to help. Increased lending provides breathing room. Advice on crop diversification offers some path forward. Yet none of those measures restore the core advantage that Black Sea access once provided. Until reliable maritime routes return, the structural disadvantage remains.
I keep returning to a simple observation. Strong yields mean little if the grain cannot leave the farm at a price that covers costs. When that equation breaks for enough producers, the next harvest shrinks. The world eventually notices the difference, often at the least convenient moment.
Possible Paths Forward And Remaining Uncertainties
Several scenarios remain possible. Continued blockage would keep pressure on storage, encourage further planting shifts, and support prices elsewhere while raising food-cost concerns for importers. A partial reopening might ease some pressure without fully releasing stockpiles. A broader restoration of shipping would change the picture dramatically and quickly. Each path carries different implications for farmers, traders, and consumers.
What seems least likely is a rapid return to the pre-conflict pattern of high-volume, low-cost Black Sea exports. Even if security improves, infrastructure damage, insurance markets, and lingering risk perceptions will take time to normalize. Farmers will remember the seasons when grain sat unsold. Those memories influence future decisions long after the immediate crisis eases.
The coming months will show how deep the current planting adjustments run and whether any diplomatic progress can reopen viable export channels. Until clearer signals emerge, the combination of full storages, constrained logistics, and cautious farmers looks set to dominate the story of regional grain markets. The rest of the world has little choice but to watch closely, because the outcome will influence food availability and prices far beyond the Black Sea coast.
In the end, the strongest harvest means little without a path to market. Right now that path remains blocked for too many producers, and the consequences are already taking shape in next year’s planting plans. How long the blockage lasts, and how markets respond when it finally eases, will determine the next chapter for global grain supplies.