
Have you checked copper prices lately? They are sitting just a hair below all-time highs, and the market already feels stretched thin. Now a fresh labor dispute at one of Chile’s key operations is adding another layer of uncertainty. I keep thinking about how quickly these situations can snowball when physical inventories are already low.
Why This Chilean Strike Matters Right Now
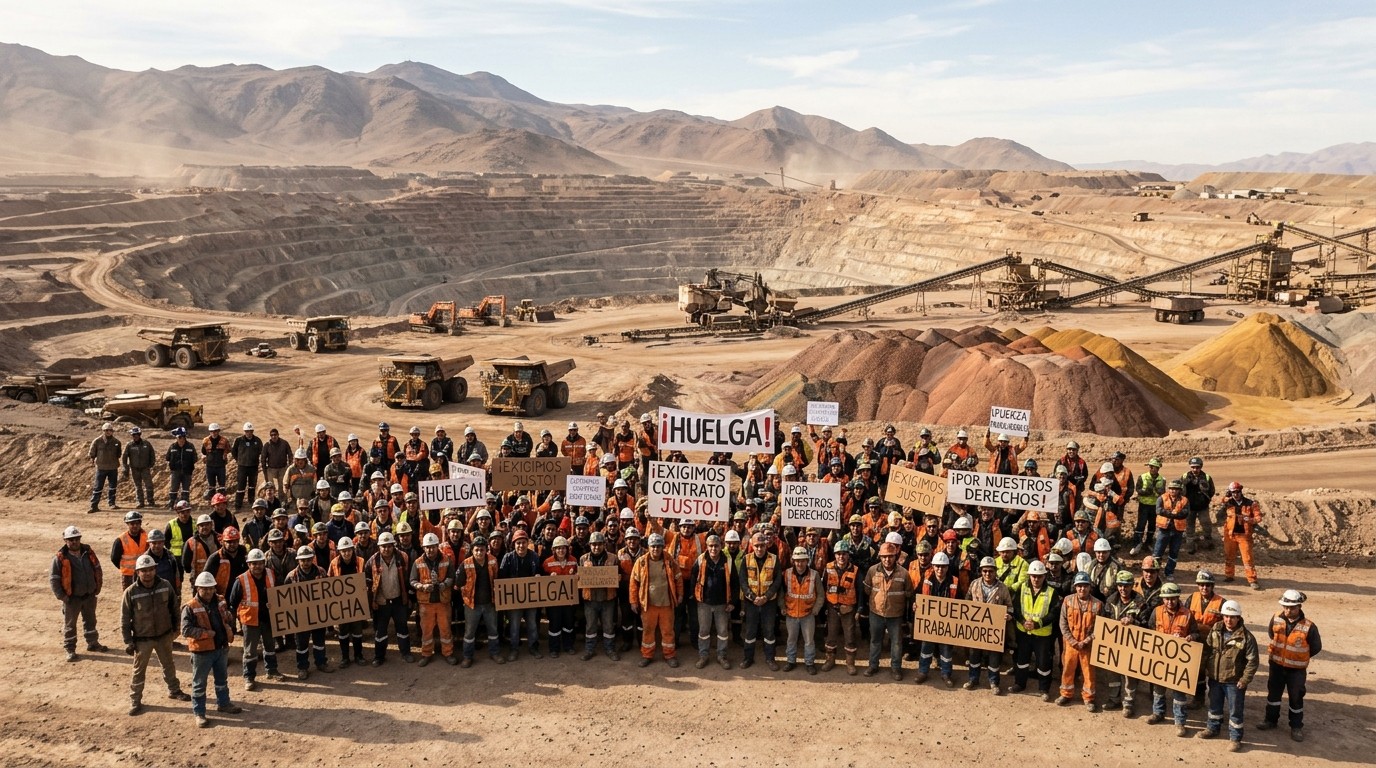
The latest development involves the Centinela mine, a major contributor to output from one of the larger copper producers in the region. Workers from two unions representing more than seven hundred people walked off the job after talks broke down. The core issue revolves around pay and benefit gaps between employees doing essentially the same work but belonging to different groups. Management reportedly turned down a proposed fix without putting a counter-offer on the table that satisfied the other side.
What stands out to me is the scale. This single site delivered around 240,400 metric tons of copper last year. That figure accounts for more than a third of the company’s total production. A long stoppage would not just dent quarterly numbers. It could also push back an important concentrator expansion that the industry has been watching closely.
Analysts following the story note that production might start to feel the effects within roughly two weeks if no resolution appears. In a market already dealing with tight physical availability, that timeline feels uncomfortably short.
The Broader Context of Tight Copper Markets
Copper has been under pressure from several directions at once. Global inventories have dropped to levels described by some researchers as unprecedented. Part of the squeeze comes from stockpiling activity in major economies. When the United States and China both build reserves, the metal available for everyone else shrinks fast.
I’ve noticed that industrial demand keeps expanding while new mine supply struggles to keep pace. Electrification, data centers, and renewable infrastructure all require substantial amounts of the red metal. That structural demand does not disappear just because one mine faces labor trouble. It simply makes any disruption more painful.
London futures recently hovered near 14,475 dollars a ton. That level sits close enough to previous peaks that any fresh supply scare can send prices higher in a hurry. Some market watchers have gone further, suggesting the current rally could still have significant room left if constraints persist.
The combination of tight physical markets, currency pressures, and policy moves is setting the stage for a sustained shift in how scarce resources are valued.
That perspective captures the mood among many commodity specialists right now. They see more than a temporary spike. They see a market that has been underinvested for years finally confronting the consequences.
Historical Patterns and What Might Happen Next
Companies in this sector often manage to settle disputes before they turn into extended shutdowns. There are examples from recent years where initial rejections and government mediation eventually produced agreements without a full stoppage. That track record offers some reassurance.
Still, every situation carries its own dynamics. The unions involved appear focused on fairness between different groups of workers. When the argument centers on equity rather than pure wage increases, compromises can prove harder to reach. I’ve seen similar cases elsewhere where the emotional side of the dispute prolonged the talks.
If the walkout continues, the immediate effect would show up in reduced concentrate and cathode output. Secondary effects might include delayed shipments to customers and higher costs for the operator as it tries to catch up later. For the wider market, even a temporary shortfall adds pressure to an already thin balance sheet of available metal.
How Production Disruptions Ripple Through Prices
Copper does not trade in isolation. A shortfall in Chile, the world’s largest producer, tends to lift premiums in other regions. Fabricators and manufacturers start competing more aggressively for remaining material. That competition often shows up first in the physical market before it fully appears in futures prices.
Consider the numbers involved. Removing even a portion of 240,000-plus tons from the annual total creates a noticeable gap. Markets that were already running with low visible inventories have little cushion. When traders and consumers realize the gap might last longer than expected, buying intensifies.
Some researchers have pointed to the possibility of prices moving substantially higher over the next couple of years if supply constraints remain unresolved. One outlook mentioned levels that would represent another large percentage gain from current prices. Whether that path materializes depends on many factors, but labor actions at major mines clearly belong on the list of risks.
The Human Side of Mining Labor Disputes
It is easy to discuss production numbers and price charts without remembering the people involved. Mining remains demanding work, often in remote locations with challenging conditions. Workers naturally want compensation structures that feel consistent across the same site.
When different unions end up with different packages for comparable roles, tension builds. That kind of disparity can undermine morale even when absolute pay levels look competitive. Management faces its own pressures. Wage settlements set precedents that affect other operations and future negotiations. Finding a middle ground that satisfies both sides is rarely simple.
In my view, the most constructive outcomes usually emerge when both parties keep talking rather than digging into fixed positions. Mediation has helped in the past. Whether it can still produce results after the strike has already started remains an open question.
What Investors and Market Participants Should Watch
Several signals will matter in the coming days and weeks. First is any official update on the duration of the stoppage. Second is commentary from the company about contingency plans or inventory buffers. Third is the reaction in nearby physical markets, where premiums often move before exchange prices.
- Progress or setbacks in mediation efforts
- Actual production figures reported for the affected period
- Changes in global inventory reports
- Shifts in treatment and refining charges for concentrates
- Broader sentiment among industrial consumers
Anyone following industrial metals knows these situations rarely stay contained. A prolonged disruption at a high-profile mine tends to attract attention from funds and speculative accounts that amplify price moves. That dynamic can turn a regional labor issue into a global pricing event.
Structural Challenges Facing Copper Supply
Labor risk is only one piece of a larger puzzle. Bringing new copper projects online takes years and faces increasing regulatory, environmental, and community hurdles. Existing mines age and grades decline. The industry has not replaced depleted reserves as quickly as demand has grown.
Chile itself illustrates the point. The country remains the top producer, yet output growth has slowed in recent years. Water scarcity, energy costs, and social expectations all complicate expansion plans. When an established operation like Centinela faces a work stoppage, the margin for error shrinks further.
Perhaps the most interesting aspect is how these constraints interact with the energy transition. Policymakers promote electric vehicles, grid upgrades, and renewable generation. All of those technologies need copper. The same policymakers sometimes create additional obstacles for the mining projects that would supply the metal. That tension is unlikely to disappear soon.
Potential Timeline and Market Implications
If the dispute resolves quickly, the impact may prove limited. Markets have a way of looking past short interruptions when confidence in a settlement exists. If the stoppage stretches into weeks, however, the calculation changes. Production losses become harder to recover within the same year. Expansion schedules slip. Customers begin searching for alternative sources, driving up costs across the board.
I find it useful to think in terms of cumulative effect. One mine strike by itself rarely transforms the entire market. Multiple disruptions, combined with low inventories and steady demand growth, create a different environment. The current episode arrives at a moment when the market already feels vulnerable.
Prices near record territory leave little room for complacency. Any fresh supply concern can trigger rapid repositioning among traders. That volatility cuts both ways, of course. A sudden resolution can reverse the move just as quickly. Still, the asymmetry favors higher prices when physical tightness is the dominant theme.
Looking Beyond the Immediate Dispute
Even after this particular strike ends, the underlying issues will remain. Copper faces a multi-year challenge of matching growing demand with reliable supply. Labor relations form one part of that challenge. Project development, permitting, capital allocation, and geopolitical factors all play roles as well.
Market participants who focus only on the next price tick risk missing the larger story. The metal has moved from a cyclical industrial commodity toward something closer to a strategic resource. Governments notice when inventories drop and prices climb. Stockpiling behavior already reflects that shift.
In my experience, the best approach is to track both the short-term noise and the long-term constraints. The current labor action belongs firmly in the noise category for now. Yet it highlights the constraints that make noise so potent.
Key Factors That Could Influence the Outcome
Several elements will determine how this situation develops. The willingness of both sides to return to the table matters most. Government involvement through mediation can sometimes break deadlocks. Public statements and the tone they strike also influence negotiating room.
Operational realities play a role too. Mines cannot always restart at full capacity the day after a strike ends. Equipment needs checks. Workforces need reintegration. Lost production is rarely recovered fully in the short term.
From a market perspective, the critical question is whether this disruption remains isolated or coincides with other supply issues elsewhere. Copper production is spread across multiple countries, but concentration risk still exists. Chile and a handful of other nations account for a large share of global output.
Why Timing Matters in Commodity Markets
Disruptions arrive at different moments with different consequences. A strike during a period of ample inventories often passes with limited price reaction. The same strike during a period of scarcity can amplify moves dramatically. Right now inventories sit at low levels by historical standards. That fact raises the stakes.
Currency movements and broader risk sentiment also influence how commodity prices respond. When the dollar weakens or industrial confidence rises, copper tends to find support. Labor news then acts as an additional catalyst rather than the sole driver.
I’ve found that the most reliable signals often come from the physical market rather than pure speculation. Watching premiums, warehouse flows, and consumer buying patterns provides a clearer picture of real tightness than futures open interest alone.
Balancing Optimism and Caution
History shows that most mining strikes eventually settle. Companies and unions share an interest in keeping operations running over the long term. That shared interest creates pressure toward compromise. At the same time, underestimating the duration of a dispute can prove costly for anyone relying on uninterrupted supply.
For the broader copper market, the episode serves as a reminder. Supply remains vulnerable to operational and social risks. Demand continues to grow on structural trends that show little sign of reversing. The gap between those two forces is what keeps prices elevated and volatility present.
Whether this particular stoppage proves short or extended, it reinforces the case for treating copper as a market where physical constraints matter more than they have in previous cycles. That perspective has guided a lot of recent analysis, and the current labor action fits squarely inside it.
The coming days will reveal whether talks resume productively or whether production losses start to accumulate. Either way, the episode has already focused attention on a market that was already on edge. In a commodity as strategically important as copper, that attention is unlikely to fade quickly.
Keeping an eye on developments at Centinela makes sense for anyone involved with industrial metals. The numbers involved are large enough to move the needle, and the timing could hardly be more sensitive. How the story unfolds will tell us something useful about both this specific mine and the broader state of copper supply.