
Have you ever watched a nuclear funding announcement and wondered how a company still in stealth mode can suddenly be worth nearly two billion dollars? That exact question hit me when news broke about Atlas Atomics closing a massive Series A. The numbers alone make you pause. Roughly four hundred million dollars raised at a valuation around one point nine billion, led by General Catalyst with Andreessen Horowitz also in the mix. And the person whose name keeps popping up? Vivek Ramaswamy, currently campaigning for governor of Ohio, yet still deeply tied to this nuclear bet.
Why This Particular Nuclear Startup Stands Out Right Now
Most advanced reactor companies are racing after the same limited supplies of high-assay low-enriched uranium. Atlas Atomics is taking a completely different path. The company is building around a heavy water reactor concept, the same broad family that has powered Canada’s CANDU fleet and India’s pressurized heavy water units for decades. That single design choice changes almost everything about the fuel story.
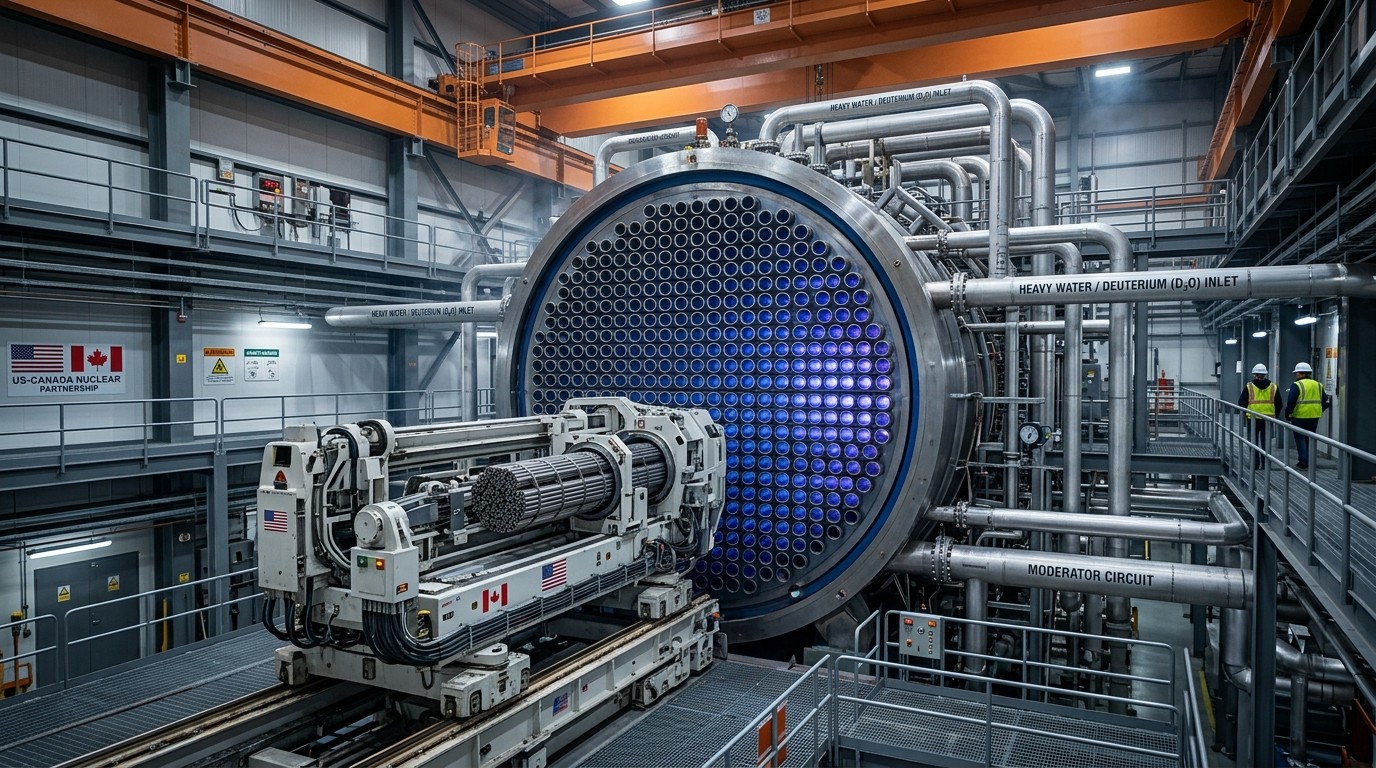
Heavy water, or deuterium oxide, slows neutrons without absorbing as many of them as ordinary light water does. The result is a reactor that can run on natural uranium. No enrichment plant required. In a market still waiting for domestic HALEU production to scale, that is a meaningful advantage. I’ve looked at a lot of these pitches, and the enrichment bottleneck keeps showing up as the quiet killer of timelines. Atlas is simply walking around it.
The People Behind the Stealth Mode Company
Ramaswamy is a cofounder and backer, but day-to-day operations sit with Kevin Gan. Gan spent more than fifteen years investing in energy, most recently at Millennium and earlier at D.E. Shaw. That background matters. He understands both capital markets and the practical realities of large energy projects. The technical side is led by Balendra Sutharshan, former chief operating officer at Oak Ridge National Laboratory. When you put those two resumes next to a heavy water design, the bet starts to look less speculative and more calculated.
The company is not completely invisible. Earlier this year it was selected for the second round of the Department of Energy’s Nuclear Energy Launch Pad program. That recognition gave the first public hint that something serious was forming. A letter of support sent to Utah’s energy office later confirmed the geographic focus. Utah looks like the place where Atlas wants to break ground first.
What Heavy Water Actually Delivers
Let’s walk through the practical upsides that come with this design family. First, natural uranium fuel removes the enrichment step entirely. Second, the reactor uses hundreds of individual pressure tubes rather than one massive forged vessel. Those giant vessels are made in only a handful of specialized foundries, mostly in Asia. Pressure tubes can be manufactured more widely and replaced if needed. Third, online refueling is possible. Fuel bundles can be swapped while the plant continues to generate power, which means no lengthy refueling outages.
There is also an isotope angle that rarely gets enough attention. Canadian heavy water reactors have long supplied a large share of the world’s cobalt-60, used for sterilizing medical equipment and treating certain cancers. Atlas has openly listed medical and industrial isotopes among its goals, alongside reliable power and fuel recycling. That multi-product approach could create additional revenue streams once the plants are running.
The goals are reliable power, more medical and industrial isotopes, and nuclear fuel recycling.
That combination feels pragmatic. Power sales alone can be tough in competitive markets. Adding isotopes and recycling services gives the business model more ways to win.
The Supply Chain Reality Check
Skipping enrichment does not mean the path is free of obstacles. The United States currently has no commercial fabrication line for CANDU-style natural uranium fuel bundles. That capacity would need to be built. Heavy water itself is another story. Separating deuterium oxide from ordinary water is energy intensive and expensive. North American supply sits largely in Canada with existing CANDU operators. Atlas would either import it or help create new domestic production before the first reactor is filled.
In fairness, almost every advanced reactor developer faces similar fabrication hurdles. Companies working with metallic fuel or specialized particle fuel also need new manufacturing plants. The difference is that Atlas is dealing with technologies that already have decades of commercial operating history rather than brand-new fuel forms that still need qualification.
Competition Is Already Forming
Atlas will not have the heavy water space to itself in the United States. AtkinsRealis, the company that licenses CANDU technology, submitted a notice of intent to the Nuclear Regulatory Commission earlier this year to begin the licensing process for CANDU reactors on American soil. Progress has been quiet since that letter, yet the intent is clear. An organization with decades of experience refurbishing heavy water plants, sometimes under budget and ahead of schedule, is now looking south of the border.
That competitive pressure could actually help the overall market. Multiple players raise the visibility of the technology and may encourage more domestic investment in heavy water production and fuel fabrication. Still, first-mover advantage in siting and regulatory familiarity will matter a great deal.
The Broader Wave of Nuclear Capital
Atlas is far from alone in attracting large checks. Venture capital has poured roughly four point six billion dollars into American nuclear startups this year alone. Other companies have closed eye-catching rounds as well. One raised four hundred seventy million after its first unit went critical in a Department of Energy pilot program. Another closed a billion-dollar Series B. The money is clearly available.
Policy tailwinds are helping. An executive order aiming to quadruple United States nuclear capacity by 2050 has focused attention and capital. Suddenly the limiting factor is less about finding investors and more about execution, supply chains, and regulatory timelines. That shift changes the entire risk profile for companies that can actually deliver hardware.
Utah as the Launch Pad
The letter Atlas sent to Utah’s energy development office was more than polite correspondence. It signaled concrete interest in a state that has been actively courting advanced nuclear projects. Reliable baseload power, isotope production, and fuel recycling form a package that aligns with many of Utah’s stated energy priorities. If the company can move from letter to site selection and then into licensing, the timeline could become one of the faster ones in the current cohort of startups.
I’ve watched enough energy projects to know that local support is rarely the hard part once the economics look solid. The harder work sits in proving the design to regulators, locking down the heavy water supply, and building the fuel fabrication capability. Those three items will determine whether the two-billion-dollar valuation holds up over the next five years.
Looking at the Trade-Offs Honestly
Every reactor technology carries compromises. Heavy water systems require ongoing management of deuterium oxide inventory and careful attention to tritium production. The pressure tube design allows online refueling and easier component replacement, yet it also means more individual components that must be monitored. Natural uranium fuel is simpler in one sense and more constrained in another because the fuel cycle economics differ from enriched systems.
Still, the accumulated operating experience from Canada and India provides a large body of data that pure first-of-a-kind designs simply do not have. That experience should translate into faster learning curves once the first American units are built. In my view, that historical track record is one of the stronger parts of the Atlas thesis.
What Success Would Actually Look Like
If Atlas reaches commercial operation, several things would change at once. A domestic source of natural uranium fuel bundles would exist. A new heavy water production pathway might open. Medical isotope supply would become less dependent on a handful of aging foreign reactors. And the United States would have another proven reactor type available for utilities that want options beyond light water designs.
The isotope business alone deserves more attention than it usually receives. Global demand for sterilization and cancer treatment isotopes continues to grow. A new American source would be welcomed by hospitals and device manufacturers that currently rely on long international supply chains.
The Quiet Strength of Proven Technology
There is a temptation in the advanced nuclear space to chase the most novel physics. Atlas is doing the opposite. It is taking a mature reactor family and adapting it to American regulatory and supply chain realities. That approach may look less flashy than molten salt or high-temperature gas concepts, yet it could prove more bankable for risk-averse utilities and industrial customers.
The valuation already reflects high expectations. Delivering on them will require disciplined execution on heavy water logistics, fuel fabrication, and regulatory engagement. The team appears well positioned for that work. Whether the market continues to reward the strategy will depend on how quickly the first concrete milestones appear.
For now, the story remains one of the more interesting developments in a sector that is suddenly flush with capital. A reactor that skips enrichment, aims for Utah, and carries decades of international operating experience behind it is worth watching closely. The next chapters will be written in licensing documents, supply contracts, and construction schedules rather than press releases. That is usually when the real test begins.
The nuclear renaissance everyone talks about will not be built on hype alone. It will be built on designs that can actually be manufactured, fueled, and operated at reasonable cost. Atlas Atomics is placing a large bet that heavy water technology still has a significant role to play in that future. Given the current constraints on enriched fuel, it is a bet that feels increasingly rational.
Investors clearly agree. Four hundred million dollars is not pocket change, even in today’s nuclear funding environment. The coming years will show whether that capital turns into operating reactors and isotope production lines or becomes another expensive lesson in the difficulty of nuclear project development. For the moment, the company sits among the most richly valued names in the sector, still largely unseen by the public, and holding a design philosophy that deliberately avoids the enrichment bottleneck holding so many others back.
That combination of capital, experienced leadership, and a technology with a long commercial history makes Atlas one of the more distinctive stories in the current wave of nuclear startups. The pressure tubes, the natural uranium fuel, and the isotope potential form a coherent package. Turning that package into concrete megawatts and medical isotopes is the hard work still ahead. Few companies have entered that race with quite this much early financial firepower behind them.