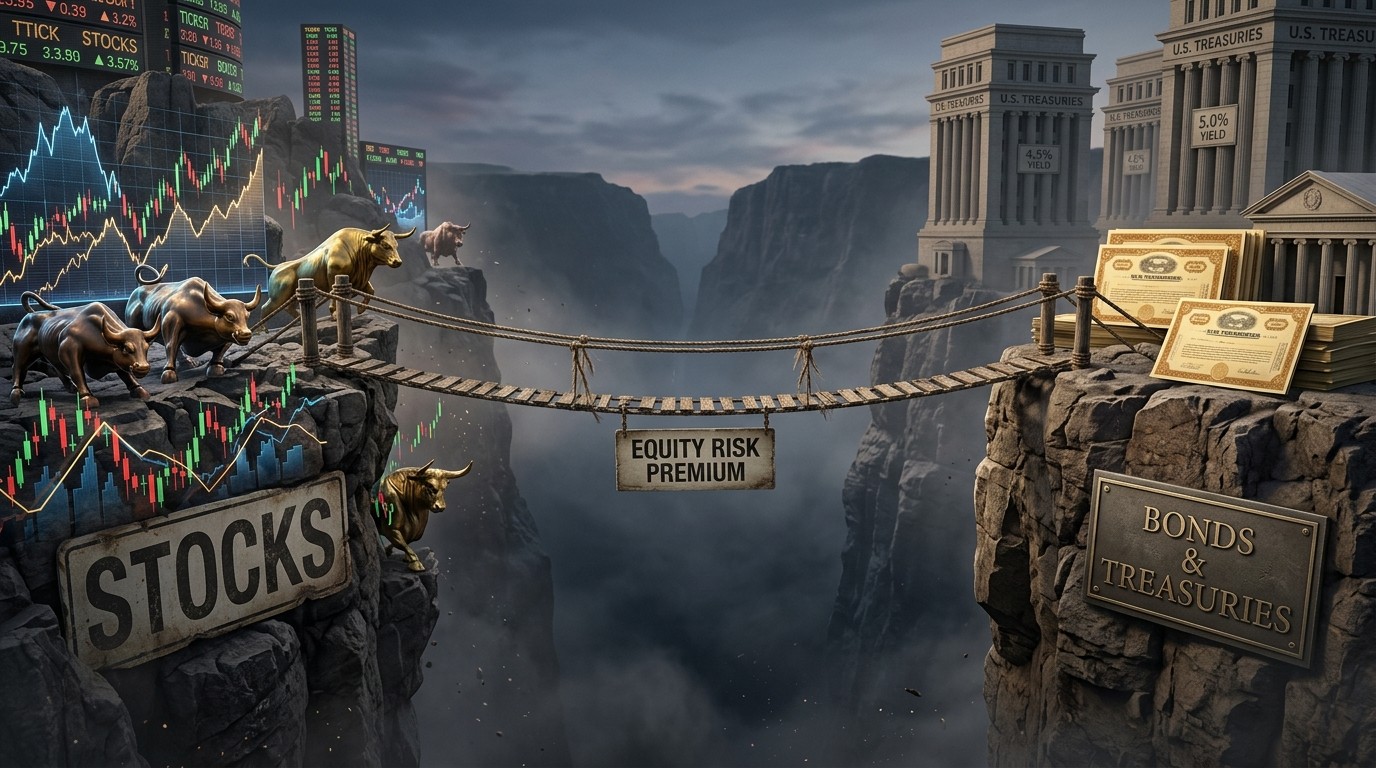

Have you noticed how quiet things feel when the usual reward for taking risk simply disappears? I keep coming back to that thought every time I look at the current numbers. The extra return investors have historically demanded for holding stocks instead of safer government bonds has basically evaporated. In some measures it has even gone negative. That single fact changes the entire conversation about whether the market still offers a fair deal.
Why The Equity Risk Premium Matters More Than Most People Realize
Let’s start with the basic idea. The equity risk premium is simply the difference between what stocks are expected to return and what a risk-free bond pays. For decades that gap stayed positive on average. Investors accepted the ups and downs of the stock market because they expected to be compensated for the ride. Right now that compensation looks thin to the point of vanishing.
At recent levels the S&P 500 trades at roughly 26 to 27 times trailing earnings. That works out to an earnings yield near 3.7 percent. Meanwhile the 10-year Treasury has climbed above 5 percent. Do the simple subtraction and you see stocks currently “earn” less than a government note. I find that comparison hard to ignore.
Some people prefer forward earnings. Even there the picture stays tight. Optimistic estimates put the forward earnings yield right around the same level as the 10-year yield. In other words, even if everything goes according to the most cheerful Wall Street forecasts, you still get almost no extra pay for taking equity risk.
Looking Back At Moments When The Premium Turned Negative
History offers a useful filter. A negative premium by itself has not always been a disaster signal. During parts of the early 1980s the gap stayed underwater for months. Bond yields sat in double digits. Stocks looked cheap by almost any measure, with earnings yields often above 5 percent and sometimes much higher. Investors who bought during that stretch enjoyed strong real returns over the following decade.
The difference today is the starting valuation. When the premium sits negative and the earnings yield also sits below 5 percent, the average real return over the next ten years has historically been much lower. More than one in four of those periods actually finished underwater. Most of those episodes clustered around the late 1990s and the peak of the dot-com era. That combination of rich prices plus a missing premium is the one that worries me.
I’ve spent time sorting monthly data back to 1950. The pattern is clear enough. Cheap stocks with a temporary negative premium often recovered once yields fell. Expensive stocks with a negative premium tended to deliver disappointing long-run results. We currently sit closer to the expensive side of that ledger.
Cash And Bonds Suddenly Look Competitive Again
For roughly fifteen years after the financial crisis, cash paid almost nothing. That environment created the familiar “there is no alternative” mindset. Savers felt pushed into stocks because every other option looked worse. The flow can reverse when safer assets start paying real money.
A 5.3 percent Treasury held to maturity offers a contractual return with no drawdown risk if you simply wait. Stocks have delivered roughly 10 percent annualized over very long periods, yet that figure assumes average starting valuations. We are not starting from average. The gap between hoped-for equity returns and locked-in bond yields has narrowed enough that many investors are reconsidering the trade-off.
I still keep bonds in most portfolios for a practical reason. They act as ballast when equity markets stumble. A 25 percent decline in stocks requires a 33 percent recovery just to break even. A deeper 50 percent drop demands more than a double. Bonds reduce the depth of those drawdowns and shorten the time needed to climb back. For anyone withdrawing money in retirement, that difference compounds in a meaningful way.
Income is better today than at any point in two decades. The 10-year yields more than three times what it paid at the end of 2021. That is contractual cash flow rather than hoped-for appreciation.
Behavioral data also tells a cautionary tale. Average fixed-income investors have often captured only a fraction of the returns their asset class actually delivered. They sell after prices fall and buy back after prices recover. The same pattern shows up in equity markets, only the swings tend to be larger. Having a steady income stream reduces the pressure to sell stocks at the wrong moment.
Two Paths That Could Restore The Premium
A negative equity risk premium does not stay negative forever. It normalizes in one of two ways. Either bond yields fall or stock prices adjust downward. Both outcomes can happen at the same time, of course.
If yields decline because of softer growth or a shift in inflation trends, the premium rebuilds from the bond side and equity valuations look more attractive by comparison. If yields stay elevated, the pressure falls more heavily on stock prices. I lean toward the view that heavy debt loads eventually create disinflationary forces, which would favor the first path. Still, markets can take their time getting there.
Measuring stocks against inflation-protected Treasuries instead of nominal ones leaves a thin positive premium in some calculations. The higher end of that range depends on strong earnings growth arriving on schedule. Nearly 30 percent growth is a high bar. I prefer to stay cautious when the optimistic case is required for the numbers to look comfortable.
Practical Adjustments Rather Than Dramatic Moves
None of this discussion suggests dumping every stock position before the calendar turns. Seasonal patterns, earnings reports, and corporate buybacks still lean supportive into year-end. The equity risk premium is a long-horizon signal, not a short-term timing tool. It does argue for thinking carefully about position sizes and overall risk exposure.
In practice that has meant modest adjustments. Duration on the bond side has been shortened a bit while overall bond allocations remain in place across balanced models. Bonds are not exciting. They simply remain one of the cheapest forms of insurance against an early equity drawdown during the withdrawal phase of a retirement plan.
Forty percent in bonds is not a law of nature. The right number depends on income needs, time horizon, and honest tolerance for watching account values fall. Some investors choose to hold less. That decision is fine as long as the remaining equity risk is managed deliberately.
Duration helps in a growth shock and hurts in an inflation shock. If inflation risk keeps you awake at night, shorter-duration holdings and inflation-sensitive assets make more sense. The key is matching the tool to the actual worry rather than following a fixed recipe.
What The Near-Term Calendar Still Offers
Even with a thin long-term premium, shorter-term catalysts continue to matter. Earnings season brings a wave of bank reports that will reveal how loan growth and credit quality are holding up with yields near multi-year highs. Inflation data arrives at a sensitive moment, just before the central bank enters its quiet period ahead of the next policy meeting.
Markets currently assign a low probability to an immediate rate hike yet a much higher chance of action by year-end. Any surprise in the inflation numbers can move the two-year yield quickly and, by extension, influence equity sentiment. Oil prices remain a wildcard that can shift inflation expectations overnight.
From a trading perspective the level that matters is the recent record close. A sustained move above that zone with broader participation would open room for further gains. Pullbacks toward the 50-day average have so far attracted buyers. A break below the September low would shift the near-term posture toward neutral and justify higher cash or hedge levels.
Rebalancing winners back to target weights ahead of earnings remains a sensible habit. Using the 50-day average as a soft stop-loss line helps keep emotion from overriding process. None of these tactics guarantee success, yet they keep risk deliberate rather than accidental.
The Behavioral Trap Waiting On Both Sides
Perhaps the most underappreciated risk right now is behavioral. When bonds finally pay a respectable yield, some investors swing too far toward safety and miss eventual equity recoveries. Others stay fully invested in expensive stocks and underestimate how long it can take to recover from a large drawdown.
I’ve watched both mistakes play out. The investors who fare best usually decide in advance how much equity risk they can tolerate, size their bond holdings accordingly, and then leave the mix alone through the inevitable noise. That sounds simple. In practice it requires resisting the urge to react to every headline.
Income from bonds today reduces the need to sell equities during weak periods. That single change can improve the odds of staying invested through the full cycle. Over a multi-decade retirement timeline the compounding effect of avoiding forced sales is substantial.
Putting The Pieces Together Without Panic
The current environment is unusual but not unprecedented. A negative equity risk premium combined with elevated valuations has appeared before. The 1980s version resolved favorably because stocks started cheap. The late-1990s version resolved less kindly because stocks started expensive. We sit closer to the second pattern.
That does not mean equities must fall tomorrow. It does mean the margin of safety is thinner than it has been for a generation. When safer alternatives pay more than 5 percent with no principal risk if held to maturity, the hurdle for owning stocks rises.
I’ve found that the most useful response is neither full retreat nor stubborn optimism. Maintain exposure to equities for long-term growth. Keep meaningful bond allocations for ballast and income. Adjust duration and position sizes as conditions evolve. Rebalance systematically rather than emotionally.
The bond market is finally paying investors to wait. The stock market continues to charge a full price for impatience. Understanding that trade-off clearly is the first step toward navigating the period ahead with eyes open.
Over the coming months the data will reveal whether earnings growth can justify current valuations and whether yields eventually ease. Until those questions are answered, treating risk as a scarce resource rather than an unlimited one feels like the prudent path. The equity risk premium has vanished for now. History suggests it will reappear, yet the path it takes to get there will shape portfolio outcomes for years.
In my own work I keep returning to one simple test. If the premium stays this thin and valuations stay this rich, the expected real return from equities over the next decade looks modest. That does not make stocks unownable. It does make thoughtful allocation more important than ever. Cash and high-quality bonds now offer a genuine alternative. Using them deliberately can turn a difficult environment into a manageable one.
The conversation does not end with a single number. It continues with questions about time horizon, withdrawal needs, and personal tolerance for volatility. Those answers differ for every investor. The data simply reminds us that the usual compensation for equity risk is currently missing in action. Acting as if that fact does not matter would be the larger mistake.
Markets have a way of surprising both the overly cautious and the overly confident. The investors who prepare for a range of outcomes, rather than a single narrative, tend to sleep better and compound more steadily. Right now that preparation includes acknowledging a vanished equity risk premium and the elevated prices that accompany it. From there the choices become clearer, even if the path remains uncertain.
I will keep watching the spread between earnings yields and Treasury yields. When that gap begins to widen again, whether through lower stock prices or lower bond yields, the risk-reward balance will improve. Until then, patience and balanced positioning look like the more reliable companions.
The numbers are straightforward. The implications require judgment. That combination is what makes the current moment both challenging and interesting for anyone managing capital over a multi-year horizon.