


Have you ever watched oil prices twitch like a nervous animal the moment headlines start flashing about the Middle East? That exact feeling hit traders hard this weekend. Fresh attacks on tankers and another strike on a major airport sent crude climbing again at the futures open, pushing WTI back toward the highs we saw on Friday. The market did not need much encouragement. Supply fears were already simmering, and this new wave of violence poured fuel on them.
Why The Latest Wave Of Attacks Matters More Than Usual
Something shifted over the past few days. It was not just one isolated incident. Several tankers took hits in and around the Strait of Hormuz, and the Houthis launched yet another strike on Riyadh’s international airport. At the same time, Iran’s forces claimed full control over the waterway that carries a huge share of the world’s oil. When those three developments land in the same news cycle, prices tend to move fast.
I have watched these kinds of spikes before. Sometimes they fade within hours. Other times they stick because the physical market is already tight. Right now the second scenario looks more likely. Global diesel stocks remain under pressure, tanker rates keep climbing, and any fresh disruption in the Gulf region lands on a market that has little spare capacity to absorb it.
Multiple Tankers Hit In A Short Window
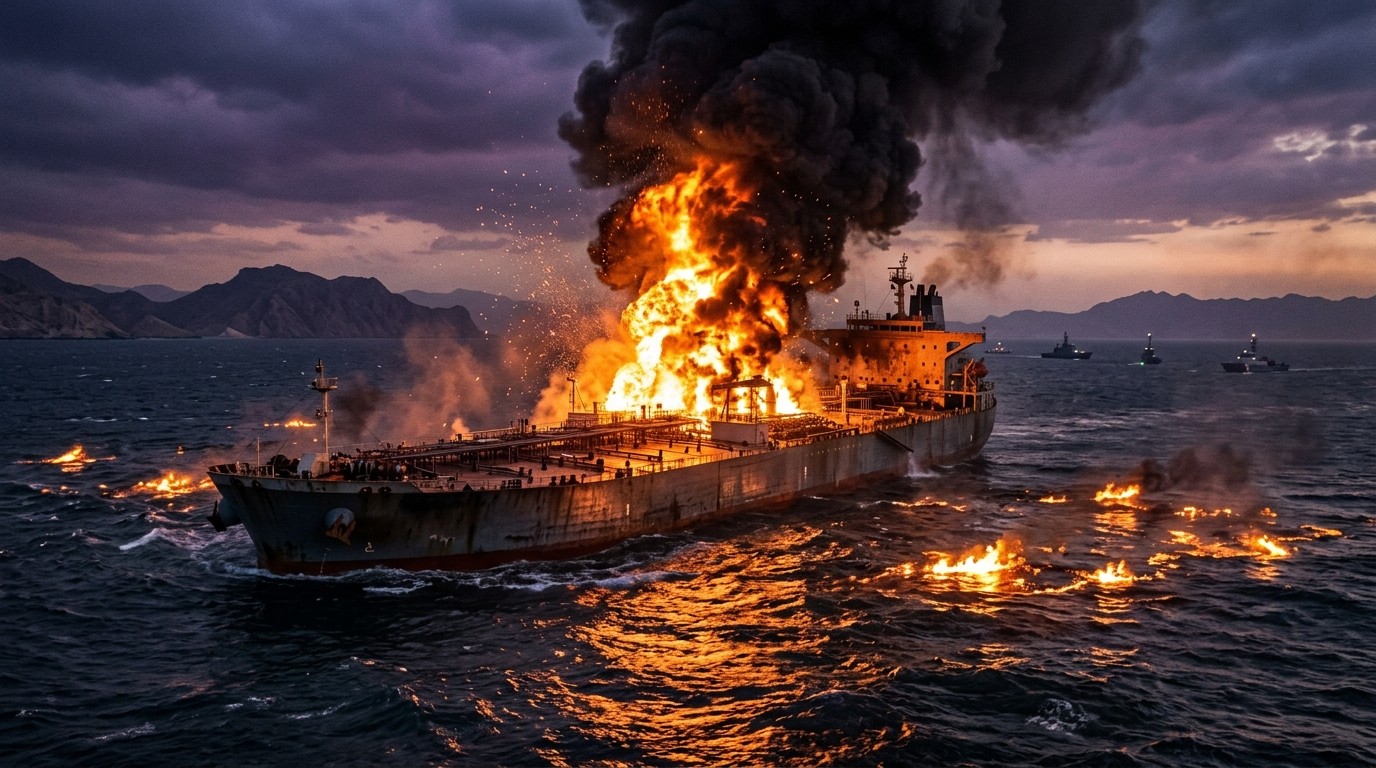
Reports over the weekend described at least two, and possibly three, vessels suffering damage in less than twenty-four hours. Most of the incidents involved sea mines. Videos circulating online showed tankers on fire after striking objects in the water. One of those ships was a large crude carrier that suffered an explosion in its engine room. Another vessel leaving the strait was struck by an unidentified projectile. A separate Panama-flagged cargo ship traveling from an Iranian port was also targeted.
The pattern feels deliberate. When several ships get hit in such a short period, the message is hard to miss. Commercial traffic through the strait is now operating under a higher level of risk than it has faced in months. Crews are on edge. Insurers are raising rates. Charterers are starting to think twice about routing decisions. All of that adds cost and friction to the system that moves oil from the Gulf to the rest of the world.
Since the broader conflict intensified earlier this year, the number of commercial vessels attacked in the region has climbed sharply. Dozens of ships have been targeted and a significant number of sailors have lost their lives. That human cost rarely shows up in the price charts, yet it shapes the decisions that shipowners make every day. Fewer willing crews and higher insurance premiums eventually translate into tighter effective supply.
Claims Of Full Control Over The Strait
Iranian forces stated publicly that they now exercise complete control over the Strait of Hormuz and will punish vessels that ignore their rules. They described one of the damaged tankers as having tried to leave through an unauthorized route. Whether every detail of that claim holds up under scrutiny is almost secondary. The fact that the statement was issued at all changes the risk calculation for every operator moving crude through those waters.
In practical terms, the strait remains one of the most important chokepoints on the planet. A large share of global seaborne oil still has to pass through it. Even temporary restrictions or the threat of further attacks can force ships to wait, reroute, or simply stay in port longer than planned. Those delays do not show up as lost barrels on a spreadsheet right away, but they tighten the physical market all the same.
When a major producer or its proxies start talking about controlling a critical waterway, traders stop focusing on the next inventory report and start thinking about the next possible disruption.
That shift in mindset is already visible in the price action. WTI pushed higher as soon as the evening session opened. The move was not frantic, but it was purposeful. Buyers who had been waiting for a dip suddenly decided the risk of missing further upside was greater than the risk of buying too early.
Airport Strikes Add Another Layer Of Tension
While the tanker story dominated the maritime headlines, the Houthis launched another attack on King Khalid International Airport in Riyadh. The previous day’s strike had already left a dozen people dead and hundreds injured. The latest projectile hit terminal facilities and sparked a fire. Authorities reported additional injuries and closed the airport while they assessed the damage.
Airports are not oil infrastructure in the narrow sense, yet they sit inside the broader energy and economic landscape of the kingdom. Repeated attacks on a major travel hub force airlines to cancel or divert flights, keep schools online, and remind markets that the conflict can reach deep into civilian and commercial space. That kind of pressure tends to keep geopolitical risk premiums alive even when the direct oil facilities themselves are not hit.
In my view the airport strikes matter because they show the conflict is not contained to the waterways. When both shipping lanes and key urban infrastructure face repeated threats, the overall sense of regional stability deteriorates. Energy markets hate uncertainty more than almost anything else, and right now uncertainty is rising.
Diesel Markets Already Look Tight
The International Energy Agency has been watching the diesel situation closely. Officials urged member countries to accelerate the release of pledged emergency stocks and to consider additional volumes if needed. The agency specifically highlighted diesel as the priority product. That request did not come out of nowhere. Global middle-distillate markets have been under strain for some time, and any fresh disruption in the Gulf region only adds to the pressure.
Diesel is the workhorse of the industrial and transport economy. When its supply tightens, the effects show up in freight rates, manufacturing costs, and eventually consumer prices. Governments know this. That is why the agency is pushing for faster and larger releases. The message is clear: the market needs more product on the water sooner rather than later.
Yet strategic stock releases are only a temporary bridge. They buy time. They do not fix the underlying problem of elevated risk along one of the world’s most important oil routes. If attacks continue or intensify, the physical tightness could outlast the available emergency barrels.
An Energy Ceasefire Between Russia And Ukraine
In the middle of all this Middle East noise, another headline appeared. Officials claimed that Russia and Ukraine had agreed to an immediate energy ceasefire. If it holds, the deal could ease some of the pressure on diesel and other refined products that have been affected by attacks on energy infrastructure in that theater. Stabilizing that front would be welcome news for the refined-product side of the market.
Still, the timing feels almost ironic. Just as one source of energy-related conflict might be dialing down, another is heating up. The market is left trying to weigh two very different geopolitical stories at the same time. One might take some diesel risk off the table. The other is putting crude and shipping risk back on it. Net effect so far has been higher prices, which tells you where traders are placing the heavier weight.
How Traders Are Reading The Signals
Treasury markets were closed when the latest attacks hit, so the usual bond-market verdict on risk sentiment was missing. In quieter periods, geopolitical headlines can move prices more than they would during a busy data week. This time the oil market did not wait for confirmation from other asset classes. It simply marked the risk higher.
Looking ahead, the calendar is full. Inflation data, central-bank speakers, and the start of another earnings season will all compete for attention. Yet none of those scheduled events can erase the images of tankers on fire or the statements claiming control over a critical chokepoint. Those images and statements tend to linger in traders’ minds longer than a single data print.
I have found that the most durable price moves in oil often begin with a genuine change in the physical risk environment rather than with pure financial positioning. Right now the physical risk environment has clearly deteriorated. That does not guarantee prices will keep rising every day, but it does suggest the floor under the market has moved higher.
Shipping Costs And Insurance Premiums Climb
One of the less visible but very real consequences of the recent attacks is the jump in tanker rates and war-risk insurance. When underwriters see multiple ships damaged in a short period, they reprice the risk. Higher premiums get passed through to charterers and ultimately to the landed cost of crude and products. Those extra dollars do not always show up immediately in the futures strip, yet they tighten the economics of moving oil and can discourage some voyages altogether.
Shipowners also face practical decisions. Do they continue sending vessels into the strait at the same frequency? Do they wait for clearer security guarantees? Do they demand higher day rates to compensate for the elevated danger to crews and vessels? Each of those choices reduces the effective capacity of the global tanker fleet, even if the physical number of ships remains unchanged.
- Higher insurance costs raise the all-in expense of every voyage
- Crew reluctance can lead to longer delays or canceled sailings
- Rerouting around higher-risk zones adds days and fuel burn
- Charterers may prefer longer-haul alternatives when available
All of these factors act like a quiet reduction in supply. The barrels are still in the ground or in storage, but getting them to where they need to go becomes more expensive and less reliable.
What History Suggests About These Episodes
Past periods of elevated tension in the same region offer some guidance, though never a perfect map. Markets usually overreact to the first few incidents, then settle into a higher risk-premium range if the attacks continue at a moderate pace. Only when a major facility is damaged or a prolonged closure of the strait looks realistic do prices enter a true panic phase. We are not there yet. We are, however, well past the point where the market can ignore the headlines.
The difference this time is the backdrop. Global spare capacity is limited. Diesel inventories in several key regions are not comfortable. Refinery margins have been volatile. In that environment, even a series of smaller disruptions can have a larger cumulative impact than the same events would have had a few years ago.
Perhaps the most interesting aspect is how quickly the market has begun to price a more persistent risk rather than a temporary scare. That shift in psychology can be self-reinforcing. Once enough participants believe the higher risk is here to stay, they adjust inventories, hedges, and trading strategies accordingly. Those adjustments themselves support prices.
Broader Implications For Energy Security
Energy security is no longer an abstract policy phrase. It is showing up in the daily decisions of refiners, traders, and governments. When a critical waterway faces repeated threats, countries that depend on seaborne crude start looking harder at alternative sources, strategic stocks, and domestic production. Those longer-term adjustments take time, yet the process begins the moment the risk becomes visible and sustained.
For consuming nations the message is straightforward. Diversifying supply routes and maintaining adequate emergency stocks is no longer optional. For producing nations in the region the challenge is different. They must balance the desire to project strength with the economic reality that prolonged disruption eventually hurts their own export revenues and customer relationships.
In the short run the market will keep reacting to every new report of a damaged vessel or a closed airport. In the medium run the focus will shift to how much of the elevated risk premium becomes permanent and how quickly additional supply from other regions can offset any lost or delayed barrels from the Gulf.
Looking At The Days Ahead
This week brings a full slate of economic data and corporate earnings. Those events will move markets. Yet the underlying story in oil remains the rise in physical and geopolitical risk. As long as tankers keep getting hit and major airports remain under threat, the price of crude will carry a higher floor than it did before this latest escalation.
Traders will watch three things especially closely. First, whether the pace of attacks slows or continues. Second, how quickly emergency diesel stocks actually reach the market. Third, whether any major producer or consumer announces concrete steps to secure shipping lanes or redirect flows. Progress on any of those fronts could ease the immediate pressure. Further incidents would do the opposite.
I keep coming back to a simple observation. Oil markets can absorb a surprising amount of noise when the physical balance is comfortable. They become far less forgiving when the balance is already tight. Right now the balance is tight, the noise is loud, and the path of least resistance for prices remains higher until something material changes in the risk picture.
The coming days will tell us whether this latest surge in attacks marks a temporary spike in tension or the beginning of a more prolonged period of elevated supply risk. Either way, the market has already begun to adjust. Those adjustments are visible in the price of crude, the cost of shipping, and the growing calls for faster stock releases. For anyone who follows energy, the message is clear. The Middle East is once again setting the tone, and the rest of the market is listening closely.
The situation remains fluid. New reports can emerge at any hour. What feels manageable on one day can look very different the next. That is the nature of markets that sit at the intersection of geopolitics and physical supply. Staying informed and staying flexible will matter more than usual in the weeks ahead.
Ultimately the price of oil is a continuous referendum on how much risk the world is willing to tolerate in its energy supply chains. This weekend’s events raised that risk, and the market voted with higher prices. Whether the vote stands or gets revised will depend on what happens next in the waterways and cities that have suddenly returned to the center of the energy conversation.



