
Have you ever watched a market that everyone expected to shine suddenly go dark? That is exactly what happened in China during the so-called Golden September, the traditional peak season for buying cars. Instead of the usual rush of customers filling showrooms, retail sales of passenger vehicles crashed by a stunning 28 percent compared with the same month last year. The numbers landed like a cold shower on an industry already wrestling with soft demand at home.
I found myself staring at the latest figures from the industry association and thinking the same thing many dealers must have felt: this was supposed to be the strong month. Golden September and Silver October are legendary for a reason. Families get bonuses, weather cools just enough to make test drives pleasant, and the calendar builds natural urgency before year-end. Yet this time the magic simply failed to appear.
Why the Expected Peak Season Never Arrived
Retail sales settled at 1.62 million units. That marks the twelfth straight month of year-on-year decline. A modest 5 percent rise from August offered only thin comfort. The drop was broad and deep. Even the usually resilient new-energy vehicles, which include pure electrics and plug-in hybrids, fell 17 percent to 1.08 million units. Those same new-energy models still captured an impressive 67 percent of total passenger-car sales, proving how far the shift away from traditional fuel vehicles has already gone.
High oil prices kept pushing the oil-to-electric transition faster than many expected. Fuel cars contracted at an accelerated pace while new-energy models showed relative resilience. Still, the overall volume stayed under heavy pressure. Dealers reported that the classic peak-season effect felt noticeably weaker than in previous years. Inventory stayed low because most retailers grew cautious about ordering fresh stock. Confidence among dealers sank, and survival pressure climbed.
The Structural Shift Toward New Energy
One of the clearest stories inside the numbers is the extreme structural differentiation. Fuel vehicles are shrinking fast. New-energy vehicles continue to lead. That leadership, however, is no longer enough to lift the entire market. The association itself noted that high oil prices keep accelerating the substitution process. Drivers who once hesitated now look at monthly fuel costs and decide the switch makes sense.
Yet even this strong segment felt the chill. Chip and memory prices have risen sharply, driven by artificial-intelligence demand. Tight supply of certain components has slowed the rate of increase in new-energy sales. The combination of higher component costs and weaker consumer appetite created a perfect storm for September.
Overall sales volume was under significant year-on-year pressure, with limited month-on-month recovery; structural differentiation was amplified to the extreme, with accelerated contraction of fuel vehicles and resilient leadership of new energy vehicles becoming the main market theme.
That statement captures the moment perfectly. The market is not simply soft. It is transforming at high speed while total demand contracts.
Exports Step In as the Unexpected Lifeline
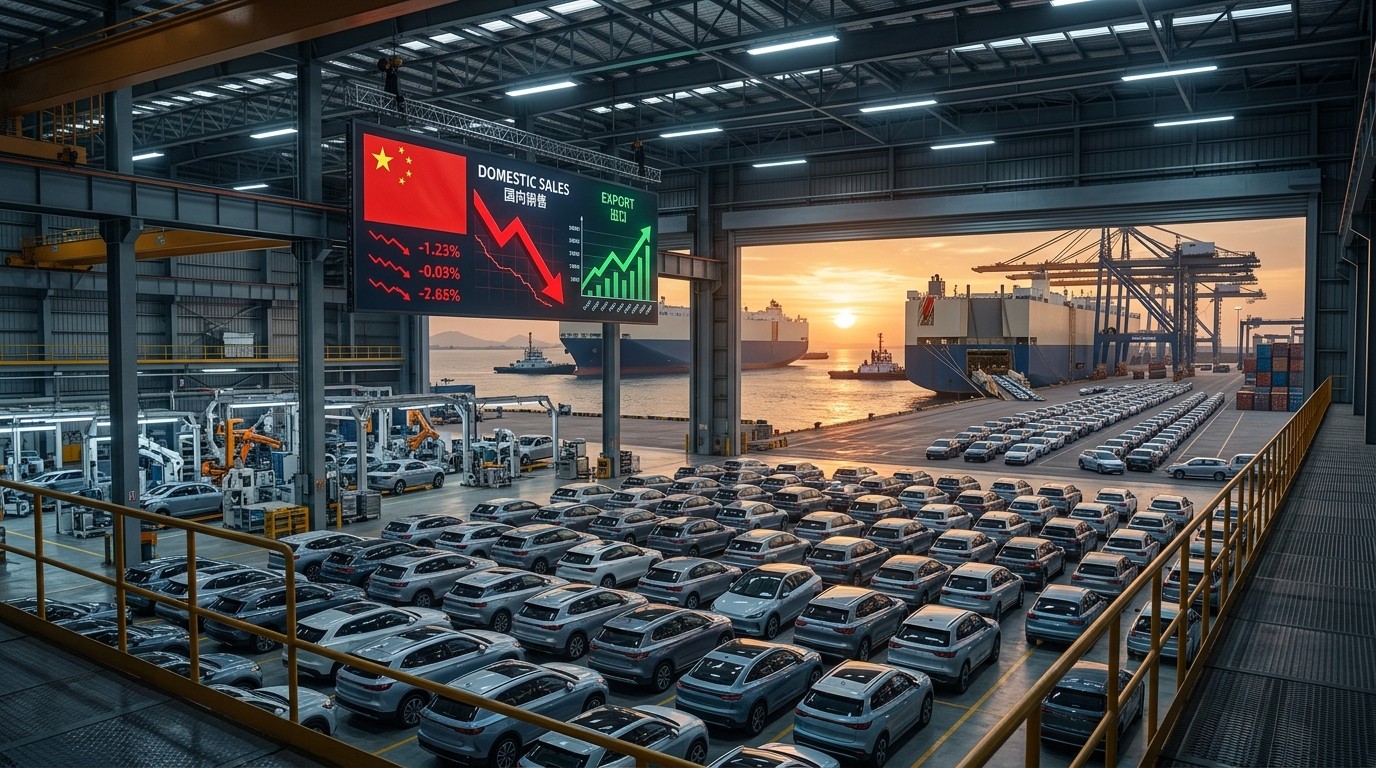
When domestic buyers stepped back, Chinese manufacturers turned their attention overseas with remarkable speed. Overseas passenger-vehicle shipments, including knock-down kits, surged 73.7 percent to 917,000 units. Exports now account for 36 percent of manufacturers’ total sales, up from just 19 percent a year earlier. At some companies the share has already climbed past 50 percent. A growing number of makers are approaching 70 percent export dependence.
These vehicles are competitive on price and increasingly sophisticated on technology. They are flooding markets across Asia, the Middle East, Latin America, and parts of Europe. The sudden rise has turned exports into the single most important buffer against weak home demand. Without that overseas demand, the production lines would have faced far deeper cuts.
In my view, the speed of this pivot is both impressive and slightly unsettling. An industry that once focused almost entirely on the world’s largest domestic market now leans heavily on foreign buyers. That dependence creates new risks as well as new opportunities.
Clouds Gathering Over the Export Boom
The export success story already faces questions. Early Monday reports raised the possibility that Europe might cap Chinese hybrid vehicle imports at around 350,000 units per year. Pure electric models face their own set of trade tensions. The United States market remains effectively closed to these vehicles. Any tightening of rules in major destinations could quickly reduce the cushion that exports currently provide.
Manufacturers are aware of the risk. Diversifying destinations and localizing production in key markets have become urgent priorities. Still, the current numbers show how heavily the industry is relying on the export channel right now.
What Dealers and Industry Insiders Are Saying
Most dealers described the Golden September effect as significantly weaker than in previous years. They remained cautious about stocking new cars. Industry inventory stayed low. Survival pressure is real for many smaller outlets. Yet the association struck a more optimistic note on the longer-term outlook. It described the current downturn as a temporary phenomenon caused by short-term policy disruptions and a high base from last year, rather than a sign that car ownership fundamentals have peaked.
That distinction matters. China still has room for higher vehicle ownership rates, especially in lower-tier cities and rural areas. The question is timing. When will consumer confidence return strongly enough to restart the domestic engine?
Breaking Down the Key Numbers
Looking closer at the data helps clarify the picture.
- Retail passenger-vehicle sales: 1.62 million units, down 28 percent year-on-year
- Month-on-month change: up 5 percent from August
- New-energy vehicle retail sales: 1.08 million units, down 17 percent
- New-energy share of total sales: 67 percent
- Overseas shipments including knock-down kits: 917,000 units, up 73.7 percent
- Export share of manufacturer sales: 36 percent, versus 19 percent a year ago
These figures tell a dual story. Domestic retail is under severe pressure. Export volumes are booming. The gap between the two has never been wider.
The Role of High Oil Prices and Policy Shifts
High oil prices continue to act as a powerful accelerator of the shift from fuel to electric. Every time drivers fill up and feel the cost, the mathematical case for switching grows stronger. At the same time, short-term policy changes have created temporary disruptions. Subsidy adjustments, local incentive programs, and regulatory updates all influence the precise timing of purchases.
The high base effect from last year also plays a part. When previous periods delivered strong numbers, year-on-year comparisons naturally look weaker. Combining that high base with policy noise and cautious consumer spending produced the sharp September drop.
Chip Supply and Cost Pressures
Another quieter but important factor is the surge in memory and chip prices linked to artificial-intelligence demand. Tight supply of certain semiconductors has slowed the production ramp of some new-energy models. Higher component costs also squeeze margins at a moment when manufacturers need every advantage they can get. The industry is learning that the global technology boom can create unexpected bottlenecks in unexpected places.
How Manufacturers Are Adapting
Faced with weak domestic retail, companies have accelerated their export strategies. Some are already deriving more than half their volume from overseas markets. Others are pushing toward 70 percent. That level of dependence is unusual for an industry that grew up serving a massive home market. It forces changes in product development, logistics, and after-sales support. Vehicles designed primarily for Chinese roads and tastes must now satisfy different regulations and consumer preferences abroad.
I have noticed that the most successful exporters tend to offer strong value propositions: modern technology at competitive prices. That combination travels well. Whether it can continue to travel freely under rising trade barriers is the open question.
Looking Ahead to Silver October and Beyond
October traditionally carries the Silver October label. Many hope it will deliver a rebound. Early signals, however, suggest caution remains the dominant mood among dealers. If the Golden September effect already proved weaker than expected, Silver October may follow a similar pattern unless consumer confidence improves quickly.
Longer term, the industry association believes the fundamentals of car ownership have not peaked. Rising incomes in inland regions, infrastructure improvements, and continued technological progress in new-energy vehicles should eventually support higher sales. The current soft patch is viewed as temporary rather than structural.
Still, the path back to stronger domestic growth will require more than hope. Clearer policy signals, stable component costs, and a recovery in household spending power will all matter.
The Bigger Picture for Global Auto Markets
What happens in China rarely stays in China. The world’s largest auto market influences global supply chains, commodity prices, and competitive dynamics everywhere. When Chinese manufacturers export more aggressively, competitors in other regions feel the pressure. When Chinese domestic demand weakens, global suppliers of parts and materials feel it too.
The current pattern—weak home sales, strong exports—creates both opportunities and tensions. Importing countries gain access to affordable, technologically advanced vehicles. Domestic producers in those countries face intensified competition. Trade policy debates intensify. The outcome of those debates will shape the next chapter of the industry.
Personal Reflections on Market Resilience
Watching this market evolve, I keep returning to one observation. Chinese auto manufacturers have shown remarkable agility. When domestic demand softened, they did not simply wait. They pivoted hard toward exports and delivered results within months. That speed of adaptation is rare in an industry known for long product cycles and heavy capital investment.
At the same time, heavy reliance on any single channel carries risk. Whether that channel is the domestic market or the export market, concentration creates vulnerability. The healthiest long-term path will involve balanced growth on both fronts.
Perhaps the most interesting aspect is how quickly the new-energy transition continues even while overall volumes shrink. The 67 percent share achieved by electric and plug-in hybrid models in a weak month shows that the technology shift has its own momentum. High fuel prices help, but consumer preference and model availability now play large roles as well.
Key Takeaways for Industry Watchers
Several points stand out clearly from the latest data.
- Domestic retail demand remains under significant pressure even during the traditional peak season.
- New-energy vehicles continue to gain share despite softer absolute sales.
- Exports have become a critical buffer, rising dramatically in both volume and share of total sales.
- Potential trade restrictions in major markets introduce fresh uncertainty for the export strategy.
- Component cost inflation linked to artificial-intelligence demand is adding another layer of complexity.
- Dealers remain cautious, keeping inventories low and confidence subdued.
- Industry leaders still view the current soft period as temporary rather than a permanent peak in ownership rates.
These takeaways paint a market in transition. Volume growth has stalled at home. Structural change continues at high speed. External demand is filling the gap for now.
What Could Turn the Tide
Several developments could help restore stronger domestic sales. A clear and stable set of purchase incentives would reduce hesitation among potential buyers. Easing of chip and memory price pressures would support production of popular models. Broader recovery in consumer confidence, tied to employment and income trends, would encourage larger household purchases. Finally, continued improvement in charging infrastructure and battery technology would remove remaining barriers for first-time new-energy buyers.
None of these factors will shift overnight. Yet the combination of them could gradually rebuild the domestic momentum that has been missing.
Final Thoughts on a Market at a Crossroads
China’s Golden September delivered a clear message. The old seasonal patterns can no longer be taken for granted. Domestic demand is soft. The new-energy transition is advancing regardless. Exports have stepped into the role of primary growth engine for many manufacturers. That configuration is new, powerful, and still fragile.
The coming months will reveal whether the export surge can be sustained and whether domestic buyers will return in meaningful numbers. For now, the industry is navigating one of its most complex periods in recent years. Volume pressure at home meets opportunity abroad. Technology leadership meets trade friction. Short-term caution meets longer-term belief in the market’s underlying potential.
In my experience, markets that face this kind of dual pressure often emerge leaner and more globally competitive. The question is how much turbulence they must endure along the way. September’s 28 percent drop was a sharp reminder that the road ahead will not be smooth. Yet the same data also showed an industry capable of rapid adjustment. That combination of challenge and adaptability may ultimately define the next phase of China’s auto story.
The numbers are out. The season that was supposed to shine turned dim. Now the real test begins: whether the lifeline of exports can hold long enough for domestic demand to recover, and whether the structural shift toward new energy can continue delivering progress even in a weaker volume environment. Those answers will shape not only Chinese manufacturers but the broader global automotive landscape for years to come.