
Every time I pull up to the pump these days I feel that familiar little sting. Gas prices keep dancing higher and lower, but they never seem to settle in the comfort zone. So when I first heard about a checking account that could hand me back as much as one hundred dollars every single month just for buying fuel, I stopped scrolling. That kind of money is not pocket change. It is the difference between stressing over the tank and treating the fill-up like a small refund. Let me walk you through exactly how this works, what the fine print really says, and whether it makes sense for your own routine.
How the Citizens Fuel Bonus Actually Puts Cash Back in Your Account
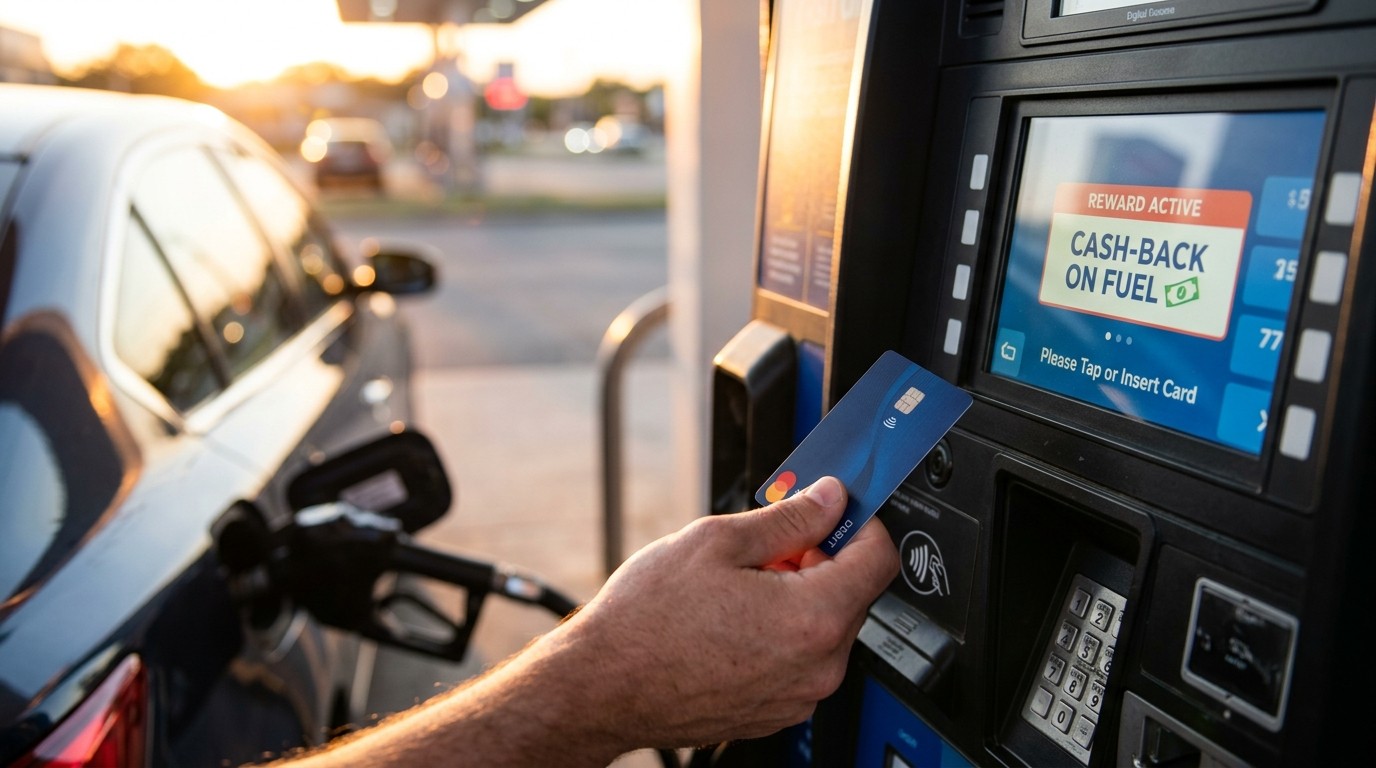
The offer is straightforward on the surface. Open a new eligible checking account by the middle of November 2026, start receiving qualifying direct deposits, and then simply use the debit card that comes with the account every time you buy gas. The bank looks at the total you spend on fuel each month and matches it, up to a clear monthly ceiling. That ceiling depends on which account you choose.
With the more basic One Deposit Checking or the business version, the match tops out at fifty dollars a month. Choose the higher-tier Quest or Private Client checking and the ceiling doubles to one hundred dollars. Do the math and you are looking at six hundred or even twelve hundred dollars over a full year if you hit the maximum every month. I have seen people leave that kind of money on the table simply because they never connected the dots between their existing fuel spending and a new debit card.
Which Checking Accounts Qualify for the Higher Rewards
Not every account at the bank unlocks the full bonus. The entry-level One Deposit Checking is the easiest door to walk through. There is no minimum opening deposit, and the nine-dollar-ninety-nine monthly fee disappears as long as you make at least one deposit during the statement period. That single deposit can be almost anything, which makes the account surprisingly flexible for people who do not want to move their entire paycheck right away.
If you already run a small business or simply prefer a business-style account, the Clearly Better Business Checking sits in the same fifty-dollar tier. For the full one-hundred-dollar monthly match you need to step up to Quest or Private Client Checking. These accounts usually come with higher relationship requirements, but once you clear them the fuel bonus becomes twice as generous. In my view the jump is worth considering only if you already keep larger balances or want the extra relationship perks that travel with those tiers.
How the Monthly Bonus Is Calculated
Here is where a lot of people get pleasantly surprised. The bank does not hand you a flat fifty or one hundred dollars simply for opening the account. Instead it looks at the actual dollars you swipe for fuel and matches them, dollar for dollar, until you hit the monthly ceiling. Spend thirty-five dollars on gas and you receive thirty-five dollars back. Spend one hundred thirty dollars and you receive the full fifty or one hundred, depending on your tier. Anything above the ceiling is simply regular spending with no extra match.
The bonus itself lands on the last day of the following month. That lag means you need a little patience, but once the rhythm starts it feels almost automatic. I like the structure because it rewards real usage rather than forcing you to chase artificial spend requirements that have nothing to do with your life.
What Counts as a Qualifying Fuel Purchase
Merchant category codes decide everything. The bank does not inspect the itemized receipt. It simply sees the code the gas station or convenience store submits with the transaction. Most of the big names you already visit carry the right code, so everyday fill-ups at the usual spots should clear without drama. The odd case that sometimes trips people up is when a station rings up snacks or car washes under a different code. In those moments the fuel portion may still qualify while the extras do not, or vice versa. The safest habit is to keep the fuel purchase clean and separate when possible.
One practical tip I have started following: glance at the transaction description in the mobile app a day or two after the fill-up. If it shows the expected category you can relax. If something looks off you still have time to adjust your next purchase before the monthly total locks in.
Direct Deposit Rules You Cannot Ignore
The fuel match only unlocks once the account receives at least one thousand dollars in qualifying direct deposits. Paychecks, Social Security, pensions, and other regular income streams count. Peer-to-peer transfers, even the ones that look automatic, do not. That distinction matters. I have watched friends miss an entire month of bonuses because they moved money through a payment app instead of setting up true direct deposit from their employer or benefits provider.
The good news is that once the first qualifying deposit lands, the account stays eligible for future months as long as it remains open and in good standing. You do not have to re-qualify from scratch every thirty days. Still, it pays to keep an eye on the deposit total, especially if your income is irregular.
A Quiet Savings Bonus Running Alongside the Fuel Offer
While the debit-card gas reward grabs the headlines, the same bank is also running a separate monthly bonus for new savings accounts. Deposit at least fifteen thousand dollars of fresh money within ten business days and then maintain the balance. Between fifteen thousand and just under forty thousand you earn fifty dollars every month. Cross the forty-thousand mark and the monthly credit jumps to one hundred fifty dollars. Over a year that becomes six hundred or eighteen hundred dollars simply for parking cash you may already have sitting somewhere else.
Combine the highest fuel tier with the highest savings tier and the theoretical annual total climbs toward three thousand dollars. Of course real life rarely lets anyone max both offers every single month, yet even hitting half that number still feels like free money most of us would happily accept.
Pros and Cons Worth Weighing Before You Apply
Every bank bonus carries trade-offs. On the positive side you receive cash that can chip away at debt, pad an emergency fund, or simply soften the blow of higher living costs. The fuel offer in particular rewards behavior you are already doing. You do not have to invent new spending categories or stretch your budget just to unlock the money.
The drawbacks are familiar to anyone who has chased account bonuses before. The checking account itself earns zero interest. Out-of-network ATM fees are not reimbursed on the basic tier. Overdraft charges still exist, though they are capped. And like almost every bank bonus, the money you receive is taxable income. Come tax season you will need to set a little aside or risk a surprise.
- Monthly cash that arrives automatically once you qualify
- No forced minimum balance on the entry-level checking account
- Ability to combine fuel and savings bonuses for larger totals
- Zero interest on the checking side and limited ATM fee help
- Taxable nature of every bonus dollar
- Need to meet direct-deposit thresholds consistently
In my experience the people who benefit most already spend enough on fuel to approach the monthly ceiling and can move a direct deposit without major hassle. If your gas spending is minimal or your income is too irregular to hit the deposit floor, the offer loses some shine.
Practical Steps to Claim the Full Monthly Match
- Decide which checking tier fits your current balances and relationship needs.
- Open the account online or in a branch before the mid-November cutoff.
- Set up at least one thousand dollars in true direct deposits as soon as possible.
- Begin using the new debit card for every fuel purchase.
- Track the monthly total in the mobile app so you know when you have hit the ceiling.
- Keep the account open and in good standing so future months continue to qualify.
Those six steps sound simple, and they largely are. The only real friction tends to appear when people delay the direct-deposit setup or mix personal and business spending in ways that confuse the merchant codes. A little planning removes most of that friction.
Who Should Strongly Consider This Offer Right Now
Commuters who drive more than average, families with multiple vehicles, and anyone already shopping for a new checking account stand to gain the most. If you currently keep your main deposit relationship at a bank that charges high fees or offers weak digital tools, switching for a temporary bonus can still make sense provided the everyday features meet your needs.
I am less enthusiastic about opening an account solely for the bonus if you already love your current bank and would only use the new debit card for the occasional fill-up. In that scenario the administrative overhead may outweigh the cash. But if your fuel spend is steady and you can meet the deposit rule without rearranging your entire financial life, the numbers become hard to ignore.
Common Questions People Ask Before Signing Up
Does the bank operate in every state? Online account opening is available nationwide as long as you meet basic eligibility. Physical branches are concentrated in a smaller number of states, so branch lovers should check coverage first.
What if I miss a month of the bonus? Eligibility resets each month. Skip the direct-deposit threshold or the fuel spend one month and you simply forfeit that month’s match. You can still qualify again the following month without restarting the entire process.
Is it wise to hold multiple bank accounts? Plenty of people do exactly that. One account can handle the fuel rewards while another holds the bulk of savings or bill payments. The key is staying organized so fees and forgotten balances do not erase the gains.
The smartest bank bonuses are the ones that reward money you were already going to spend. When the reward lines up with real life instead of forcing artificial behavior, the value sticks around longer.
How This Offer Fits Into a Larger Money Strategy
Think of the fuel match as a temporary high-interest side hustle attached to everyday spending. While the checking account itself pays no interest, the effective return on the fuel dollars you would have spent anyway can be enormous. Pair that with the separate savings bonus and you create a short-term cash-flow boost that can fund other goals: an emergency cushion, a debt payment, or even the start of a brokerage account.
I have found that the people who extract the most value treat the bonus as a bridge rather than a permanent feature. They use the extra cash to strengthen their overall position, then reassess once the promotional window ends. That mindset keeps the relationship with the bank healthy and prevents the common trap of collecting accounts that later become neglected.
Final Thoughts Before the Deadline Arrives
Gas prices are unlikely to become dramatically cheaper overnight. Any tool that softens the impact without requiring major lifestyle changes deserves a close look. The Citizens debit-card fuel bonus is one of those tools, provided you open the right account in time, meet the direct-deposit floor, and actually use the card at the pump.
Take a quiet evening this week, pull up your last few months of fuel receipts, and run the numbers. If the potential match looks meaningful, the next step is simply deciding which account tier fits and getting the paperwork started. A few minutes of setup now can turn the next twelve months of fill-ups into a surprisingly pleasant refund instead of another monthly expense.
That is the kind of quiet financial win most of us can use right now. The offer will not last forever, and the calendar is already moving toward the November cutoff. Whether you chase the full one-hundred-dollar tier or simply test the fifty-dollar version, the important part is making an intentional choice instead of letting another month of higher gas prices pass without a plan.
I have watched enough promotional offers come and go to know that the best ones feel almost effortless once the initial setup is complete. This fuel match has that potential. Open the account, point a direct deposit at it, swipe the card when you fill the tank, and let the monthly credits accumulate. Over time those credits add up to real money that can be redirected toward whatever matters most in your own budget.
And if the numbers still feel borderline after you run them, there is no harm in waiting. Banking promotions appear regularly. The difference with this one is the direct link to a universal expense that almost every driver already faces. That link is what makes the offer worth the extra attention right now.