
Have you ever watched two neighbors handle the same problem in completely opposite ways and then wondered which one ends up better off? That is exactly what is unfolding right now between Europe and Canada when it comes to Chinese vehicle imports. One side is quietly building walls with quotas and steeper duties. The other held the line on sovereignty and is now staring at rising unemployment. The numbers are already telling a clear story, and the ripple effects reach far beyond car lots.
Europe’s Quiet Turn Toward Protection
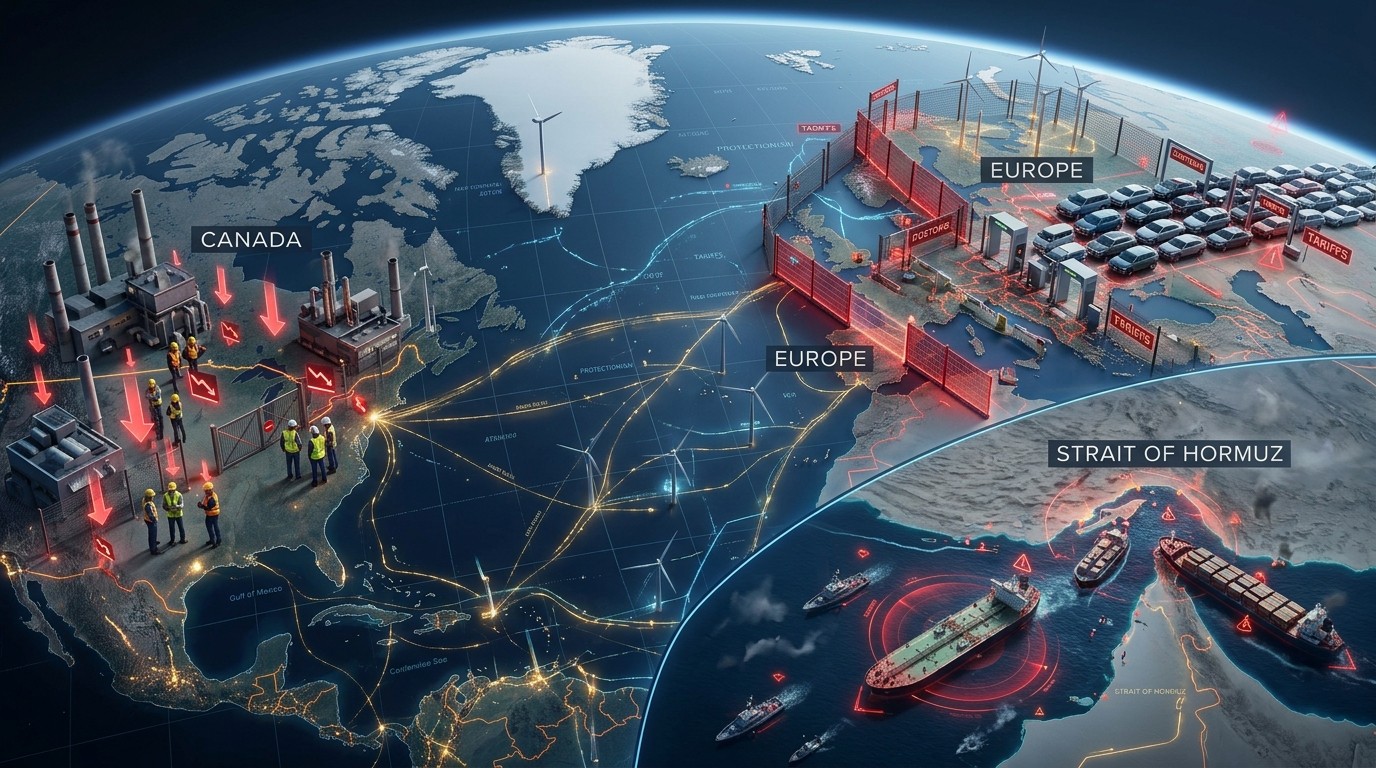
European equity markets closed last week on a firm note. The CAC40 climbed nearly one percent on Friday alone, lifted in part by news that the European Union will place a 350,000-unit annual quota on Chinese hybrid and plug-in hybrid vehicles. Once that ceiling is hit, much steeper tariffs kick in. Chinese shipments of these cars into Europe had been on track to jump from roughly 300,000 units to an estimated 800,000. Officials expect the new safeguard to cut those imports by more than half.
What stands out is how the measure was crafted. It was negotiated bilaterally, which lowers the chance of immediate retaliation, and it does not require proof of dumping or market distortion to take effect. That flexibility matters. European manufacturers have watched Chinese producers scale up at a speed few domestic plants can match. The quota gives breathing room without an all-out trade war declaration.
I’ve found that these kinds of sectoral moves often signal a broader change in mindset. For years the default European posture leaned toward open markets. Now the conversation has shifted. Captains of industry in chemicals and other heavy sectors are already asking for similar treatment. At some point the Commission may decide that plugging individual holes is less efficient than a wider net of tariffs. The United States has already traveled that road.
The British Angle And Political Undercurrents
Across the Channel the pressure is different but related. Reports suggest Germany would like Britain to raise its own tariffs on Chinese electric vehicles in exchange for smoother access to the European market. The lingering sense on the continent is that the United Kingdom should not enjoy selective benefits after choosing to leave the larger club. In France that sentiment carries extra weight, sharpened by history and by an approaching presidential contest where populist voices are expected to perform strongly.
The proposed quid pro quo feels familiar. It echoes the arrangement the United States offered Canada: align on a common external tariff toward China in return for the most favorable market access terms available. In Canada’s case the concern was straightforward. Officials wanted to close off any back-door route for Chinese goods entering the American market through northern ports. For Britain the calculus is more about political signaling. The fact that the steering wheel sits on the opposite side already limits large-scale re-export of Chinese hybrids into Europe.
Canada’s Costly Choice
Canada chose a different path. It declined the common-tariff arrangement in order to keep full control over its own trade decisions. That decision carried a price. Canadian exporters have traditionally shipped about two-thirds of their products into the United States. When market access becomes less certain, the domestic economy feels it quickly.
Employment data released last week showed the Canadian economy shed 68,300 jobs in September after losing 41,700 the month before. The unemployment rate edged up from 6.4 percent to 6.5 percent even as workforce participation declined. The situation would likely look worse without elevated demand for potash and energy products linked to conflicts in the Middle East and Eastern Europe. Those bright spots cannot fully offset weakness elsewhere.
In my view the Canadian experience illustrates a hard truth about modern trade. Sovereignty sounds appealing until the largest customer starts writing new rules. The short-term pain shows up in payroll numbers and in boardrooms that suddenly face thinner order books. Whether the long-term gain in policy independence proves worth it remains an open question, but the immediate data is unambiguous.
The Deeper Structural Problem
Europe’s new vehicle measures address a visible symptom. They do not touch the underlying imbalance. Chinese industrial capacity continues to expand even while domestic demand stays relatively weak. The result is persistent export pressure across multiple sectors. Specialized industrial machinery, general industrial equipment, and road vehicles have all seen Chinese producers gain share at the expense of traditional European leaders. Data centers and high-tech hardware look like the next frontier.
Policy in Beijing still prioritizes investment and production over a decisive shift toward household consumption. Ideological preferences and fiscal realities both play a role. Public debt has climbed rapidly and the fiscal balance is already stretched. Raising taxes on wealthy residents who hold assets offshore may help the budget, yet it does little to boost broad-based consumer spending. Any serious move toward stronger social programs would require resources that are currently directed toward maintaining industrial momentum and competing in advanced technology.
The huge investments in artificial intelligence and other high-tech fields, largely financed by private capital in the United States, have pushed China into an investment contest that leaves limited room for social spending.
Some observers compare the dynamic to the military spending race of earlier decades. The open question is whether the financial superiority that once decided such contests still exists in the same form. Private capital flows, technological leadership, and the ability to absorb short-term costs all matter. The answer will shape not only trade patterns but the broader balance of economic influence.
Energy Markets Add Another Layer Of Uncertainty
While trade policy dominated one set of headlines, energy markets were being pushed around by geopolitics. An announced energy ceasefire between Russia and Ukraine was broken almost immediately by strikes on power infrastructure in major cities. Earlier comments had suggested that continued attacks on certain energy facilities could affect intelligence sharing. At the same time, a separate arrangement involving Russian diesel shipments received mixed reactions, with some describing it as helpful for lowering fuel costs and others viewing it as problematic.
In the Middle East the situation remained tense. Strikes hit a major international airport, causing casualties and forcing operational suspensions. Concurrent reports described incidents involving shipping in the Strait of Hormuz and nearby waters. One vessel was immobilized under a blockade enforcement action. Despite the noise, benchmark crude prices were trading lower at the start of the new week, a reminder that markets often look through short-term disruptions when supply expectations remain adequate.
These energy developments matter for Canada in particular. Elevated demand for its resource exports has provided a partial cushion against trade-related job losses. Any sustained disruption or price spike could cut both ways: higher revenues for producers, higher costs for consumers and manufacturers. The interplay between trade friction and energy volatility is worth watching closely.
What The Shift Toward Tariffs Really Means
Perhaps the most interesting aspect is how quickly the Overton window on protectionism has moved. A few years ago large-scale tariffs were treated as relics of a less enlightened era. Today they are discussed as practical tools for managing overcapacity and preserving strategic industries. Europe’s vehicle quota is carefully designed, limited in scope, and negotiated rather than imposed unilaterally. That may make it more durable and less likely to trigger an escalating spiral.
Still, the logic is spreading. Once one sector receives relief, others line up. Chemicals producers have already begun making the case. If the pattern continues, the European approach could evolve from targeted safeguards into something closer to the broader tariff framework already in place elsewhere. The risk is that temporary measures become permanent features of the landscape.
- Targeted quotas can buy time for domestic industry without immediate retaliation
- Broader tariff regimes risk higher costs for consumers and downstream manufacturers
- Alignment on external tariffs can become a condition of preferential market access
- Refusal to align preserves policy freedom but can reduce commercial opportunity
- Energy and resource demand can temporarily mask underlying trade weakness
Canada’s recent employment figures serve as a live case study. Job losses accumulated over two consecutive months even as certain commodity exports remained firm. The unemployment rate rose despite a smaller labor force. Those numbers concentrate the mind. Policymakers who prioritize sovereignty above all else must still answer to households that need steady work.
Looking Ahead: Industry By Industry Pressure
Chinese producers have already overtaken traditional leaders in several categories of industrial machinery. Road vehicle exports are approaching the same milestone. The pattern is unlikely to stop at current product lines. High-tech manufacturing, data-center equipment, and specialized components are natural next steps. Each advance increases the political pressure inside importing countries to respond.
For Europe the choice is becoming clearer. Continue with sector-specific measures that require constant negotiation and monitoring, or move toward a more comprehensive external tariff structure that simplifies enforcement. The first path preserves more of the open-market rhetoric. The second path acknowledges that large, persistent imbalances may not self-correct through market forces alone.
In Canada the debate is different. Having chosen independence over alignment, the country now faces the practical consequences in labor markets and export volumes. Future negotiations will almost certainly revisit the same trade-offs. Whether a revised arrangement emerges depends on how painful the current path becomes and how willing both sides are to revisit earlier positions.
The Human And Political Dimensions
Behind every tariff schedule and employment release sit real households and real political pressures. In Europe the rise of populist candidates in major economies adds urgency to visible action on industrial competition. In Canada the job numbers feed into a different conversation about the costs of standing apart. Neither side is operating in a vacuum. Voters notice when factories slow and when energy bills rise.
I’ve noticed that trade policy often moves faster once the pain becomes localized and measurable. Abstract arguments about comparative advantage carry less weight when specific communities lose shifts or when particular industries report sharp drops in orders. The European vehicle quota is a response to exactly that kind of concentrated pressure. Canada’s employment data may eventually produce a similar political reaction.
Energy markets add another variable that neither trade negotiators nor labor statisticians fully control. A sustained rise in fuel prices can amplify the cost of protectionist measures by raising input costs across the board. Conversely, stable or lower energy prices can cushion the impact of higher import duties. The weekend’s geopolitical events showed how quickly those prices can be influenced by distant developments.
Balancing Sovereignty And Market Access
The core tension remains unresolved. Nations want the freedom to set their own rules. They also want the largest possible markets for their goods. When those two goals collide, something has to give. Europe is experimenting with limited, negotiated barriers that still leave room for diplomacy. Canada tested a more absolute stance and is now measuring the commercial cost.
Neither approach is cost-free. Tariffs and quotas raise prices for some buyers and protect jobs for some workers. Open access can accelerate industrial hollowing in sectors where competitors enjoy structural advantages. The optimal mix depends on a country’s industrial base, its political tolerance for disruption, and the behavior of its trading partners.
What feels different this time is the scale of the capacity imbalance. When one major economy continues to expand production capacity far beyond domestic absorption, the pressure on everyone else intensifies. Temporary safeguards may evolve into longer-term features of the trading system. That possibility alone is reshaping how governments and companies plan.
Practical Implications For Markets And Policy
Equity markets registered the European news positively, especially in sectors that stand to benefit from reduced import competition. Bond yields had already eased somewhat, providing additional support. The combination of firm risk assets and contained yields suggests investors are still weighing the growth impact of protectionism against the relief it provides to specific industries.
For policymakers the lesson is more nuanced. Targeted measures that are negotiated rather than imposed can achieve meaningful volume reduction with lower escalation risk. Broader frameworks carry higher political and economic costs but may prove simpler to administer once the number of affected sectors multiplies. Canada’s recent data will be studied closely by any government considering a similar refusal of alignment offers.
Energy remains the wild card. A durable reduction in geopolitical tension would support lower fuel prices and ease cost pressures. Fresh disruptions would work in the opposite direction and could complicate the politics of trade barriers by raising the overall price level. The interplay between these forces will shape the next phase of both trade policy and market performance.
A Longer View On Industrial Competition
Step back far enough and the current episode fits a larger pattern. Industrial leadership has shifted before. What is new is the speed and the degree of state coordination behind the latest wave of capacity expansion. Traditional market mechanisms struggle when one participant prioritizes volume and technological advance over near-term profitability and domestic consumption balance.
Europe’s response is still evolving. The vehicle quota is an early, carefully calibrated step. Further measures in other sectors appear likely. Whether the endpoint is a patchwork of safeguards or a more uniform external tariff remains to be determined by political and industrial pressures that are still building.
Canada’s path will also continue to unfold. Job losses concentrate attention. Resource demand provides temporary relief. Future negotiations will test whether the preference for full policy independence can be reconciled with the commercial realities of deep integration with a much larger neighbor. The answer will matter well beyond North America.
In the end the story is less about any single quota or employment release and more about how open economies adapt when faced with sustained, large-scale overcapacity elsewhere. The tools of the past—pure free trade or pure protection—look insufficient on their own. Hybrid approaches that combine negotiation, limited barriers, and strategic alignment are emerging by necessity. Watching which of those approaches deliver the better combination of growth, employment, and resilience will occupy policymakers and markets for years to come.
The contrast between Europe’s measured embrace of tariffs and Canada’s experience after declining a similar framework offers a real-time laboratory. The data is already arriving. More will follow. For anyone tracking global markets, industrial policy, or the intersection of trade and energy, the next chapters promise to be revealing.