
I still remember the first time I heard someone casually mention that satellite networks might one day undercut the big wireless carriers on price. It sounded like science fiction then. Fast forward to today and the conversation has shifted from possibility to probability. A well-known investment research firm just moved AT&T from an outperform rating to market perform and trimmed its price target, pointing squarely at the accelerating push by SpaceX into both broadband and wireless services. The timing feels deliberate. Right after the successful deployment of the first batch of next-generation Starlink satellites, the pressure on traditional telecom operators is no longer theoretical.
Why the Rating Change Matters Right Now
The firm lowered its target to a level that still leaves modest upside from recent closing prices, yet the message is clear. Ongoing competitive pressure from newer satellite-based services is compounding other headwinds already facing the industry. Recent pricing moves by the large incumbents and the usual seasonal softness expected in the fourth quarter only add to the caution. In this environment, justifying a higher conviction rating becomes increasingly difficult, even when valuations look discounted.
What stands out to me is the language used around volatility. The analyst notes that volatility itself now seems almost inevitable for the established operators. That single observation captures the mood among many investors who have watched legacy telecom stocks lag broader markets for months. Shares of the company in question have declined more than nine percent so far this year, a performance that trails the overall market by a noticeable margin.
The Starlink Capacity Inflection Point
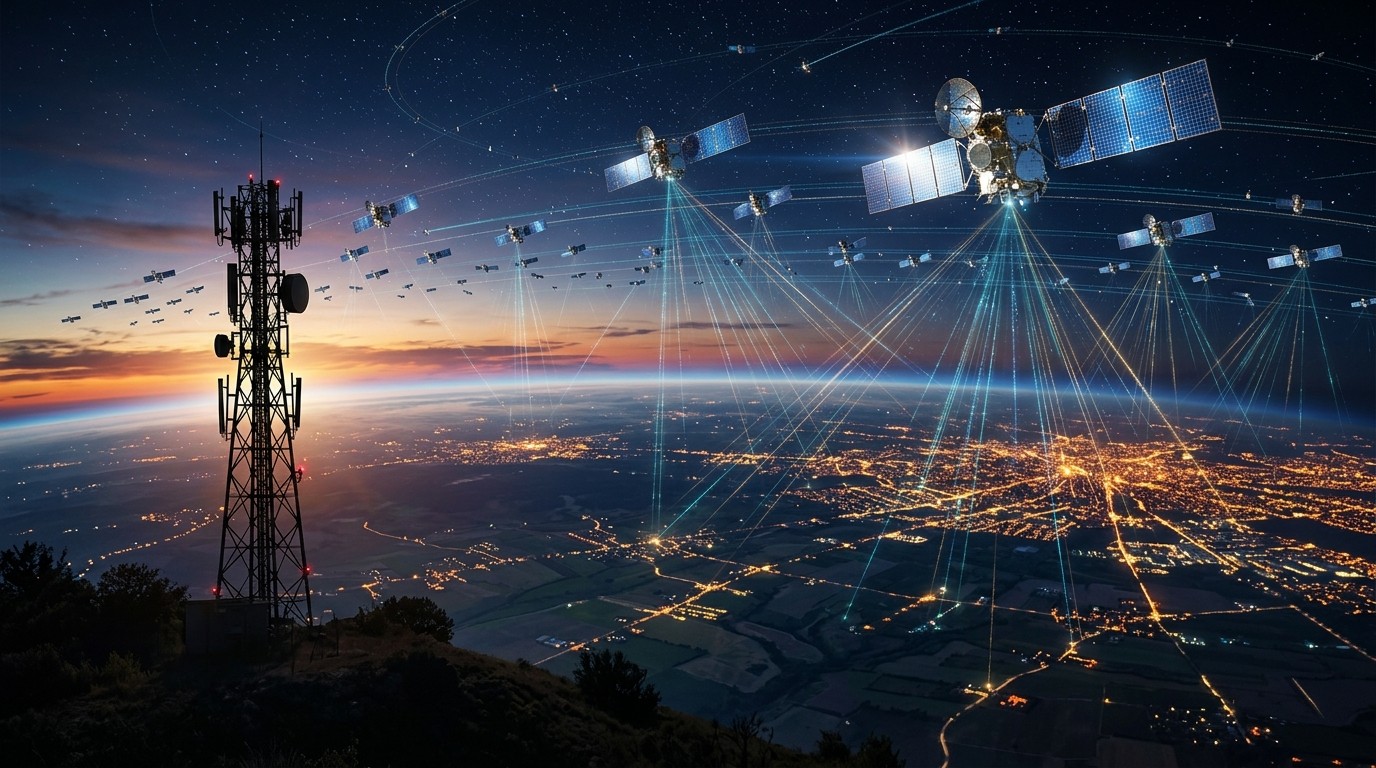
Last month’s Starship mission marked more than another successful launch. It deployed the first group of V3 satellites, an event described as the start of a meaningful capacity expansion for the wireless service. Greater capacity usually translates into more flexibility on pricing and coverage. When a relatively new entrant gains the ability to compete more aggressively, the established players face a choice: match the intensity or risk gradual share erosion.
I’ve found that capacity is often the quiet variable that reshapes competitive dynamics. Early satellite systems struggled with limited bandwidth and high latency. The newer generation appears designed to address both constraints. As the constellation scales, the service gains room to attract additional subscriptions without immediately running into hard technical ceilings. The research note expresses little doubt that the service still has a long runway for subscriber growth. The open question remains the degree of disruption it will ultimately create.
The overhang is unlikely to subside as the newer constellation scales and the service gains flexibility to compete more aggressively.
That statement lingers. Even if the absolute level of disruption stays debatable for now, the mere presence of an expanding alternative creates a prolonged investor debate. Markets dislike uncertainty almost as much as they dislike clear negative outcomes. The combination of both tends to keep multiples compressed.
Pricing Power Under Pressure
Traditional wireless operators have long relied on a relatively stable pricing environment. Customers switch less frequently than in many other industries, and the cost of building nationwide terrestrial networks creates high barriers to entry. Satellite systems change the equation by offering coverage in places where building towers remains expensive or impractical. Once capacity improves, the same systems can begin to compete more directly in denser markets as well.
Startups and newer platforms have already begun capturing incremental share in certain wireless segments. The concern is that this trend could accelerate. When that happens, the ability of large incumbents to raise prices or maintain margins becomes more constrained. Recent pricing actions by the major carriers already reflect a more competitive landscape. Adding a scaled satellite option into the mix only intensifies the dynamic.
In my experience watching these cycles, the first stage usually involves rural and underserved areas. The second stage appears when capacity allows more aggressive offers in suburban and even some urban corridors. Whether that second stage arrives quickly or gradually remains the central debate. Either way, the direction of travel is the same.
Market Reaction and Consensus Contrast
The rating change stands somewhat apart from the broader street view. A majority of the analysts covering the stock still maintain positive ratings. That divergence itself can create interesting trading dynamics. When one respected voice steps back while others remain constructive, the market often spends time testing which perspective will prove more accurate.
Meanwhile the company behind the satellite network, which completed its public listing earlier this year, has delivered solid gains over the past three months. The contrast in recent performance is hard to ignore. One side of the competitive equation is expanding capacity and market presence. The other is navigating slower growth and multiple compression.
Broader Implications for Legacy Telecom
Perhaps the most interesting aspect is how this situation fits into a longer pattern. Telecom operators have faced successive waves of technological change. Fiber displaced much of the old copper plant. Mobile broadband shifted traffic patterns and revenue models. Now satellite systems are testing the geographic and cost assumptions that underpinned the last generation of network investment.
None of this means traditional networks disappear overnight. Far from it. Dense urban areas still require the capacity and reliability that terrestrial infrastructure provides. The real issue is the gradual loss of pricing flexibility at the margin. When a portion of the customer base gains a credible alternative, the entire pricing structure comes under review.
I keep returning to the idea of an overhang. Markets can live with known competitive pressure. They struggle more with open-ended questions about how far that pressure will travel. As the satellite constellation continues to grow, those questions are likely to remain front and center for several quarters at least.
What Investors Should Watch Next
Several markers will help clarify the trajectory. First is the pace of additional satellite deployments and the resulting capacity gains. Second is any visible shift in promotional intensity or average revenue metrics at the large carriers. Third is subscriber growth reported by the satellite service itself. Together those data points will either confirm the cautious view or allow a more constructive stance to regain ground.
- Further Starship missions and V3 satellite counts
- Quarterly wireless pricing and churn trends at major operators
- Reported adoption rates for the expanding satellite service
- Any regulatory or spectrum developments that alter the competitive balance
- Capital expenditure guidance from traditional carriers responding to the new environment
Seasonality also plays a role. The fourth quarter often brings elevated promotional activity as carriers chase year-end targets. Layering additional competitive intensity on top of that seasonal pattern can amplify short-term pressure on reported metrics. Investors who understand both the cyclical and structural forces tend to navigate these periods with clearer eyes.
The Long Runway Question
The research note expresses confidence that the satellite service still has substantial room to attract new users. That assessment feels reasonable given coverage gaps that remain in many regions and the improving technical profile of the newer satellites. Growth at the margin does not automatically translate into wholesale displacement of existing networks. It does, however, create a persistent competitive reference point that was previously missing.
Think of it as a new benchmark for what connectivity can cost and how widely it can be delivered. Once that benchmark exists and keeps improving, the older models face continuous comparison. Some customers will switch. Others will simply use the existence of the alternative as leverage in their negotiations with current providers. Both outcomes chip away at the prior pricing equilibrium.
In my view the most constructive path for the established operators involves accelerating their own network upgrades while carefully managing the customer experience that pure satellite options still cannot fully match. Reliability in high-density environments, seamless handoff between cells, and deep device ecosystem integration remain areas of relative strength. Protecting those advantages while responding to price pressure is the delicate balance now required.
Valuation Context and Investor Sentiment
Even after the target reduction, the stock still trades at a discount to many historical averages and to some peers. Discounted valuations can create opportunity when the underlying concerns prove temporary. They become traps when the concerns prove structural and persistent. Distinguishing between the two requires continuous monitoring of the competitive indicators outlined earlier.
Sentiment toward the broader sector has been mixed for some time. Dividend yields remain attractive to income-focused investors, yet growth scarcity keeps growth-oriented capital elsewhere. The satellite development adds another layer to that already complex picture. Some will see the current weakness as an entry point. Others will prefer to wait for clearer evidence that the competitive threat is being successfully managed.
I’ve noticed that sectors undergoing technological transition often experience prolonged periods of multiple compression before a new equilibrium forms. The compression reflects uncertainty more than immediate earnings collapse. Once the market gains confidence in the new competitive order, multiples can stabilize or even expand again. Getting the timing right remains difficult.
Looking Beyond the Immediate Headline
It is tempting to treat every analyst rating change as a discrete event. In reality most such moves sit inside longer narratives. The narrative here involves the gradual arrival of scalable non-terrestrial networks and the adaptive response of the companies that built the previous generation of infrastructure. That story will continue unfolding through successive satellite launches, quarterly earnings reports, and shifts in consumer behavior.
One practical observation: the same firm that adjusted its view on the traditional carrier was also involved in the public listing of the satellite company. That dual perspective can sometimes produce sharper insight into the relative competitive positions. Whether that insight proves accurate over the next several years is something only time and data will confirm.
For now the message is one of caution rather than outright pessimism. Market perform ratings leave room for the stock to participate in broader market moves while signaling that company-specific upside appears more limited under current conditions. Investors who already hold the shares may choose to maintain positions for income characteristics while remaining alert to any further deterioration in competitive metrics. Those considering new positions may prefer to wait for additional confirmation that the capacity expansion is either slower or less disruptive than currently feared.
Practical Takeaways for Portfolio Construction
When a sector faces structural change, position sizing and time horizon matter more than usual. Concentrated bets on any single carrier carry elevated risk until the competitive landscape clarifies. Diversified exposure across several operators, or a broader telecommunications allocation, can reduce single-name volatility while still providing participation in any eventual recovery.
Income investors should continue monitoring free cash flow generation and dividend coverage ratios. Competitive pressure that remains modest may leave those metrics intact. Pressure that intensifies could eventually force harder choices between capital returns and network investment. The satellite capacity expansion simply raises the probability that such choices arrive sooner rather than later.
- Review current position sizes relative to overall portfolio risk tolerance
- Track upcoming satellite deployment schedules and reported capacity metrics
- Compare promotional intensity and average revenue trends across the major carriers each quarter
- Assess whether any valuation discount adequately compensates for the elevated competitive uncertainty
- Consider whether income characteristics still justify holding through a potentially prolonged period of multiple compression
None of these steps guarantee perfect timing. They do, however, create a structured framework for responding as new information arrives. Markets rarely resolve competitive debates in a single quarter. They grind through them over longer stretches, rewarding those who stay disciplined and update their views as evidence accumulates.
The Human Element Behind the Numbers
Behind every rating change and price target sits a set of assumptions about customer behavior. Will households in rural areas migrate quickly once higher-capacity satellite options become available? Will urban and suburban customers treat satellite service as a primary connection or as a backup? How price-sensitive will different segments prove once they gain real alternatives?
These questions resist clean quantitative answers in the early stages. Survey data and early adoption figures provide clues, yet the full picture emerges only after the service reaches meaningful scale. That is precisely why the overhang language appears in the research note. The uncertainty itself becomes a factor that influences valuation until clearer data arrives.
I find it useful to remember that technological transitions rarely unfold in straight lines. Early over-optimism about disruption often gives way to periods of disappointment, only to be followed later by more substantial impact once the technology matures and distribution improves. The current phase looks closer to the middle of that arc than to either extreme.
Closing Thoughts on a Shifting Landscape
The decision to step back from a more constructive rating reflects a sober assessment of the competitive environment rather than any sudden deterioration in the core business. Traditional wireless networks remain essential infrastructure. Their economics, however, are being tested by a new class of competitor that did not exist in meaningful form only a few years ago.
As the newer satellite constellation continues to expand, the debate over its ultimate impact will likely intensify rather than fade. Investors who treat the situation as a temporary distraction risk underestimating the duration of the overhang. Those who treat it as an existential threat risk overreacting to a challenge that may ultimately prove manageable. The balanced path involves acknowledging the pressure, monitoring the key indicators closely, and adjusting exposure as the evidence evolves.
In the end the market will decide how much of the competitive narrative is already priced into the shares and how much remains to be reflected. Until that verdict becomes clearer, a more neutral stance on the name appears consistent with the elevated uncertainty now surrounding the sector. The coming quarters of satellite deployments and carrier financial results will supply the next chapters in a story that is still very much being written.
What began as a technical achievement in space has become a tangible factor in equity research models and portfolio decisions on the ground. That translation from orbit to earnings estimates is what makes the current moment worth watching carefully. The capacity is growing. The pricing flexibility is increasing. And the investor conversation about traditional telecom has gained a new and persistent reference point that will not disappear anytime soon.