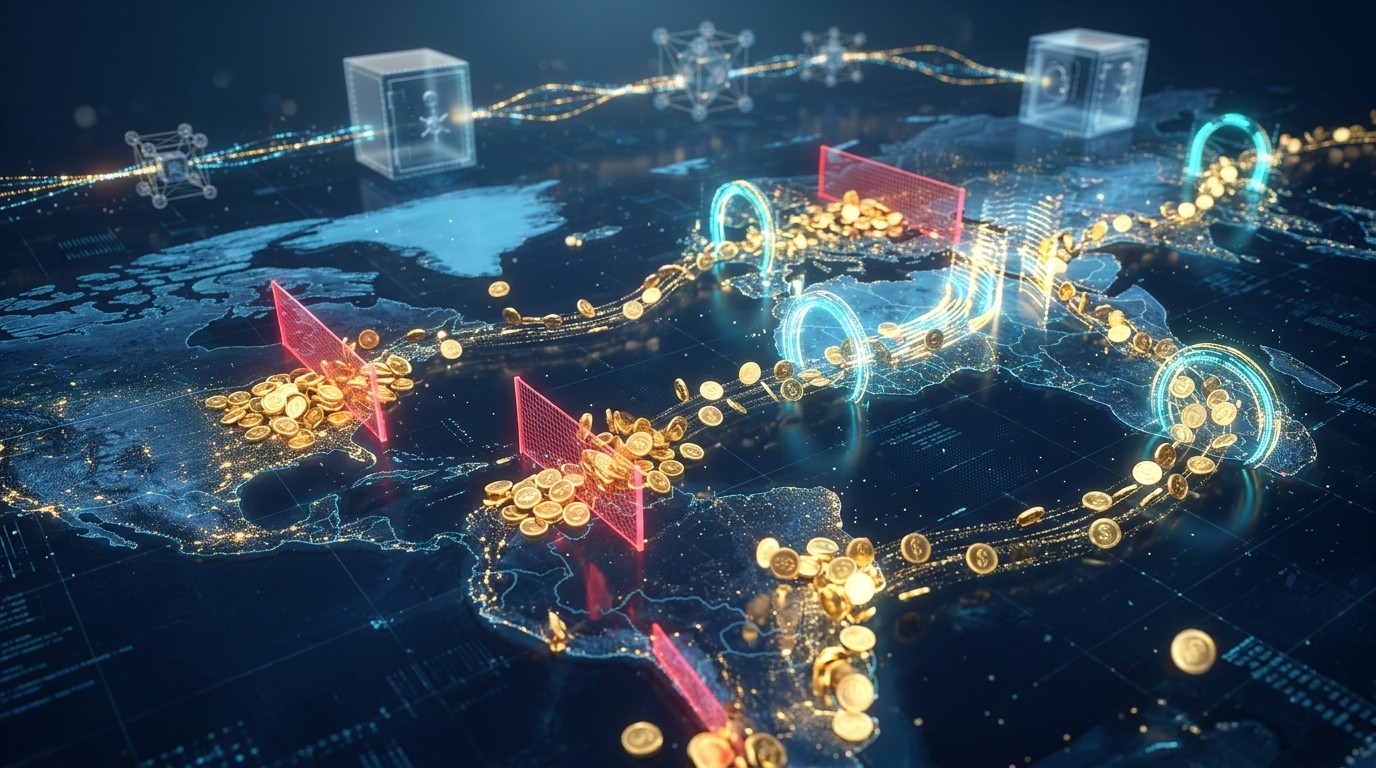

Picture this. You send a dollar-backed token from one continent to another in under a minute. The recipient sees the balance update almost instantly. Yet the actual cash and securities that supposedly back that token might sit in a bank vault thousands of miles away, subject to local laws and office hours that have nothing to do with your transaction. That gap between speed and control is exactly what keeps regulators awake at night.
Why Global Tokens Still Face Local Rules
Stablecoins have grown into a market worth roughly three hundred billion dollars. Nearly all of that value tracks the US dollar. The instruments move freely across chains and borders, but the rules that govern their reserves, redemptions and reporting still stop at national lines. I’ve watched this tension build for years, and the latest high-level assessment of the problem makes the mismatch clearer than ever.
An issuer can hold its assets in one country while users in half a dozen others trade the same token around the clock. When the market price slips below the promised one-to-one peg, people naturally head for the exit. The question then becomes simple and uncomfortable: which entity actually has to pay, and does it have the cash ready in the right place at the right time?
The Scale That Makes The Problem Systemic
Mid-year figures put the total stablecoin market near three hundred billion. Ninety-nine percent of that sits in dollar-linked tokens. Do the quick math and you land around two hundred ninety-seven billion dollars of claims that, in theory, can be redeemed for cash or cash equivalents. Those numbers are rounded and a little dated, yet they still show why a pure company-by-company view is no longer enough.
What matters more is the fraction that could be demanded on any given day and the location of the holders who might make the call. An issuer often cannot answer either question with precision. Tokens travel through secondary markets, land in self-custodied wallets, and sit behind exchange accounts that may or may not share full geographic data. The public ledger shows addresses and amounts. It does not show residency or beneficial ownership.
In my view the most striking point is how ordinary this opacity has become. We accept that a blockchain records every transfer, yet we still cannot reliably map those transfers to real-world locations or purposes. That is not a temporary data shortage. It is a structural feature of how these systems work.
When A Global Token Creates Local Pressure
A token can circulate worldwide while its legal redemption promise remains anchored in a specific jurisdiction. The wallet address never announces which court would hear a dispute or which legal entity actually owes the holder money. Institutional conversion routes often rely on regulated banks that operate on conventional schedules. Meanwhile the token itself trades twenty-four hours a day.
If secondary-market sellers grow impatient while direct redemption moves more slowly, the market price can drift away from the peg. A temporary discount does not automatically mean insolvency. At the same time, a one-dollar quote on one venue does not guarantee that every holder can cash out at par. The bridge between continuous trading and timed cash settlement sits at the heart of the vulnerability.
An issuer may not know who holds its liabilities, where those holders are domiciled, or where redemption requests will arrive.
Exchanges know some of their customers under identification rules, yet they lose sight of tokens once those tokens leave the platform. Blockchain analytics can cluster addresses and estimate flows, but residence and purpose remain largely invisible. No single dashboard stitches the pieces together automatically.
Multi-Issuer Structures And Concentrated Demand
Some arrangements involve affiliated issuers that share liability for one global token while keeping separate pools of reserves. In calm conditions the design makes the token easier to use across borders. Under stress the picture changes. Redemption demand can pile up at one affiliate even though the group as a whole holds enough assets.
Imagine two affiliates, each having issued a billion dollars of tokens and each holding a matching billion in local reserves. Holders then demand one and a half billion from the first affiliate and half a billion from the second. The group still balances overall, yet the first affiliate faces a five-hundred-million shortfall until liquidity can move across borders. Whether that movement happens quickly depends on legal access, settlement hours, asset quality and coordination among the entities.
Secondary markets and cross-border rebalancing can realign the pressures. They can also fail when confidence drops. If no one can clearly establish which affiliate’s liabilities correspond to tokens held through intermediaries, the legal picture grows messy in an insolvency scenario. Group-wide backing alone does not erase the time-and-place mismatch.
Not every stablecoin uses this multi-issuer model. A single issuer with transparent reserves faces a different set of questions. Still, the geography of reserves versus the geography of demand deserves its own monitoring lens. A single aggregate reserve ratio cannot reveal that distribution.
How Stress Could Travel Beyond Crypto Markets
Most stablecoin activity today stays inside crypto trading venues. Tokens serve as liquidity for entering, exiting and moving between digital assets. In some emerging economies they also act as stores of value. Broader payment use remains possible. The channel through which distress spreads depends heavily on that use case.
Potential spillover paths include forced sales of reserve assets, withdrawals of bank deposits to fund redemptions, reliance on stablecoins for real-economy settlement, and foreign-exchange markets used for cross-border activity. None of these chains has played out at full systemic scale so far. The point of monitoring is to spot the links before a problem at one participant becomes a problem for others.
A redemption wave does not require deficient reserves to start. Rumors, platform restrictions or a temporary inability to move funds across markets can push holders to sell below par. High-quality liquid reserves and clear redemption rights reduce the chance of a prolonged gap. Quantity and quality of backing, plus the oversight around them, remain central to resilience.
For smaller economies the same token can carry different weight. A stablecoin that looks modest next to the global dollar market can matter a great deal inside a local banking and payments system. Currency substitution, bank disintermediation and capital-flow management all become relevant once adoption grows. The risk is conditional on local circumstances rather than automatic for every cross-border transfer.
Why The Public Ledger Cannot Answer The Geography Question
Blockchains generate abundant records. A typical transfer shows the token contract, source address, destination address, amount and timestamp. It does not reliably indicate whether the movement is a remittance, exchange collateral, a trader shifting funds between own wallets, or a payment between two people in different countries. Centralized platforms often net customer trades internally without writing every transaction to the chain.
Data problems fall into two broad categories. Structural gaps come from pseudonymity and smart-contract design; better scraping alone will not reveal the person or location behind every address. More tractable gaps involve information that already exists but is not shared with authorities, or inconsistent methods used by commercial data providers. The two categories need different remedies.
Private compilers currently supply much of the information that authorities use. Their clustering rules and filtering choices can differ. One provider might count transfers between wallets controlled by the same exchange as volume; another might exclude them. Neither approach is necessarily wrong. Without the methods, a regulator comparing the two numbers cannot know whether a divergence reflects real activity or changing measurement.
Ask a basic question such as “How much stablecoin crossed the border this week?” and you quickly need reliable country labels at both ends, an account of internal exchange transfers, a way to exclude self-transfers, and consistent rules for multi-chain bridges. On-chain data alone does not supply those inputs. A precise-looking figure from a proprietary model can still carry a wide uncertainty range.
Shared formats, disclosed heuristics, combined sources and targeted reporting requirements could improve the estimates. That does not mean every transfer must become publicly identifiable. Authorities may need aggregate information from issuers and regulated intermediaries, protected by appropriate safeguards and coordinated across countries.
Partial Views That Never Quite Align
An issuer or its auditor can examine reserve accounts and the obligations recorded inside the issuer’s own system. A custodian bank sees the assets it holds, subject to its legal duties. An exchange sees customer balances and internal transfers. A chain analyst sees token movements between addresses, often without the identities behind them. A national supervisor receives reporting from entities inside its jurisdiction while meaningful activity may sit elsewhere.
None of these partial views is useless. The difficulty lies in their mismatch. A reserve attestation can confirm assets at a reporting moment without mapping where future redemption pressure will originate. Exchange records can identify a subset of holders without capturing wallet-based circulation. On-chain supply figures can identify token contracts while missing claims that exist under another legal arrangement.
Useful monitoring would track the depth, liquidity and structure of secondary markets together with the geographic distribution of holdings, redemptions and reserve assets. Geography matters especially for multi-issuer designs. Analytical expertise, information sharing and possible industry practices for combining on-chain and off-chain data all form part of the suggested direction. These metrics remain a work program rather than a finished universal template with automatic trigger thresholds.
Uneven Rules Across Jurisdictions
Treatment of foreign-issued stablecoins remains uncertain or undefined in many places. A company may issue in one country, distribute through affiliates in others, and see its token traded on platforms subject to still different licensing regimes. Peer reviews of earlier recommendations have already highlighted gaps and inconsistencies in national implementation.
No one is proposing a single global regulator. Coordination among national authorities and standard-setters remains the realistic path. Information-sharing agreements, comparable reporting formats and crisis-response plans could give existing supervisors a less fragmented picture. Whether domestic law actually permits each agency to request or exchange specific data is still a question for that jurisdiction.
The industry case for global tokens is real. Cross-border payments can be slow and expensive. Tokens available at all hours can make transfers easier and support financial inclusion. Some of those benefits may flow from distributed-ledger infrastructure itself rather than from any particular privately issued stablecoin. A policy discussion that counts only risks would miss why users and businesses adopt the instruments in the first place.
The unresolved issue is who can act once information arrives. A regulator who spots an exchange discount may lack authority over an issuer abroad. An issuer may control redemption yet have no power over the marketplace selling the token. A bank may hold the reserves without any relationship to the wallet holder. Coordinated data is necessary for oversight. It is not sufficient unless roles in stress and insolvency are clarified before stress hits.
What The Latest Assessment Actually Delivers
The recent note is deliberately limited. It assesses important data sources and their limitations rather than claiming to inventory everything supervisors will ever need. It does not identify an imminent run, assign loss probabilities or set new capital requirements. The mid-year size and dollar-peg figures describe a snapshot, not a live dashboard. Treating a monitoring paper as a forecast would stretch its claims beyond what they support.
A practical next step is to watch whether authorities can obtain comparable data on redemption queues, reserve locations and cross-border secondary-market liquidity. Equally important is the question of which institution can use that information during a crisis and whether legal claims travel cleanly with tokens across affiliated issuers. The information gaps have been named. Domestic supervisors and issuers now face the harder task of stating what they can provide and what remains structurally unobservable.
Practical Signals Worth Tracking
Several concrete developments will show whether progress is real. High-level meetings of finance ministers and central-bank governors may endorse further work or set timetables for cross-border monitoring. Publication of a comparable set of metrics covering secondary liquidity and the location of reserves and redemptions would mark a tangible step. Contractual terms of multi-issuer arrangements should clarify which entity owes a holder cash and where claims can be enforced.
- Consistent reporting of geography and redemption flows by issuers and regulated intermediaries
- Published coordination arrangements among national authorities for distress at a global issuer
- Clearer treatment of foreign-issued tokens under domestic licensing regimes
- Improved disclosure of the heuristics used by commercial data providers
- Evidence that secondary markets can absorb temporary discounts without prolonged stress
I’ve found that the most useful questions are often the simplest. Can the issuer locate the majority of its holders with reasonable confidence? Do the reserves sit in the same jurisdiction where demand is likely to appear? Are the contractual redemption rights enforceable across the affiliates that issue the same token? Answers that remain vague leave room for surprise when markets turn.
Balancing Speed And Accountability
Stablecoins offer genuine operational advantages. Settlement can occur outside traditional banking hours. Cross-border transfers can avoid some of the friction that still attaches to correspondent banking. For users in economies with volatile local currencies the dollar peg itself can provide a practical store of value. Those benefits explain the growth that has already occurred and the interest that continues.
At the same time the instruments create obligations that national supervisors must be able to monitor and, if necessary, manage. The current combination of global circulation and local legal anchors produces blind spots. Closing those blind spots does not require inventing a new global authority. It does require better data coordination, clearer contractual mapping of liabilities, and realistic crisis playbooks that account for time-zone and jurisdictional frictions.
Perhaps the most interesting aspect is how ordinary the problem has become. The technology that moves value at the speed of the internet still relies on reserves that move at the speed of traditional finance. Until those two clocks can be better synchronized, or until the legal and operational bridges between them are strengthened, the oversight gap will remain a structural feature rather than a temporary inconvenience.
The market itself will keep evolving. New issuance models, clearer reserve standards and improved transparency practices can reduce some of the frictions. Regulators will continue to refine the metrics they watch. Users and businesses will keep adopting the instruments that solve real payment and storage problems. The tension between borderless tokens and bordered oversight is unlikely to disappear. Managing it more effectively is the practical task ahead.
Looking Ahead Without Overclaiming
No single report can resolve the full set of issues. What the latest assessment does achieve is a clearer statement of where the information is missing and why that absence matters under stress. Secondary-market liquidity, the geographic match between reserves and demand, and the legal clarity of multi-issuer arrangements all emerge as priorities for ongoing work.
In practice the next few reporting cycles and policy discussions will show whether the suggested monitoring direction turns into usable tools. Comparable data on redemption patterns and reserve locations would already represent progress. Crisis coordination arrangements that exist on paper before any stress arrives would represent further progress. None of these steps eliminates risk. They do make the risk more visible and therefore more manageable.
Stablecoins remain a live experiment in how digital claims interact with traditional financial infrastructure. Their global reach is already demonstrated every day. Their oversight still operates largely inside national borders. Bridging that difference without smothering the operational advantages is the policy challenge that will shape the next phase of the market. The data gaps have been named. Closing them is now a shared task for issuers, intermediaries and the authorities that supervise them.
The conversation is far from finished. Every new disclosure, every change in contractual terms, and every improvement in data sharing will add a piece to the picture. For anyone who uses, issues or simply watches these instruments, staying attentive to the evolving match between global circulation and local accountability remains essential. The tokens move fast. The rules that ultimately stand behind them still move more slowly. That difference is worth understanding in detail.