

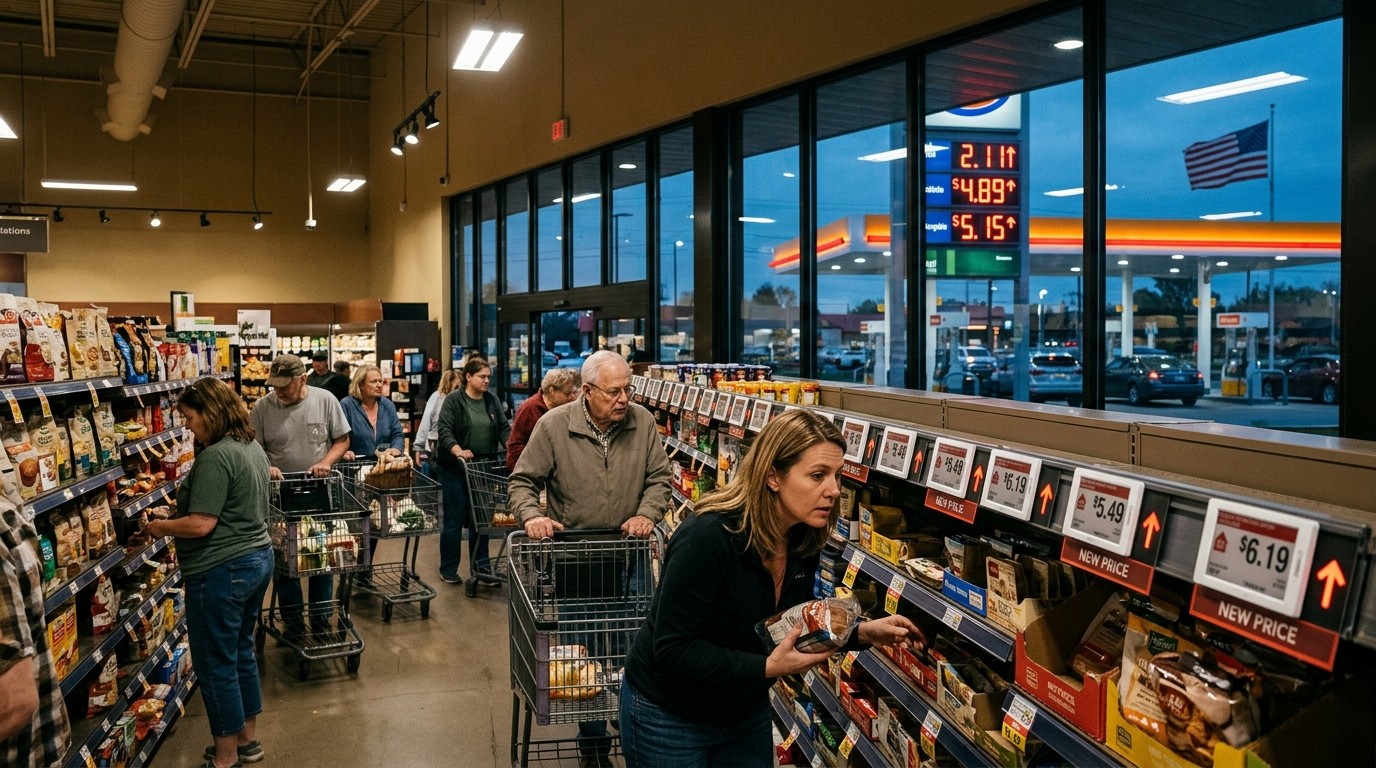

Have you noticed how much more it costs to fill up the tank or restock the fridge these days? That everyday pinch is exactly why the September consumer price index numbers due out this week feel so loaded. Economists are bracing for a report that could confirm inflation is not only sticky but actually picking up speed again, and the numbers floating around right now paint a picture that should make anyone watching the Federal Reserve sit up a little straighter.
What The Latest Forecasts Reveal About Price Pressures
Most analysts tracking the data expect the headline consumer price index to jump 0.6 percent from August to September. On a year-over-year basis that would push the reading to 3.6 percent. That is not just a number on a spreadsheet. It would mark a clear acceleration away from the central bank’s long-stated 2 percent target and suggest that the progress made earlier in the year has started to reverse in some meaningful ways.
Core inflation, the version that leaves out food and energy, looks a bit more contained on the surface. Forecasters see a 0.2 percent monthly gain and a 2.5 percent annual increase. The monthly figure would actually represent a slight cooling from the previous report, yet the yearly number would still edge higher. In my view that combination is the part that keeps policy makers awake at night. Headline numbers grab the headlines, but core measures often tell the deeper story about whether underlying price pressures are truly easing.
Energy remains the wild card that could push the entire report higher than models currently project. Oil prices have been on a tear. Brent crude, the global benchmark, climbed more than 14 percent during September alone and finished the third quarter up roughly 42 percent. At the start of this week it was still trading near 105 dollars a barrel. Those kinds of moves do not stay isolated for long. They work their way into transportation, manufacturing, and eventually the prices consumers see on store shelves.
Why Energy Costs Keep Dominating The Conversation
Energy has been one of the most persistent drivers of inflation for months now. Geopolitical tensions that flared earlier in the year continue to ripple through global oil markets. Recent policy shifts aimed at increasing supply have not produced the kind of immediate relief many hoped for. Analysts tracking the situation note that even modest increases in diesel availability are unlikely to offset the broader upward pressure already baked into prices.
One chief economist I follow closely has been especially vocal about the upside risk in this particular report. When oil moves this sharply, historical patterns suggest that official forecasts often undershoot the final printed number. That is not a prediction of disaster. It is simply a reminder that models struggle when volatility spikes. Sticky energy costs also have a nasty habit of leaking into other categories. Once companies start absorbing higher fuel and input expenses, they eventually pass those costs along, and the distinction between energy and non-energy inflation begins to blur.
We’ve got real upside risk on the September CPI. Typically, when we have these moves in inflation, everyone’s models undershoot the actual outcome.
That observation lands with particular force right now. If the headline figure comes in hotter than expected, the Federal Reserve will face even more pressure to treat the energy surge as something more than a temporary shock. Officials have already signaled that another rate increase remains on the table. After delivering their first hike in three years last month, the minutes from that meeting made clear that further tightening is a live possibility. Market participants currently lean toward a December move, though conviction about the exact timing remains low while the overall direction of travel feels more certain.
How The Federal Reserve Is Likely To Respond
The list of reasons for another rate hike keeps growing. Inflation running above target for a sustained period is the most obvious one. Labor market resilience, ongoing geopolitical uncertainty, and the simple fact that earlier progress has stalled all add weight to the case. At the same time, policy makers have to balance the risk of over-tightening against the danger of letting price pressures become entrenched again. It is a narrow path, and Wednesday’s data will help determine how much room they still have to maneuver.
I have found that the most useful way to think about the coming decision is to separate conviction from timing. Most observers share a high degree of confidence that the next move, when it comes, will be higher rather than lower. The precise meeting at which that happens is far less certain. December remains the base case for many traders, yet a stronger-than-expected CPI print could accelerate that timeline or simply harden the case for a more aggressive path later.
Perhaps the most interesting aspect is how this report arrives just weeks before the midterm elections. It is the final major inflation reading the public will see before voters head to the polls. Economic confidence has already declined across the political spectrum this year, though the drop has been steeper among some groups than others. Numbers that confirm accelerating prices could color the national conversation in ways that extend well beyond pure monetary policy.
Producer Prices Offer Another Early Warning
Thursday brings the producer price index, a measure of inflation at the wholesale level. Economists expect a 0.6 percent monthly rise and a 5.5 percent year-over-year increase. Both figures would represent a modest acceleration from the prior month. Producer prices often feed into consumer prices with a lag, so a hotter reading here would reinforce concerns that the September CPI is not an isolated blip.
Watching the two reports side by side can be revealing. When wholesale costs climb faster than retail prices, it sometimes signals that companies are absorbing margin pressure for the moment. Eventually that pressure has to go somewhere. Either prices rise or profitability suffers. In an environment where energy remains elevated, the path of least resistance is usually higher consumer prices down the road.
What Everyday Price Changes Mean For Households
Inflation data can feel abstract until it shows up in the grocery cart or the monthly budget. A 0.6 percent monthly jump does not sound dramatic on its own, yet compounded over time it erodes purchasing power in ways that are hard to ignore. Families already stretched by higher housing, insurance, and transportation costs feel each additional uptick more sharply. The acceleration in the yearly rate from previous months only amplifies that sense of pressure.
Energy stands out because it touches nearly every part of daily life. Higher diesel costs raise the price of shipping food across the country. Refineries pass along crude oil increases at the pump. Even electricity and heating bills can feel the indirect effects when natural gas and residual fuel markets tighten. The result is a broad-based cost-of-living squeeze that shows up in consumer sentiment surveys and, eventually, in spending patterns.
Core inflation remaining above 2 percent on a yearly basis suggests that the problem is not limited to volatile categories. Shelter, services, and other stickier components continue to contribute. When those areas refuse to cool quickly, the Federal Reserve has less room to declare victory and pivot toward easier policy. That is the quiet undercurrent running through this entire data cycle.
Looking Ahead To The Broader Economic Picture
The September report will not arrive in isolation. It sits inside a larger mosaic of labor market data, consumer spending trends, and global developments. Strong job numbers can support demand even as prices rise, creating the classic conditions that keep inflation elevated longer than expected. Softening demand, on the other hand, can help bring price growth back down, though it usually comes with its own set of trade-offs.
Geopolitical risks remain an unpredictable variable. Any further disruption to energy supplies would compound the already elevated baseline. Conversely, a sustained period of lower oil prices would provide welcome relief, yet few expect that scenario to materialize quickly. Policy makers therefore have to plan for a range of outcomes rather than betting on a single neat resolution.
In my experience following these cycles, the most useful posture is cautious realism. Inflation has proven more persistent than many hoped a year or two ago. Progress is still possible, yet it is unlikely to arrive in a straight line. Reports like the one due this week serve as regular reality checks on how far the economy still has to travel.
- Headline CPI is projected to rise 0.6 percent month over month
- Yearly headline inflation expected at 3.6 percent
- Core CPI forecast at 0.2 percent monthly and 2.5 percent annually
- Oil prices remain a significant upside risk factor
- Producer prices also expected to accelerate modestly
Those bullet points capture the central expectations, yet the real story will emerge in the details. Category-by-category breakdowns often reveal whether the pressure is concentrated or broad-based. Shelter costs, used vehicles, apparel, and medical care can each tell a slightly different tale. Analysts will pore over those sub-indices looking for signs of either diffusion or concentration of price increases.
Why This Particular Report Carries Extra Weight
Timing matters. Coming right before a major election, the numbers will be scrutinized not only by economists and traders but by a much wider public audience. Political narratives around the cost of living have already been prominent throughout the year. A reading that confirms accelerating inflation would likely intensify those debates, while a cooler-than-expected print could provide some breathing room. Either way, the data will not be ignored.
Consumer sentiment has already reflected growing unease. Confidence measures have declined across party lines, though the magnitude of the drop has varied. When people feel the pinch at the gas station and the grocery store, abstract debates about monetary policy become personal. That feedback loop between lived experience and economic data is one reason central banks watch these reports so carefully.
Market participants will also be parsing the numbers for clues about the December policy meeting. Futures pricing currently assigns a meaningful probability to another rate increase by year-end. A significantly hotter CPI could raise that probability further. A softer reading might keep the door open for a longer pause. The reaction in bond yields, equity futures, and the dollar will offer an immediate gauge of how the market digests the information.
Practical Ways To Think About The Data
For households, the most practical response is to stay informed without overreacting to any single release. Inflation data arrives monthly, and one print rarely defines a long-term trend by itself. Looking at three-month averages or six-month trends often provides a clearer sense of direction. Energy prices in particular can reverse quickly when supply conditions improve, so treating every spike as permanent can lead to unnecessary anxiety.
At the same time, dismissing persistent above-target inflation as temporary has proven costly in recent years. The middle path involves acknowledging the risks while recognizing that policy makers still have tools available. Higher rates eventually cool demand. Supply improvements can ease bottlenecks. Productivity gains, though harder to engineer, can also help over longer horizons.
Investors face a slightly different calculus. Rising inflation and the prospect of further rate hikes tend to pressure longer-duration assets and growth-oriented sectors. Value-oriented areas and certain real assets sometimes hold up better in such environments, though nothing is automatic. Diversification and a clear understanding of personal time horizons remain more useful than trying to outguess every data release.
| Measure | Expected Monthly Change | Expected Yearly Change |
| Headline CPI | 0.6% | 3.6% |
| Core CPI | 0.2% | 2.5% |
| Producer Prices | 0.6% | 5.5% |
The table above summarizes the consensus forecasts heading into the week. Actual results can and often do deviate, sometimes substantially when energy markets are this volatile. That is why the phrase “upside risk” keeps appearing in conversations among professional forecasters. Models calibrated on calmer periods struggle when the underlying drivers shift rapidly.
The Longer-Term Inflation Landscape
Stepping back from this single report, the broader inflation story remains unfinished. After the sharp rises of earlier years, the subsequent cooling was real and welcome. Yet the final stretch back to a stable 2 percent environment has proven more difficult than many anticipated. Structural factors such as demographic shifts, housing shortages in certain markets, and ongoing global supply chain reconfiguration all play roles that short-term data cannot fully capture.
Energy transition efforts add another layer of complexity. Investment in new capacity takes time, and periods of underinvestment can leave markets tighter than desired when demand rebounds. Geopolitical fragmentation has also reduced some of the efficiency gains that globalization once delivered. None of these forces guarantee permanently higher inflation, but they do suggest that the path back to the old baseline may be bumpier than hoped.
Policy makers will continue to emphasize data dependence. That phrase can sound like a dodge, yet it accurately reflects the reality of operating with incomplete information in a complex system. Each CPI release, each employment report, and each update on consumer spending adds another piece to the puzzle. The September numbers form one important piece, not the entire picture.
What To Watch In The Coming Days
Beyond the headline and core figures, several details deserve close attention. The contribution from energy categories will reveal how much of the monthly jump is attributable to oil and related products. Shelter costs, which have been slow to cool, remain a key swing factor. Any surprising strength or weakness in services outside of energy and shelter could signal shifts in underlying demand.
Market reaction will also be telling. Bond yields often move quickly on inflation surprises, and equity sectors can rotate based on the perceived implications for growth and policy. Currency markets tend to respond to relative interest rate expectations. Watching those cross-asset moves can provide a real-time read on how the data is being interpreted by participants with capital at risk.
Finally, the tone of commentary from Federal Reserve officials in the days after the release will matter. Even if the formal decision is weeks away, subtle shifts in language can reveal how the committee is updating its thinking. A more concerned tone would reinforce the case for further tightening. A more balanced assessment might keep options open for a longer pause.
All of this underscores why the September CPI report has attracted so much attention. It is not merely another data point. It arrives at a moment when inflation risks appear to be reaccelerating, when energy markets remain unsettled, and when the political calendar is compressing the usual policy timelines. How the numbers ultimately print will shape the conversation for weeks to come.
In the end, the best approach is to treat the report as useful information rather than a definitive verdict. Inflation dynamics evolve. Policy responds. Households and businesses adapt. Staying informed about the latest readings helps with that adaptation, whether the numbers land exactly as expected or deliver a surprise that forces everyone to update their assumptions. The coming days will provide the next chapter in a story that is still very much unfolding.
Looking further out, the interaction between energy markets and broader price trends will likely remain a central theme. If oil prices stabilize or retreat, the upside risk to future CPI prints diminishes. If they continue climbing or even hold near current elevated levels, the pressure on both headline and core measures could persist longer than models currently assume. That uncertainty is precisely why Wednesday’s release carries such weight.
Consumer behavior will also play a role in how the story develops. If households begin pulling back on discretionary spending in response to higher prices, demand-driven inflation pressures could ease. If they continue spending through the increases, relying on savings or credit, the inflation process can become more self-reinforcing. Early evidence on that front will come from retail sales and credit data in the weeks ahead.
Business pricing power is another variable worth tracking. Companies that have successfully passed along higher costs may continue doing so as long as demand remains resilient. Those facing stiffer competition or more price-sensitive customers may absorb more of the pressure in margins. The producer price index due on Thursday will offer an early look at how those dynamics are evolving at the wholesale level.
Ultimately, the September CPI report is a snapshot of conditions at a particular moment. It will not settle every debate about the economic outlook or the appropriate policy path. What it can do is refine the probabilities around different scenarios and force a fresh assessment of risks. In an environment where energy prices have already moved sharply and political stakes are high, that refinement is valuable in its own right.
As the data arrives and markets digest the implications, the focus will quickly shift to the next set of indicators and the next policy meeting. That is the nature of the economic calendar. Each release informs the next, and the process of interpretation never fully stops. For now, the attention remains squarely on whether the September numbers confirm the acceleration that so many are expecting, and what that confirmation would mean for the months ahead.



