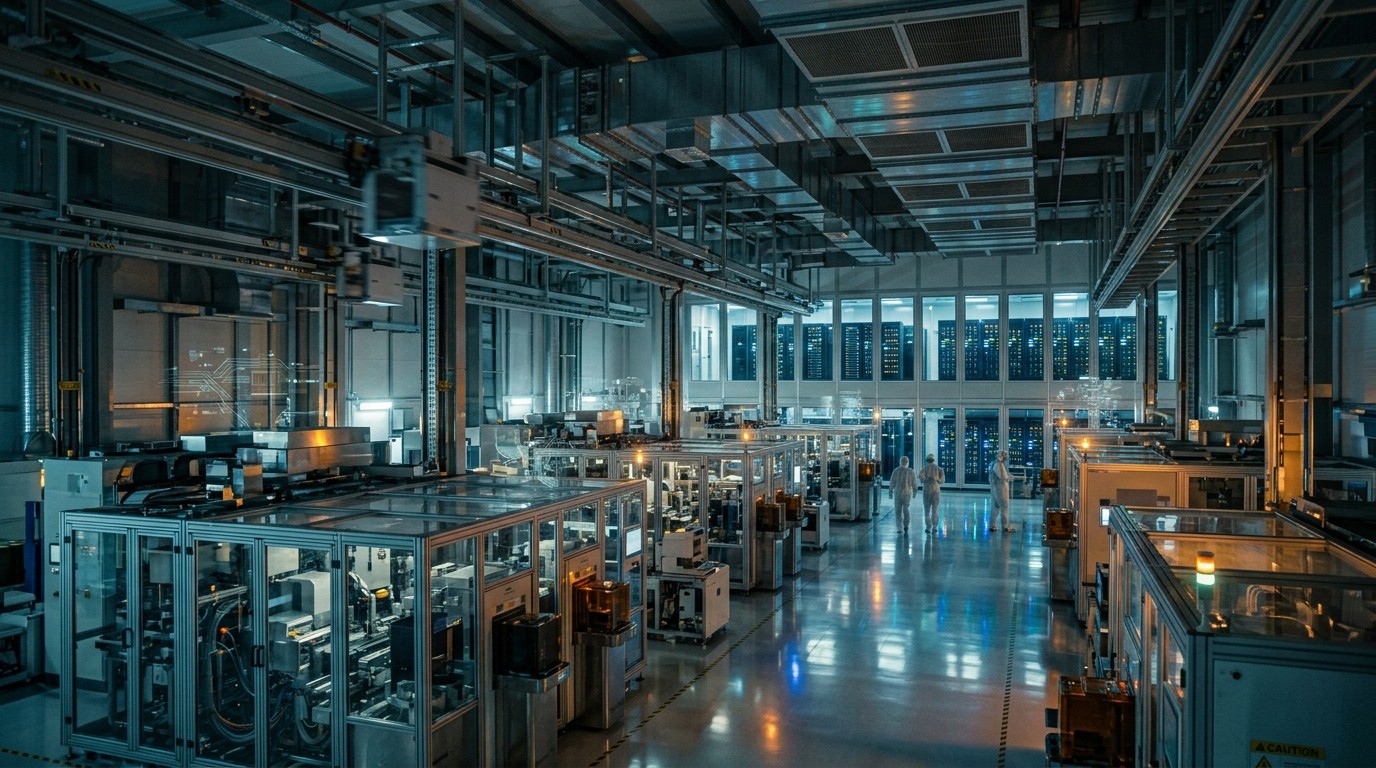

I still remember the first time I watched a video of an extreme ultraviolet machine at work. Those mirrors, the vacuum chambers, the sheer precision required to print circuits smaller than a virus. It felt almost unreal. Fast forward to this week and that same technology sits at the center of one of the strongest quarterly reports the industry has seen in a while. Customers are already talking about orders that reach into 2029 and even 2030. That kind of forward visibility does not appear every day.
Why Long-Term Orders Matter More Than One Strong Quarter
Profit numbers that beat forecasts always grab headlines. Yet the more interesting part of the latest update sits in the order pipeline. Some chipmakers have begun signaling interest in tools they will need five or six years from now. That is not normal purchasing behavior. It tells us they see sustained demand for advanced chips well beyond the current AI build-out cycle.
In my view, this shifts the conversation. We are no longer debating whether artificial intelligence needs more silicon. The discussion has moved to how fast the industry can deliver the equipment that makes those chips possible. Capacity constraints have been a recurring theme for years. Now those constraints stretch further into the future.
The Quiet Confidence Behind Multi-Year Planning
When a foundry or memory producer starts talking about 2030 equipment needs, they are making a serious bet. These machines cost tens of millions of dollars each. Lead times already run long. Placing interest this far ahead signals two things at once: deep conviction in future volume and a desire to lock in supply before competitors do the same.
I have followed this sector long enough to know that such visibility used to be rare. In earlier cycles, order books rarely stretched beyond two years with real confidence. The current environment feels different. AI training clusters, inference accelerators, and high-bandwidth memory all require the most advanced lithography available. That demand does not look temporary.
Customers expressing interest this far out is one of the clearest signals that the industry expects structural rather than cyclical growth.
Perhaps the most striking element is how this interest arrives alongside strong near-term results. The combination suggests the company is managing both the present ramp and the next decade of expansion at the same time. That is a difficult balancing act.
Capacity Realities That Shape Every Decision
Building these systems is not like expanding a simple factory line. Each tool involves extreme engineering, specialized components, and highly trained teams. Ramping output takes years of planning and investment. Even with recent expansions, the industry still faces limits on how many high-end machines can leave the production floor each quarter.
This reality explains why customers are reaching so far forward. They understand that waiting until 2027 or 2028 to place firm orders risks missing the window. By signaling early, they help the supplier plan its own capacity investments. It becomes a kind of shared roadmap rather than a series of last-minute requests.
I find this dynamic fascinating. It creates a feedback loop where demand visibility encourages more manufacturing capacity, which in turn supports even more ambitious chip designs. The whole ecosystem moves forward together, though never as quickly as some would like.
What the Profit Beat Actually Reveals
Strong third-quarter numbers did not arrive by accident. Higher average selling prices on advanced systems, solid service revenue, and disciplined cost control all played roles. Yet the real story lives underneath the surface numbers. Demand for the most sophisticated tools remains robust even as some older technology nodes face softer conditions.
This split in the market is worth watching. Logic and advanced memory continue to pull hard on the latest equipment. Mature nodes move more slowly. The company appears to be navigating that divergence with skill. Investors often focus only on the top-line growth. I prefer looking at product mix and margin trends, because they show whether the business is capturing value from the AI wave or simply riding volume.
- Advanced systems continue to drive the majority of revenue growth
- Installed base service business provides a steady, high-margin foundation
- Order interest for future years reduces uncertainty around the next investment cycle
- Capacity expansion plans now have clearer long-term justification
None of these points exist in isolation. Together they paint a picture of a supplier that sits at a genuine bottleneck in the AI supply chain. That position brings both opportunity and responsibility.
How AI Workloads Translate Into Tool Demand
Every large language model training run, every new inference chip, every high-bandwidth memory stack depends on the ability to print finer features with higher yields. That work happens on these specialized machines. When hyperscalers announce multi-billion-dollar data center builds, the ripple effect eventually reaches the lithography floor.
The lag between cloud spending announcements and equipment orders used to be longer. It has shortened. Chip designers now plan process technology roadmaps with clearer visibility into AI volume. Foundries respond by securing tools earlier. The entire chain has become more synchronized around artificial intelligence timelines.
One personal observation: the industry used to debate whether AI would create a lasting silicon boom or a temporary spike. The 2029 and 2030 interest largely settles that debate. Companies do not lock in expensive capital equipment that far ahead for a fad.
Balancing Near-Term Execution With Decade-Long Vision
Delivering strong quarterly results while preparing for 2030 is harder than it sounds. Production lines must stay full today. Engineering teams must simultaneously develop the next generation of tools. Supply chains for critical components need to scale without creating new bottlenecks. Talent pipelines have to expand in specialized fields that already face shortages.
I have spoken with people across the industry who describe the current period as both exhilarating and exhausting. The opportunity is enormous. The operational challenges match it. Getting the balance right will determine who captures the full value of this cycle.
Risks That Still Deserve Attention
No growth story arrives without caveats. Geopolitical tensions continue to influence export rules and customer access. Technology development roadmaps always carry uncertainty. Economic slowdowns in certain regions can delay secondary investments even when leading-edge demand remains firm.
Yet the long-term order interest provides a partial buffer. When customers signal needs this far out, it reduces the chance of a sudden and sharp downturn in the advanced segment. Cyclical swings still exist, of course. Their amplitude appears smaller for the highest-end tools than for more mature equipment.
Another point worth considering is execution risk on capacity expansion. Announcing plans is one thing. Delivering the systems on schedule and at the required quality is another. The track record so far has been solid, but the scale of the next decade of growth will test that record more thoroughly than previous cycles.
What This Means for the Broader Semiconductor Landscape
The implications stretch well beyond one company. When the leading supplier of critical tools gains multi-year visibility, every major foundry and integrated device manufacturer gains a clearer planning horizon. Capital expenditure budgets become easier to justify. Process technology roadmaps gain more concrete timelines. Even software and systems companies that depend on advanced chips benefit from greater certainty around future supply.
I sometimes think of the semiconductor equipment sector as the quiet foundation under the loud AI narrative. Data centers get the attention. Model releases generate the excitement. None of it scales without the physical ability to manufacture the silicon at the required density and volume. That ability starts with these tools.
| Time Horizon | Primary Focus | Key Driver |
| Current Year | Delivery and installation | Existing AI build-out |
| Next 2-3 Years | Capacity ramp | Next-generation nodes |
| 2029-2030 | Long-term reservation | Sustained AI and advanced computing |
Looking at that simple breakdown helps clarify why the latest update carries weight. It is not just about one strong quarter. It is about three distinct planning horizons aligning more tightly than they have in a long time.
The Human Side of Precision Engineering
Behind every order number sit teams of engineers, operators, and support staff who keep these complex systems running. Training new talent takes years. Retaining experienced people in a competitive market is an ongoing challenge. The company has spoken before about the importance of its workforce, and the current demand environment only raises the stakes.
I have always been struck by the quiet pride people in this field take in solving problems most of us never even see. Aligning mirrors to atomic-scale accuracy. Maintaining vacuum environments cleaner than almost anything else on earth. Pushing yields higher quarter after quarter. That culture of precision underpins the financial results we discuss so casually.
When customers commit this far ahead, they are also expressing confidence in the people who will design, build, and support the next generation of tools. That human element rarely appears in earnings summaries, yet it remains essential.
Looking Ahead Without Overreaching
It would be easy to declare that the next decade is already secured. Reality is more nuanced. Technology transitions still carry risk. Customer concentration in certain segments requires careful management. Competitive dynamics in the broader equipment market continue to evolve.
Still, the combination of near-term outperformance and long-term interest creates a stronger foundation than the industry has enjoyed in many previous cycles. The AI-driven need for advanced silicon shows little sign of slowing. The tools required to produce that silicon remain scarce relative to demand. That scarcity, managed carefully, supports both pricing power and visibility.
In my experience covering technology markets, periods of genuine structural demand are rare. Most growth stories eventually face digestion phases or competitive responses that reset expectations. The current environment around leading-edge lithography looks more durable than most. That does not mean smooth sailing. It does mean the trajectory has clearer support than usual.
Practical Takeaways for Anyone Following the Sector
First, pay attention to the mix of systems rather than only total revenue. Advanced tools carry different margins and different demand drivers than older platforms. Second, watch capacity utilization and lead times. Those operational metrics often signal turning points earlier than headline numbers. Third, keep an eye on customer commentary around their own capital plans. When leading chipmakers speak confidently about 2028 and beyond, the equipment suppliers usually benefit.
- Focus on product mix within reported numbers
- Track lead times and capacity expansion progress
- Monitor foundry and memory maker investment signals
- Consider the multi-year nature of current order interest
- Balance optimism with realistic views on execution risk
These points are not exhaustive, of course. Markets move on new information constantly. Yet they provide a useful framework for interpreting future updates.
A Broader Reflection on Technological Progress
Every few years the industry reaches a point where the physical limits of manufacturing threaten to slow the pace of innovation. Extreme ultraviolet lithography itself was once considered an almost impossible challenge. It took decades of development before high-volume production became reality. Now that reality is expanding to meet an entirely new class of computational demand.
There is something quietly impressive about that progression. Human ingenuity keeps finding ways to push past previous boundaries. The latest earnings update is, at its core, a commercial expression of that ongoing effort. Customers need more advanced chips. The tools to make them are in high demand. The supplier is responding by looking further into the future than usual.
I find myself returning to that early video of the machine at work. The precision, the complexity, the quiet intensity of the process. Those same qualities now underpin a multi-year order horizon that few expected even a couple of years ago. The numbers are impressive. The underlying capability is more impressive still.
As the industry continues to navigate the AI era, the companies that enable the physical production of advanced silicon will remain central. Strong quarterly results matter. Long-term customer interest matters more. Together they suggest that the next chapter of semiconductor progress is already being written, one carefully planned tool delivery at a time.
The coming quarters will reveal how quickly capacity can expand and how firmly those 2029 and 2030 signals convert into firm orders. For now, the message is clear enough. Demand for the most advanced manufacturing technology remains robust, and customers are planning further ahead than they have in a long while. That combination deserves attention from anyone who cares about the future of computing.
Looking back on previous cycles, periods of strong visibility often preceded significant investment waves across the entire ecosystem. Designers gained confidence. Foundries expanded. Equipment makers scaled. The pattern is not guaranteed to repeat exactly, yet the current signals share many of the same characteristics. Patience and careful observation will serve better than excessive short-term speculation.
Ultimately, the story is about more than one set of financial results. It is about the industrial foundation required to keep artificial intelligence advancing. That foundation is being reinforced today with an unusually long planning horizon. The practical implications will unfold over years rather than months. Watching how those implications develop should prove one of the more interesting threads in technology markets for the remainder of this decade.