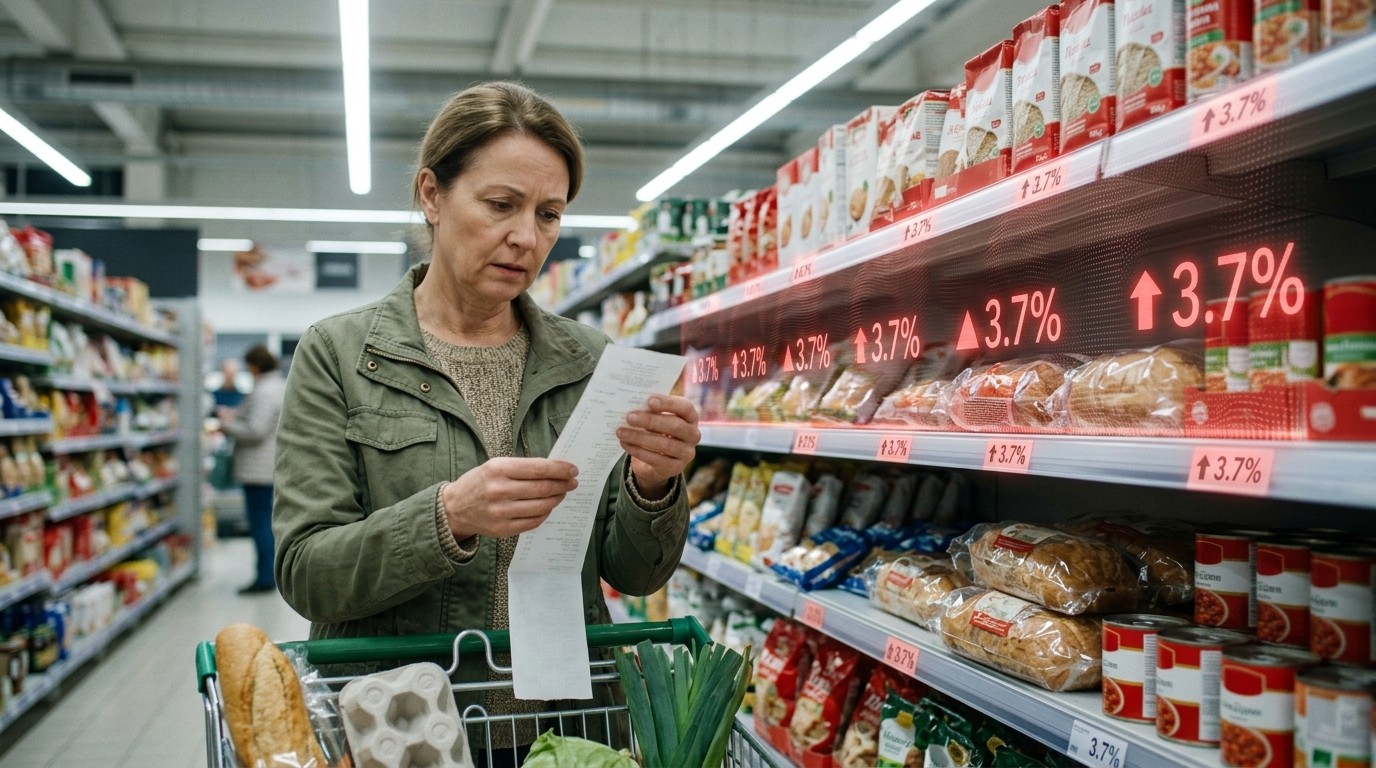

Walking through the supermarket last weekend I caught myself doing the same mental math I have done for months. A gallon of milk here, a bag of coffee there, and the total on the screen keeps climbing even when the cart looks no fuller than it did a year ago. That quiet frustration many of us feel every time we pay for ordinary goods found official confirmation this week. The latest reading on consumer prices showed another solid monthly increase and left the annual inflation rate sitting at 3.7 percent, still a long way from the comfort zone policymakers prefer.
What The Fresh CPI Numbers Actually Reveal
The broad measure of what households pay for goods and services across the economy advanced 0.6 percent on a seasonally adjusted basis during September. Over the past twelve months that same index now stands 3.7 percent higher. Most forecasters had braced for a 0.6 percent monthly rise and a slightly softer 3.6 percent yearly figure, so the outcome landed right on the monthly consensus yet a touch firmer on the annual side.
Strip away the often-volatile food and energy components and the picture changes only modestly. This so-called core measure climbed 0.3 percent for the month and 2.6 percent over the year. Those readings also came in a little warmer than the 0.2 percent and 2.5 percent many had projected. In other words, the underlying trend of price pressures remains sticky even after the wild swings of previous years have faded.
I have watched these reports for a long time, and what stands out is the stubbornness. We have seen energy prices swing wildly and food costs cool in some categories, yet the overall cost of living keeps grinding higher at a pace that continues to outrun the official 2 percent goal. That gap matters because it shapes everything from grocery budgets to mortgage rates.
Why A 0.6 Percent Monthly Jump Still Stings
At first glance half a percentage point does not sound dramatic. Spread across an entire month it can feel almost invisible. Yet compound those monthly gains and the damage accumulates fast. A 0.6 percent rise in September on top of previous increases means households are paying noticeably more for the same basket of goods than they did just a few months earlier.
Think about the practical side. Rent checks, insurance premiums, medical visits and everyday services rarely reverse course once they move higher. Even if gasoline prices soften for a stretch, the cumulative effect of earlier gains stays embedded in the index. That is why the yearly rate remains elevated at 3.7 percent rather than drifting quickly back toward the target.
In my view the real story sits less in any single month and more in the pattern. Prices have been rising at a pace that refuses to settle. Consumers notice it in the checkout line long before the official data arrives. The report simply puts a precise number on an experience most people already feel in their wallets.
Core Inflation Tells A More Persistent Tale
Removing food and energy is a standard way to judge underlying momentum. Those two categories can jump or plunge on weather, geopolitics or seasonal quirks. Once they are set aside, the remaining prices still advanced 0.3 percent in September. The yearly core rate of 2.6 percent sits closer to the desired target yet continues to move sideways rather than downward.
Services make up a large share of that core reading. Shelter costs, medical care, education and other hard-to-cut expenses tend to change slowly. When they keep rising, the overall index finds it difficult to cool. Goods prices have moderated in many categories, but services have not cooperated to the same degree.
Perhaps the most interesting aspect is how the core figure continues to surprise a touch to the upside. Forecasts expected a milder 0.2 percent monthly increase. The extra tenth of a percentage point may look small on paper, yet it reinforces the message that inflation is not vanishing on schedule.
How Households Feel The Squeeze In Daily Life
Numbers on a government release become real when they hit the family budget. A higher CPI means the same paycheck buys less than it did a year earlier. For many families that translates into tougher choices at the store, delayed purchases of bigger items, or simply less money left at the end of the month.
I have spoken with friends who track their spending more carefully than ever. They notice the price of coffee beans, the cost of a simple dinner out, and the steady climb in car insurance. Those individual stories line up with the broad data. When the official index rises 0.6 percent in a single month, it confirms that the pressure remains widespread rather than isolated to a few categories.
- Grocery staples continue to take a larger share of weekly budgets
- Housing and utility costs show little sign of meaningful retreat
- Service prices from medical visits to personal care keep advancing
- Even modest monthly gains add up quickly over a full year
None of this is abstract. The 3.7 percent yearly increase means that an item costing one hundred dollars last September now costs roughly one hundred three dollars and seventy cents. For larger household expenses the dollar difference becomes substantial.
The Gap Between Current Inflation And The Official Goal
Policymakers have long aimed for price stability defined as roughly 2 percent inflation over time. The latest yearly reading of 3.7 percent leaves a clear gap. Core inflation at 2.6 percent is closer yet still above the mark. Closing that distance has proven more difficult than many hoped after the sharp spikes of earlier years.
Why does the gap persist? Part of the answer lies in the delayed effects of past supply disruptions and strong demand. Another part comes from the way wages and prices can reinforce each other. When living costs rise, workers seek higher pay to keep up. Higher labor costs then feed into the prices of services. Breaking that cycle takes time and careful policy.
In my experience watching these cycles, the final stretch of the disinflation path often proves the stickiest. Early progress can look dramatic, but the last percentage points require sustained pressure on demand or further supply improvements. September’s data suggests that last stretch is still underway.
What The Numbers Suggest For Interest Rate Decisions
Central bank officials watch the consumer price index closely because it influences their decisions on borrowing costs. A hotter-than-desired reading reduces the room for rapid cuts in rates. At the same time, an economy that is already showing some cooling forces a balancing act.
The September figures arrived with both the headline and core measures a bit firmer than expected. That combination tends to keep policymakers cautious. They want to see a clearer and more sustained downward trend before declaring victory over inflation. A single month does not rewrite the entire outlook, yet it does reinforce the case for patience.
Price stability remains the foundation for healthy long-term growth, and current readings show that foundation is not yet fully restored.
Markets had already priced in a gradual path of rate adjustments. The latest data is unlikely to reverse that path, but it may slow the pace. Borrowers watching mortgage rates or credit card interest will notice the difference if officials choose to wait longer for clearer progress.
Comparing September With Recent Trends
Looking back over the past several reports reveals a pattern of uneven progress. Some months delivered milder gains, while others like September pushed the yearly rate higher again. The volatility itself has moderated compared with the extreme swings of a few years ago, yet the direction remains upward at a pace that keeps inflation above target.
Food prices have cooled in certain categories while energy costs continue to fluctuate with global events. Shelter, which carries heavy weight in the index, has slowed its earlier rapid climb but has not fallen. That combination produces the mixed picture we see today: progress in some areas, stubbornness in others.
I find it useful to remember that inflation is rarely a straight line. Temporary relief can give way to renewed pressure when demand stays resilient or supply chains face fresh hiccups. The September reading serves as a reminder that the process of returning to 2 percent is still incomplete.
Practical Steps Households Can Consider Right Now
While no individual can change the official index, people can respond to the environment it describes. Reviewing recurring expenses, comparing insurance rates, and adjusting grocery strategies remain sensible moves when prices keep rising. Some families find value in locking in certain costs where possible or shifting spending toward categories that have shown more stability.
- Track monthly spending against the same period last year to spot the biggest increases
- Review fixed costs such as insurance and subscriptions for potential savings
- Prioritize purchases that offer lasting value rather than short-term convenience
- Build a modest buffer for unexpected price jumps in essentials
None of these steps eliminate the broader pressure, but they can soften its impact. The data confirms that the cost of living continues to advance, so preparation remains more useful than surprise.
Broader Economic Ripples From Persistent Inflation
Higher consumer prices do more than stretch household budgets. They influence wage negotiations, corporate planning, and investment decisions. Businesses facing rising input costs often pass those costs along when demand allows. Workers facing higher living expenses seek larger pay increases. The resulting feedback loop can keep inflation elevated longer than a simple one-time shock would suggest.
At the same time, elevated prices reduce the purchasing power of savings and fixed incomes. Retirees and others living on relatively stable income streams feel the erosion most acutely. That distributional effect adds another layer of concern beyond the headline percentage.
From a growth perspective, sustained inflation above target can eventually weigh on spending if real incomes fail to keep pace. The current environment still shows resilience in many sectors, yet the risk of gradual erosion remains worth watching.
Looking Ahead To The Coming Months
One report never settles the inflation debate. Future readings will reveal whether September’s firmer numbers prove temporary or mark a more lasting firmness. Energy markets, labor conditions, and the path of shelter costs will all play roles in the next chapters.
If core measures begin to ease more convincingly, confidence that inflation is returning to target will grow. If they remain sticky near current levels, the path back to 2 percent will look longer. Either outcome carries consequences for interest rates, financial markets, and everyday budgets.
I tend to watch the core services component most closely. Goods prices have already moderated in many areas. Services, especially those tied to housing and labor, will determine how quickly the overall index can settle. September offered little evidence of a sudden breakthrough on that front.
Putting The Latest Data In Historical Context
Inflation has moved through several distinct phases in recent years. Rapid acceleration gave way to a period of gradual cooling, and now the process has settled into a slower grind. The current 3.7 percent yearly rate remains well below the peaks of earlier spikes yet stubbornly above the long-term average that defined the previous decade.
That historical comparison helps set expectations. Returning all the way to 2 percent after a period of elevated readings often takes longer than the initial decline. Policy, market forces, and simple base effects all interact. The September figures fit the pattern of a transition that is still incomplete.
Perhaps the most useful perspective is to treat the data as a progress report rather than a final grade. Progress has occurred, yet the remaining distance is clear. Households and policymakers alike must navigate the stretch that still lies ahead.
Why Communication Around Inflation Matters
Clear explanation of the numbers helps people understand why their expenses feel heavier. When official data lines up with lived experience, trust in the information grows. When gaps appear between the reported figures and daily reality, frustration can rise.
The latest release offers a relatively straightforward message. Prices rose again in September, the yearly rate sits at 3.7 percent, and core measures remain above the preferred target. That transparency allows families, businesses, and investors to adjust plans with better information.
In my own reading of these reports I value the consistency of the measurement process. Even when the numbers disappoint, knowing they rest on a broad and established methodology provides a reliable benchmark. The alternative of incomplete or delayed information would leave everyone flying blind.
Balancing Growth Concerns With Price Stability
Every inflation report sits inside a larger economic picture. Strong demand can support jobs and incomes while also contributing to price pressures. Cooling demand can ease inflation yet risk slower growth. Officials must weigh both sides when setting policy.
The September data leans slightly toward the inflation side of that balance. A 0.6 percent monthly rise and a 3.7 percent yearly rate keep price stability concerns alive. At the same time, other indicators will determine whether the overall economy retains enough momentum to absorb higher rates without sharp slowdown.
That balancing act is never simple. Too much focus on inflation can overlook softening in the labor market or consumer spending. Too little focus can allow elevated prices to become entrenched. The latest numbers simply add one more data point to an already complex decision set.
Key Takeaways From The September Reading
Several points stand out clearly. Consumer prices advanced 0.6 percent for the month. The yearly inflation rate reached 3.7 percent. Core prices excluding food and energy rose 0.3 percent monthly and 2.6 percent annually. Both the headline and core figures came in a touch firmer than most forecasts.
These results show that the cost of living continues to rise at a pace above the long-run goal. Progress has been real compared with earlier peaks, yet the final return to target remains a work in progress. Households will continue to feel the effects in everyday purchases, while policymakers will continue to weigh the data carefully.
| Measure | September Change | Annual Rate | Compared With Expectations |
| Headline CPI | 0.6 percent | 3.7 percent | Monthly in line, annual slightly higher |
| Core CPI | 0.3 percent | 2.6 percent | Both slightly firmer |
The table captures the essential comparison. Expectations were already for a solid monthly gain. The outcome confirmed that view while adding a small extra firmness on the yearly side and in the core measures.
Final Thoughts On Navigating The Current Environment
Inflation at 3.7 percent is not a crisis, but neither is it the comfortable stability many prefer. It represents a middle ground that still requires attention. For families the practical response remains careful budgeting and awareness of where costs are rising fastest. For policymakers the response involves patience and data dependence.
I have found that the most useful approach is to stay informed without becoming overwhelmed by every monthly fluctuation. The September report fits into a longer story of gradual cooling that has not yet reached its destination. That story will continue to unfold in the months ahead, and each new reading will add another chapter.
Until clearer evidence of sustained progress appears, the message from the latest consumer price index remains straightforward. Costs are still climbing, the yearly rate sits well above target, and the path back to 2 percent inflation is not yet complete. Understanding that reality helps everyone plan with clearer eyes.
The numbers themselves are only the starting point. What matters more is how households, businesses, and officials respond to the pressure they describe. September offered little relief, yet it also offered clarity. That clarity, uncomfortable as it may feel at the checkout counter, remains the most valuable product of the entire report.