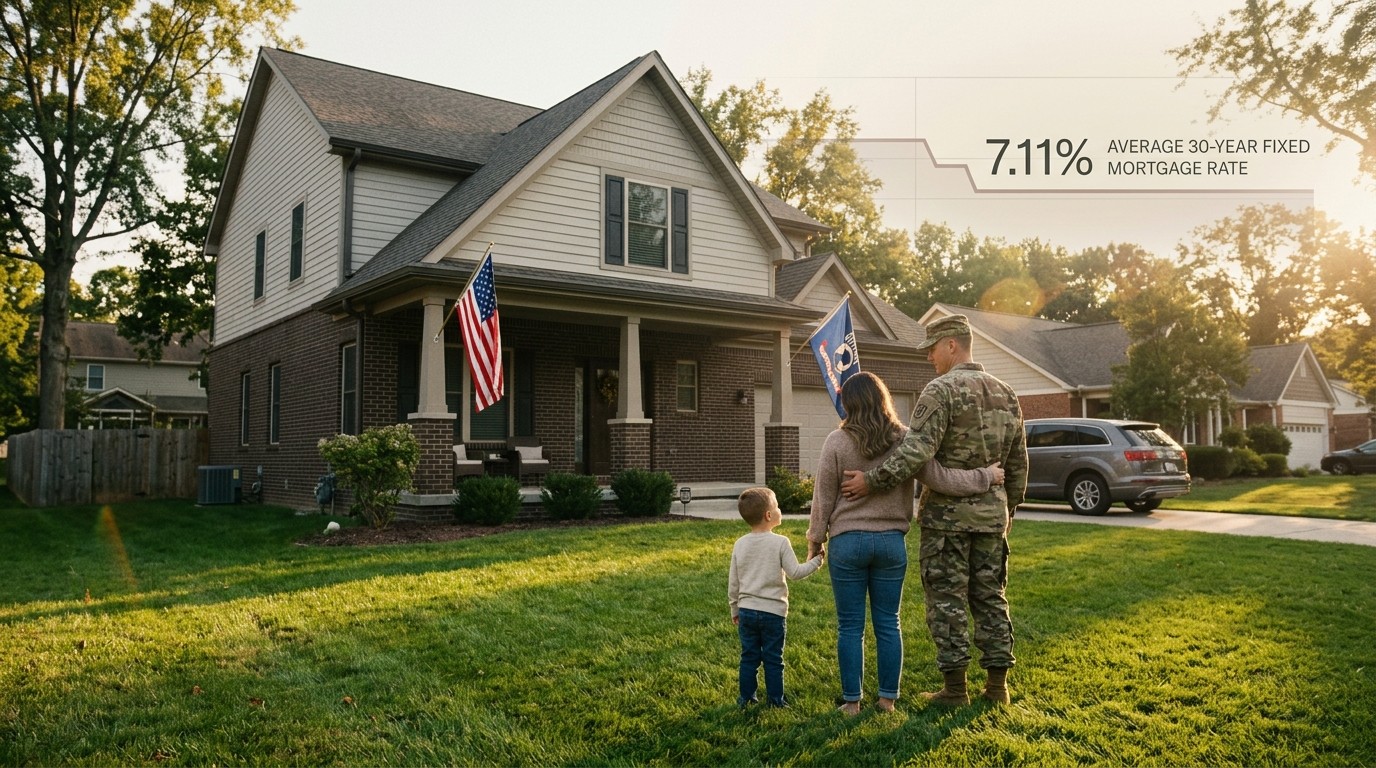

I still remember the first time a veteran friend told me he was staring at mortgage rates that felt completely out of reach. He had served two deployments, saved what he could, and yet the idea of putting twenty percent down seemed impossible. That conversation stuck with me. Today, on October 14 2026, the average 30-year fixed VA loan rate sits at 7.11 percent according to the latest market data. It edged a little lower than Monday, which is welcome news, but the number itself only tells part of the story. What matters more is how veterans and active-duty members can turn that rate into a practical path toward homeownership without draining every last dollar they have.
Understanding Where VA Loan Rates Stand Right Now
Rates move daily, sometimes by only a few basis points, yet those small shifts can change monthly payments by dozens of dollars. The current 7.11 percent figure reflects locked rates from a broad slice of lenders across the country. It is not a guaranteed quote for every borrower. Credit profile, loan size, and even the specific lender’s pricing model all play a role. Still, the fact that the average has softened slightly offers a small window of opportunity for anyone who has been waiting on the sidelines.
VA loans remain one of the strongest tools available to those who have worn the uniform. No down payment is required in most cases. Private mortgage insurance disappears entirely. Closing costs can often be negotiated or covered by the seller. These features do not erase the impact of a mid-seven-percent rate, but they soften it considerably when compared with conventional financing that demands cash up front and monthly insurance premiums.
Why the Rate Environment Feels Different This Week
Market watchers noticed the modest dip from Monday’s reading. Bond yields, inflation expectations, and broader economic signals all feed into mortgage pricing. For veterans, the practical question is whether this small improvement is enough to move forward or whether waiting for further declines makes more sense. In my experience, trying to time the absolute bottom rarely works out cleanly. Life events, family needs, and local housing inventory often matter more than chasing another quarter-point drop.
That said, the difference between 7.25 percent and 7.11 percent on a $350,000 loan is real money over thirty years. It is worth running the numbers carefully rather than assuming every rate movement is insignificant.
The Core Advantages That Still Matter Most
Zero down payment remains the headline benefit. Many service members leave active duty with modest savings after years of frequent moves and deployments. Being able to purchase a home without writing a large check removes one of the biggest barriers. The absence of monthly mortgage insurance is another quiet but powerful advantage. Conventional borrowers who put less than twenty percent down often pay hundreds of dollars extra each month for years. VA borrowers skip that cost entirely.
Interest rates on VA loans also tend to sit a bit lower than comparable conventional rates because the government guarantee reduces risk for lenders. That spread is not enormous, yet it compounds over the life of the loan. Add the ability to roll certain closing costs into the loan amount or negotiate seller concessions, and the overall cash needed at the table drops dramatically.
Choosing a Lender When Service and Rates Both Count
Not every lender treats VA loans with the same level of care. Some treat them as just another product. Others have built entire teams around military borrowers and understand the unique paperwork, timelines, and life circumstances that come with service. The difference shows up in how smoothly the process moves and how competitive the final pricing becomes.
Customer service ratings matter more than many people realize. A lender that answers the phone at odd hours or provides free credit counseling before the formal application can save months of frustration. Some institutions also offer rate-drop options after closing for a modest fee, which can be useful if rates continue to ease.
What Strong Customer Support Looks Like in Practice
I have watched veterans spend weeks chasing documents only to discover a lender had no real experience with residual income calculations or Certificate of Eligibility issues. The better companies keep dedicated specialists who know the VA system inside and out. They also tend to maintain higher satisfaction scores from independent surveys and maintain clean records with consumer protection agencies.
Beyond the transaction itself, some lenders support broader military family programs. That extra layer does not change the interest rate, but it signals a long-term commitment rather than a one-time sale.
When Competitive Pricing Becomes the Priority
Certain credit unions that serve military members consistently post rates below the national average. Membership requirements usually involve a connection to the armed forces, which keeps the focus tight. These institutions sometimes layer additional benefits such as the ability to lower the rate later without a full refinance. For borrowers who locked in when rates were higher, that flexibility can be valuable.
Online platforms have also improved dramatically. Fully digital applications, remote closing options, and partner credits with real estate agents can reduce both friction and out-of-pocket costs. The key is verifying that the digital experience does not come at the expense of knowledgeable human support when complicated questions arise.
The best lender is rarely the one with the flashiest advertisement. It is the one that matches your specific timeline, credit situation, and communication preferences while still delivering a competitive rate.
Practical Steps Before You Apply
Start with the Certificate of Eligibility. Most lenders can pull it electronically in minutes if your service record is straightforward. Gather recent pay stubs, bank statements, and a clear picture of any existing debts. Residual income guidelines for VA loans look beyond the simple debt-to-income ratio and consider whether enough money remains after major expenses to support daily living. Understanding those numbers early prevents surprises later.
Credit scores still matter even though VA loans are more flexible than conventional products. Higher scores generally unlock better pricing. Spending a few months improving utilization ratios or correcting reporting errors can pay for itself many times over in lower interest costs.
- Pull your free credit reports and dispute any clear errors
- Keep credit card balances well below thirty percent of limits
- Avoid opening new accounts in the months before applying
- Document any large deposits so underwriters understand the source
How Loan Terms Shape Long-Term Affordability
Most borrowers choose the thirty-year fixed option for the lowest monthly payment. Fifteen-year terms cut total interest dramatically but raise the monthly obligation. Some lenders offer custom terms between eight and twenty-nine years, which can help match the payment to a specific budget or expected career timeline. Adjustable-rate options exist as well, though fixed rates currently dominate for good reason given the uncertainty around future rate paths.
Running amortization scenarios side by side is one of the most useful exercises a borrower can do. Seeing the difference in total interest paid over the full term often clarifies which structure actually fits the household best.
The Role of Closing Costs and Seller Concessions
VA loans allow sellers to contribute toward closing costs within set limits. In competitive markets those contributions can disappear, yet in balanced or buyer-friendly markets they remain common. Some lenders also provide credits in exchange for a slightly higher rate. The math needs careful review because a higher rate lasts for years while a credit is a one-time benefit.
I have seen borrowers focus so intently on the interest rate that they overlook several thousand dollars in upfront costs. The opposite mistake is equally common. Balancing both sides produces the clearest picture of true affordability.
Common Pitfalls That Still Catch People Off Guard
One frequent issue involves residual income shortfalls in high-cost areas. Another appears when borrowers try to finance the VA funding fee on top of the maximum loan amount without realizing the impact on loan-to-value ratios. Appraisal gaps can also create last-minute stress if the home does not meet the purchase price. Building a modest cushion into the budget and maintaining open communication with the loan officer reduces these risks.
Timing the application relative to a permanent change of station or separation from service requires extra planning. Orders can change, and some benefits depend on active-duty status at specific moments. Starting conversations early with both a lender and a real estate professional familiar with military moves helps keep the process aligned with official timelines.
Looking Beyond the Purchase to Future Flexibility
Many veterans use the VA loan once and then sit on the property for years. Others refinance when rates drop or when equity grows enough to support a cash-out option for renovations or debt consolidation. The ability to reuse the benefit after selling a previous VA-financed home remains one of the program’s quieter strengths. Keeping good records of prior loan payoffs and entitlement restoration makes future transactions smoother.
Some lenders now offer streamlined refinance paths that reduce documentation. Others provide rate-modification programs that avoid a full refinance altogether. These tools are worth asking about even if the current rate feels acceptable, because circumstances change.
Matching Lender Strengths to Personal Priorities
Someone who values round-the-clock phone support and free credit coaching will gravitate toward one type of institution. A borrower focused primarily on shaving every possible basis point off the rate may prefer a different model. Fully digital processes appeal to those who want to manage everything from a phone between deployments or shift work. There is no universal best lender, only the best fit for a particular situation.
I tend to encourage people to obtain at least two or three competing loan estimates early in the process. Comparing the interest rate, the annual percentage rate, and the cash required to close side by side removes a lot of the sales pressure and reveals genuine differences.
| Priority | What to Emphasize | Typical Trade-Off |
| Customer Support | Dedicated military specialists, high satisfaction scores | May not always post the absolute lowest rate |
| Lowest Rate | Consistent pricing below national averages | Membership or eligibility requirements may apply |
| Digital Convenience | App-based management, remote closing options | Human support can feel thinner during complex issues |
Preparing Mentally and Financially for the Process
Buying a home is stressful even under the best conditions. Adding the layers of military life, frequent moves, or recent transitions multiplies the complexity. Setting realistic expectations about timelines, appraisal outcomes, and rate locks helps keep emotions in check. A rate lock protects against upward movement for a defined period, usually thirty to sixty days. Understanding the extension costs if the closing date slips is part of smart planning.
Building a modest emergency fund before closing provides breathing room if unexpected repairs appear after move-in. VA loans do not require reserves in the same way some conventional programs do, yet having cash available still reduces stress.
The Bigger Picture for Military Homeownership
Homeownership has long been viewed as a cornerstone of financial stability. For those who have served, the VA loan program was designed specifically to make that stability more accessible. The current rate environment is not the easiest we have seen in recent decades, yet the structural advantages of the program continue to outweigh many of the challenges. Zero down payment, no monthly mortgage insurance, and competitive interest rates still form a powerful combination.
Markets will keep moving. Rates will rise and fall. What remains constant is the value of approaching the decision with clear eyes, solid preparation, and a lender that treats the transaction as more than a simple file number. The modest improvement to 7.11 percent this week may or may not mark a turning point. For many veterans, the more important turning point is deciding that the time has come to put the benefit to work.
Take the time to review your eligibility, gather the basic documents, and speak with a few qualified lenders. Compare the full picture rather than any single number. The right structure for your household will become clearer once the options sit side by side. And if the numbers still feel tight today, the preparation itself positions you to move quickly when conditions improve further.
Homeownership after military service carries a particular weight. It represents roots after years of mobility, a place that belongs fully to the family rather than the next set of orders. The tools to make it happen remain available. Using them wisely starts with understanding exactly where rates stand today and which partners can turn those rates into a successful closing.
Final Thoughts on Timing and Decision Making
No one can predict the next six months of rate movement with certainty. What can be controlled is the quality of preparation and the choice of lender. A slightly higher rate with excellent service and smooth execution often produces a better overall experience than the absolute lowest quote paired with poor communication. Conversely, leaving significant money on the table for no good reason is equally unwise.
Perhaps the most useful mindset is to treat the process as a series of informed trade-offs rather than a hunt for perfection. Run the payment scenarios. Check residual income guidelines against your actual budget. Confirm entitlement status early. Then choose the path that aligns with both the numbers and the practical realities of daily life.
The 7.11 percent average on October 14 2026 is simply today’s snapshot. Tomorrow’s number may differ. The underlying benefits of the VA loan program, however, have proven durable across many different rate environments. For those ready to use them, the opportunity remains open.