
Paying an overseas supplier used to feel like navigating a maze of forms, waiting days for clearance, and watching fees quietly eat into the total. I’ve watched enough of these transfers stall over the years to know the frustration is real. Now a platform called A7 International claims it can turn that process into something almost as simple as sending a message from your phone. The idea is straightforward yet powerful: you send USDT, and the person or company on the other end receives a normal bank deposit. No crypto wallets required on their side. That single change could reshape how many smaller businesses handle cross-border work.
How A7 International Is Rewriting the Rules of Global Settlements
The company started in 2024 with a clear focus on supporting Russian businesses engaged in foreign trade. Within two years it grew into a noticeable force, handling roughly 15,000 companies and processing more than 10 trillion roubles in 2025. That domestic success created demand from firms outside Russia. Foreign clients began asking for the same speed and simplicity. A7 responded by launching an international version designed for remote use and limited to jurisdictions where digital-asset circulation is legal.
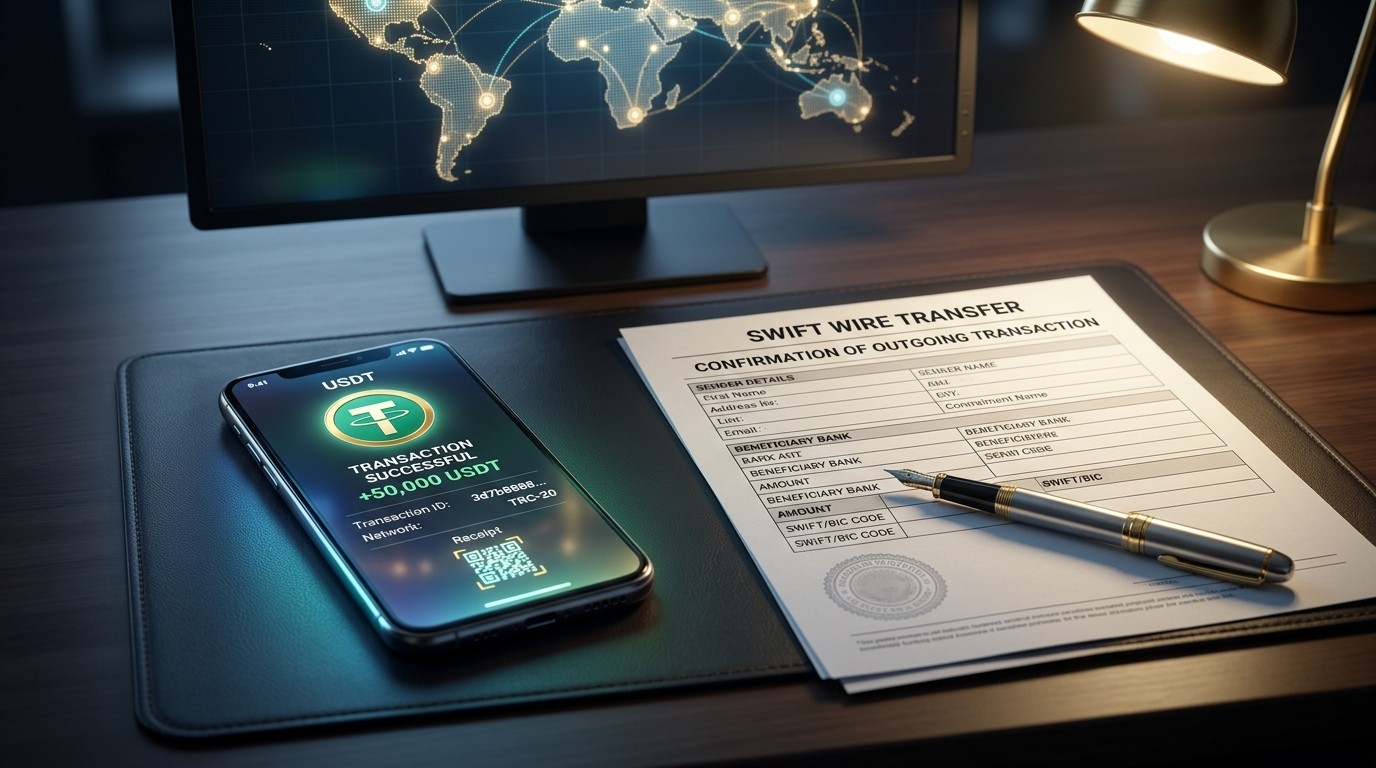
What stands out is the deliberate decision to keep the recipient experience completely traditional. The sender moves USDT on the TRON network. A7 then arranges a bank transfer through SWIFT or similar channels using the exact details listed on the invoice. The money lands in a regular account. Recipients never touch cryptocurrency. In my view that hybrid approach is the real innovation. It removes the biggest barrier many companies still face when dealing with digital assets.
The Simple Mechanics Behind the Service
Registration happens on the a7.biz personal account. Individuals complete standard identity checks. Companies go through corporate verification. Once approved, the user uploads an invoice and any supporting documents. An internal system reads the invoice automatically and helps fill the application. From there the process becomes largely automated.
An artificial-intelligence layer examines the sender, the beneficiary, the jurisdictions involved, and a set of risk factors. It builds a risk profile for the payment and matches that profile against available payment routes. Cost, speed, reliability, and regulatory limits all factor into the recommendation. The routing can shift if conditions change. Years of accumulated transaction data feed continuous improvement of those decisions.
We are presenting not just a new product in the lineup, but a new image of A7. We have adapted our service so that it can be used remotely from anywhere in the world.
At launch the platform accepts only USDT on the TRON network. Bank payouts currently cover US dollars, euros, Chinese yuan, and UAE dirhams. Other currencies can be arranged in advance. The fee sits at 0.3 percent for both businesses and individuals. Clients see the final cost, commission included, before they confirm. Execution typically takes one business day or longer. After completion the user receives a SWIFT message or equivalent proof, plus the closing documents needed for currency and customs control.
Why the Timing Feels Right
Cross-border payments still carry friction that feels outdated in 2026. Traditional banking corridors remain slow for many corridors. Fees stack up. Holds appear without clear explanation. Smaller companies often lack the volume to negotiate better terms. A service that lets them use a widely available stablecoin while delivering conventional bank money to the other party addresses a genuine gap.
I’ve spoken with operators who already run international supply chains. The common complaint is not the existence of crypto options but the practical difficulty of getting counterparties to accept them. Many suppliers simply refuse digital-asset payments. They want the money in their regular account so it fits existing accounting and tax systems. A7 International removes that refusal by handling the conversion and the final bank leg itself.
The platform also stresses compliance. It operates only where local rules permit cryptocurrency activity. The AI-driven risk assessment is designed to keep transactions inside those boundaries. That focus matters. In an environment where regulators continue to refine digital-asset rules, a service that prioritizes legal alignment has a better chance of lasting.
Practical Benefits for Everyday Business Users
Speed ranks high on the list. One business day is not instantaneous, yet it compares favorably with many traditional routes that stretch into several days or longer. Transparency is another plus. Seeing the exact cost before confirmation eliminates the unpleasant surprise of hidden charges. Remote access means a founder in one country can settle an invoice for a partner in another without flying anyone anywhere or opening local bank accounts.
The documentation package deserves mention. Closing papers for currency control and customs help keep the paper trail clean. Companies that already deal with export-import formalities will appreciate not having to chase extra confirmations.
- Low fixed commission of 0.3 percent
- Final cost visible before payment
- Recipient receives ordinary bank funds
- Supporting documents supplied after settlement
- Works from a smartphone interface
Perhaps the most interesting aspect is how the service packages these features into a single remote flow. Users do not need to manage multiple providers or maintain separate crypto and banking relationships for each corridor. One account handles the entire sequence.
Risk Considerations and Realistic Limits
No payment system is perfect. Stablecoin transfers still depend on the underlying blockchain remaining functional and liquid. TRON has proven reliable for USDT movement, yet network congestion or temporary disruptions can occur. The conversion into fiat and the subsequent bank transfer introduce ordinary banking risks such as correspondent-bank delays or compliance reviews on the receiving side.
Users must also complete KYC or KYB processes. That step is necessary for regulatory reasons, but it requires preparation of identity or corporate documents. Companies operating in tightly restricted jurisdictions may find the service unavailable. A7 is explicit about operating only where cryptocurrency circulation is permitted.
I’ve found that the most successful early users are those who already understand both traditional trade finance and the practical side of stablecoins. They treat the platform as a bridge rather than a complete replacement for every banking relationship. That measured approach tends to produce fewer surprises.
The Broader Shift Toward Hybrid Payment Models
A7 International is not alone in exploring the space between crypto rails and traditional banking. Other services have tried similar bridges. What differentiates this launch is the scale of the domestic operation that preceded it and the explicit focus on remote international access. The company already processed large volumes before expanding outward. That operational track record gives the new product a foundation many startups lack.
The presentation itself took place on a deliberately chosen date and time: October 13 at 13:13. Symbolism aside, the message was clear. The team wants users to feel the service is ready for everyday commercial use rather than experimental trials.
In practice the hybrid model may encourage more businesses to keep a portion of working capital in stablecoins. When conversion into bank money becomes fast and inexpensive, the incentive to hold digital assets for settlement purposes grows. That dynamic could gradually increase liquidity on the corridors the platform serves.
Who Stands to Gain the Most
Export-oriented small and medium enterprises look like the primary audience. These firms often lack dedicated treasury teams yet still need reliable ways to pay foreign suppliers or receive payment from overseas buyers. Freelancers and independent contractors who invoice internationally form another natural group. They can settle in USDT and still deliver bank funds to the client’s preferred account.
Larger companies may use the service for specific corridors where traditional banking remains expensive or slow. The ability to choose the route based on real-time cost and reliability data adds flexibility that rigid banking relationships sometimes lack.
Individuals also have access, provided they complete verification. The same 0.3 percent fee applies. That parity between personal and corporate pricing is uncommon and could attract smaller-volume users who previously found cross-border options too costly.
Looking Ahead at Possible Developments
The current launch focuses on USDT and four major fiat currencies. Expansion of accepted stablecoins or additional payout currencies would broaden usefulness. Deeper integration with accounting software could reduce the manual steps of invoice upload. Stronger mobile-first features would match the stated goal of completing transfers from a smartphone.
Regulatory clarity will remain a moving target. Services that adapt quickly to new rules in different jurisdictions will keep an advantage. A7’s emphasis on local compliance and AI-assisted risk profiling suggests the team understands that reality.
I keep returning to one practical observation. The companies that adopt tools like this earliest are usually the ones already feeling the pain of slow traditional corridors. They test small payments first, confirm the documentation works with their accountants, and then scale volume. That cautious path still leaves room for meaningful efficiency gains.
A Closer Look at the User Journey
Imagine a manufacturer in Southeast Asia that needs to pay a European parts supplier. The invoice arrives in euros. The manufacturer holds USDT. Instead of converting through multiple exchanges and then initiating a bank wire, the team logs into the A7 International account, uploads the invoice, confirms the displayed cost, and sends the stablecoin. Within a business day or so the supplier sees the euro amount in its bank account along with the usual SWIFT reference.
The manufacturer receives the confirmation documents needed for its own records. Currency-control paperwork is already prepared. The entire sequence stays inside one platform. That compression of steps is what many operators say they want.
Of course the first transfer always carries extra caution. Users typically start with modest amounts to verify the full cycle. Once confidence builds, larger invoices follow. The platform’s track record with thousands of domestic clients provides some reassurance that the underlying infrastructure has already handled significant volume.
Comparing Cost and Transparency
Traditional bank wires often carry fixed fees plus percentage charges that vary by corridor and by the number of intermediary banks. Exchange-rate spreads add another layer of cost. Crypto-to-fiat services sometimes introduce their own spreads or delayed settlement. A flat 0.3 percent commission with the final figure shown in advance removes much of that uncertainty.
Transparency alone does not guarantee the cheapest possible route on every occasion. Dynamic routing, however, aims to select among available options based on current conditions. Over repeated use the average cost should stay competitive for the corridors the platform supports.
I’ve noticed that businesses value predictability almost as highly as absolute lowest cost. Knowing the exact outflow before confirming a payment helps cash-flow planning. That predictability is part of the quiet appeal here.
Compliance and Trust Building
Every cross-border payment system eventually faces questions about source of funds and destination of funds. A7 International addresses those questions through structured verification and ongoing AI monitoring. The system evaluates jurisdictions and transaction patterns before recommending a route. That pre-check reduces the chance of a payment being rejected later by a correspondent bank.
Trust also grows from the documentation trail. Receiving a proper SWIFT message or equivalent confirmation after each transfer gives accountants and auditors the paper they expect. Closing documents for customs further reduce downstream friction.
Building that trust takes time. Early adopters will watch settlement times and documentation quality closely. Consistent delivery on both fronts will determine whether the service moves from occasional use to regular operational tool.
Potential Impact on Smaller Market Participants
Large corporations already negotiate preferential banking terms. Smaller firms rarely enjoy the same leverage. A platform that offers the same fee schedule to individuals and companies levels part of that playing field. Combined with remote access, it lowers the barrier for businesses that previously found international payments cumbersome.
Freelancers and digital-service providers form another group that could benefit. Many already receive or hold stablecoins. Being able to convert those holdings into clean bank transfers for clients who still prefer traditional methods expands the set of workable relationships.
Over time the presence of efficient hybrid options may encourage more counterparties to accept invoices denominated in ways that suit both parties. The conversation shifts from “we only take bank wires” to “we can work with whichever settlement path is most practical.”
Technical Underpinnings Worth Noting
The choice of TRON for USDT transfers is practical. The network has long handled large volumes of stablecoin movement at relatively low cost. That infrastructure choice supports the low overall fee the platform can offer. The AI routing layer sits on top of existing payment channels rather than attempting to replace them entirely. It selects among available paths instead of inventing new ones.
Data accumulation is described as a continuous improvement loop. Each transaction adds information that can refine future risk assessments and route selections. In principle that feedback should make the system more accurate over time. Real-world performance will show how well the theory holds.
The remote nature of the service also implies robust security around the personal account. Identity verification, document upload, and fund movement all require careful protection. Users should apply the same caution they would with any financial platform: strong authentication, careful review of details before confirmation, and regular monitoring of account activity.
Balancing Innovation with Everyday Practicality
Some payment innovations remain interesting mainly to specialists. Others solve problems that ordinary commercial teams face every week. A7 International positions itself in the second category. The emphasis on ordinary bank receipt, visible pricing, and supporting documents speaks to operational realities rather than pure technology demonstrations.
That practical orientation may prove more durable than flashier alternatives. Businesses adopt tools that reduce friction without introducing new forms of complexity. When the recipient side stays familiar, adoption faces fewer internal obstacles.
In my experience the services that last are the ones that respect existing workflows while quietly improving them. The hybrid model does exactly that. It inserts digital-asset efficiency at the point where it helps most and leaves the final delivery in the form companies already know how to handle.
Final Thoughts on the Road Ahead
Cross-border payments will continue evolving. Stablecoins have already proven useful for certain corridors. The next step is making their conversion into everyday bank money as frictionless as possible. Platforms that solve that conversion cleanly while staying inside regulatory lines stand a good chance of becoming standard tools.
A7 International enters the international market with domestic volume already behind it and a clear product thesis. Whether it becomes a widely used option depends on consistent execution: reliable settlement times, accurate documentation, and continued adaptation to regulatory change. Early results will matter. So will the willingness of businesses to test the service with real invoices.
For now the offering is limited to specific assets and currencies, yet the underlying idea is broader. Pay with digital assets. Deliver conventional bank funds. Keep the process remote and transparent. That combination addresses a persistent pain point. If the platform delivers on the promise, more companies may discover that international settlements no longer need to feel like an obstacle course.
The real test will come in the months after launch as volume grows and different corridors are exercised. Users will compare actual experience against the claims of speed, cost, and simplicity. Those comparisons, more than any presentation, will decide how far the model travels. In a market still searching for better ways to move money across borders, a practical hybrid solution is worth watching closely.