

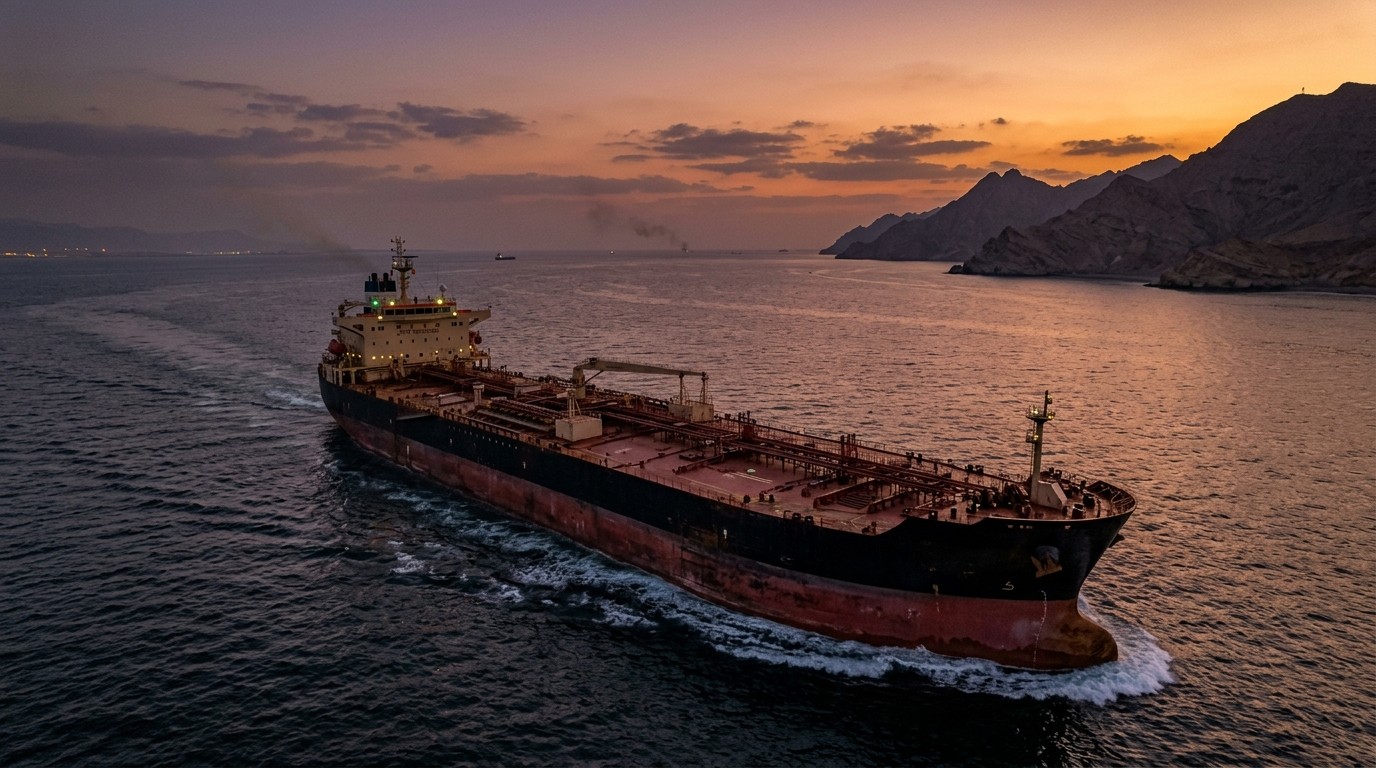

I still remember the first time I looked at a map of the Persian Gulf and realized just how narrow that passage really is. The Strait of Hormuz looks almost impossibly tight for the volume of oil and goods that squeeze through it every single day. When news broke this week that two Singapore-flagged container ships had been hit, one of them sinking after a projectile strike and fire, my first thought was simple: will anyone still dare to sail there? The answer, it turns out, is more complicated and far more interesting than a simple yes or no.
Why Commercial Vessels Keep Moving Through The Danger Zone
The latest incidents involving the GFS Pride and GFS Giselle have raised fresh alarms. One vessel went down. The other suffered damage. Crews from both ships made it out safely, which is the best possible news under the circumstances. Yet crossings through the strait did not stop. Numbers dropped, sure, but traffic continues. In the week ending mid-October the count fell to 131 from 176 the week before. That decline cannot be pinned only on these two attacks. Still, the pattern is clear enough: some operators are pulling back while others keep calculating the odds and deciding the risk remains worth taking.
What keeps them coming back? Money, mostly. Strong demand for Middle Eastern energy, especially from Asian buyers, creates a powerful pull. Tanker operators see opportunities that outweigh the elevated danger, at least for now. I’ve spoken with people in the industry over the years and the conversation almost always returns to the same point. Higher prices can cover higher insurance costs, higher war-risk premiums, and even the occasional hit. One regional official put it bluntly in a recent private exchange: sometimes you take losses, but the overall “Hormuz shuttle” still pays.
The Persistent Pull Of Energy Demand
Oil and gas still dominate the story. Asia needs those barrels. Refineries in several major economies continue to run hard. When crude prices climb because of the very risks that make the voyage scary, the math can actually improve for the shipowner willing to accept the danger. The vessels that keep sailing are often the ones prepared to self-insure or pay steep premiums. They treat the strait as a calculated gamble rather than an absolute no-go zone.
Container ships tell a slightly different tale. Most of the big global lines pulled out months ago when the broader conflict first flared. They have not returned. Only smaller regional operators still offer sporadic feeder services. That means the latest attacks on Singapore-flagged containers may not shake the overall container network as hard as they first appear. The majors already re-routed. Their networks adjusted. The ships still visible in the strait are more often tankers chasing energy cargoes than the large box ships that once dominated certain routes.
I don’t see in the short term that Singapore flagged ships or Singapore shipping companies would necessarily avoid taking the transit if there is an opportunity.
That assessment from a maritime security specialist in Singapore feels realistic. Opportunity still exists. Some owners will chase it. They will weigh crew safety, of course, but commercial incentives remain stubbornly present. The association that represents Singapore shipping interests made a similar point. These events are more likely to produce adjustments in trading patterns than a wholesale retreat from the region. Markets respond to shifts in supply and demand. Operators adapt rather than abandon the area entirely.
How Risk Premiums And Higher Prices Change The Equation
Consider the economics for a moment. A very large crude carrier sailing a “Hormuz shuttle” can earn more today than it did before the conflict began, even after factoring in the chance of damage. Higher oil prices act as a buffer. Self-insurance becomes a viable strategy for certain owners who decide the upside covers the downside. It is not a decision made lightly. No responsible operator treats crew lives as secondary. Yet the numbers can align in ways that keep the traffic moving.
I’ve found that the most revealing conversations happen when people speak off the record. One Gulf contact described roughly twenty large tankers running a continuous loop, accepting the occasional strike as a cost of doing business. The phrase “sometimes you get hits, but it is still worthwhile” stuck with me. It captures the cold arithmetic at work. Not every owner will make that calculation. Some will stay far away. Others will keep sailing and hope their luck holds.
What The Latest Numbers Actually Reveal
Crossings fell from 176 to 131 in a single week. That is a meaningful drop. It is not a collapse. Analysts who track vessel movements note that the decline began before the most recent attacks and cannot be blamed solely on them. Broader caution has been building for months. Still, the fact that more than a hundred ships continued to transit after two high-profile incidents tells you something important about the underlying commercial pressure.
Maritime risk specialists emphasize that Iran retains the ability to threaten commercial vessels. The danger is no longer limited to oil and gas tankers. Container ships, bulk carriers, and other vessel types can find themselves in the crosshairs. That reality has already reshaped network planning for the largest container operators. They stay out. Smaller players and energy-focused owners make different choices.
- Major container lines remain absent from the strait since the early months of the conflict
- Regional feeders continue limited and irregular services using smaller ships
- Tanker traffic persists because of strong Asian demand for crude and refined products
- War-risk insurance costs have risen sharply and now form a significant part of voyage economics
- Some operators treat the higher premiums as an acceptable cost of access to high-value cargoes
The picture is uneven. Energy flows continue under elevated risk. Container flows have largely found other paths. That divergence matters for anyone trying to understand how the situation might evolve.
The Shadow Of A Wider Escalation
Perhaps the most interesting aspect is what happens if the danger spreads beyond the strait itself. Right now the critical alternative ports for Gulf cargo sit in safer waters. Places such as Khorfakkan and Sohar have become vital lifelines for goods entering the region. If kinetic activity expands into the Gulf of Oman, those gateways could face disruption. Supply chains that have already adapted once would face a second, more painful adjustment.
Maritime advisors who study the region warn that a wider zone of conflict would cut off a significant portion of supplies to Gulf countries. The current workaround depends on those UAE and Omani ports remaining open and accessible. Any extension of attacks into that area would raise the stakes considerably. For the moment the focus stays on the narrow strait. That could change quickly.
In my view the industry is walking a tightrope. Operators keep sailing because the commercial case still holds for certain trades. Crews continue to board those ships because the companies they work for have judged the risk manageable under current conditions. Insurance markets price the danger and some owners pay the price. Governments watch and issue warnings. The whole system keeps functioning under stress rather than shutting down.
How Different Vessel Types Face Different Realities
Not every ship faces the same pressure. A very large crude carrier carrying millions of barrels of oil has different economics from a mid-sized container feeder. The crude carrier can earn enough in a single successful voyage to justify elevated risk premiums. The feeder may find the numbers less forgiving. That is one reason the big container operators stay away while certain tankers keep coming.
Singapore-flagged vessels sit in a particular position. The country maintains a significant shipping registry and a strong reputation for maritime safety. When two of its ships are hit in the same week, the incident carries symbolic weight. Yet specialists familiar with Singapore owners suggest they will not automatically withdraw. If a profitable opportunity appears, some will still take it. That pragmatic stance reflects the broader industry mood.
| Vessel Type | Current Approach | Key Driver |
| Large Crude Tankers | Continue selective transits | High oil prices and Asian demand |
| Major Container Lines | Avoid the strait entirely | Network redesign after early conflict |
| Regional Feeders | Sporadic limited services | Local cargo needs and smaller scale |
| Other Commercial Ships | Case-by-case decisions | Individual risk and reward calculations |
The table above simplifies a complex reality, but it captures the main split. Energy still pulls ships through. Container logistics has largely moved on. That split shapes the overall traffic picture and explains why the latest attacks have not emptied the strait.
Commercial Incentives Versus Crew Safety
Every operator I have ever discussed this with insists that crew safety remains the top priority. The statements from shipping associations repeat the same message. Decisions balance commercial considerations against security developments and the well-being of the people on board. In practice that balance can look different depending on the company, the cargo, and the specific risk assessment of the moment.
Some owners will refuse any voyage that requires a Hormuz transit under current conditions. Others will accept higher costs and proceed with enhanced security measures. The range of responses is wide. That variety itself is part of the story. There is no single industry position. There is a spectrum of risk tolerance shaped by individual balance sheets and risk appetites.
One subtle point often missed in broader coverage is the role of self-insurance. Certain owners with deep pockets or strong balance sheets can absorb a loss that would cripple a smaller player. When crude prices are elevated, those owners can treat occasional damage as a cost of accessing premium earnings. It is a hard-edged calculation. It is also one that keeps some ships moving when others stay in port.
Adjustments Rather Than Withdrawal
The official stance from shipping industry representatives in Singapore is worth noting carefully. Rather than signalling a broad withdrawal from the region, recent developments are more likely to produce adjustments to trading patterns. Markets respond to changes in the supply and demand of goods and energy. Operators will continue to weigh those commercial realities against the latest security picture.
That language feels measured and accurate. Withdrawal sounds dramatic. Adjustment is what usually happens in practice. Routes shift. Cargoes move through alternative ports. Some voyages simply become more expensive. The underlying trade does not vanish overnight. It finds new paths or accepts higher costs on the old ones.
I’ve watched similar patterns in other chokepoints over the years. When risk rises, traffic rarely stops completely. It slows, it adapts, it becomes more expensive, and then it continues in a new form. The Strait of Hormuz is following a familiar script so far. The open question is how far the risk can climb before the adaptation process itself breaks down.
Looking Ahead At Possible Turning Points
Further attacks could deter more operators. The impact would vary by vessel type and by each company’s internal risk assessment. Another high-profile sinking might push some of the remaining tankers to pause. An expansion of activity into the Gulf of Oman would raise the stakes for everyone, including the alternative ports that currently serve as workarounds.
For now the commercial incentives remain strong enough to keep a reduced but still significant volume of traffic moving. Strong Asian demand for oil provides the underlying pull. Higher prices help cover the elevated costs. Some owners are prepared to accept the residual risk. That combination explains why ships are still crossing even after this week’s attacks on Singapore vessels.
The situation remains fluid. One more serious incident could shift the balance. A period of relative calm could encourage more traffic to return. Operators will keep watching the same variables: the security picture, the price of oil, the cost of insurance, and the availability of alternative routes. Those factors will decide how many ships keep sailing the strait in the weeks and months ahead.
What strikes me most is the stubborn persistence of commercial logic in the face of clear danger. People sometimes assume that rising risk automatically empties a waterway. Reality is messier. When the cargo is valuable enough and the alternative routes are limited or costly, some ships will keep coming. The crews on those ships, the owners who send them, and the buyers waiting for the cargo all participate in a calculated judgment about acceptable risk. That judgment is being tested again this week. So far it has not collapsed.
The Human Element Behind The Numbers
Behind every transit number sits a group of seafarers who boarded a ship knowing the route carried elevated danger. Their safety remains the non-negotiable element in every serious discussion. When both crews from the recent attacks were reported safe, that outcome mattered more than any commercial calculation. Future decisions will continue to turn on whether companies believe they can protect the people they put on those vessels.
Shipping associations emphasize this point repeatedly. Operational choices balance commercial opportunity against security developments and crew welfare. The language is careful because the stakes are high. No one wants to appear to prioritize profit over people. At the same time, the industry cannot ignore the economic forces that keep certain voyages viable even under stress.
In practice that tension produces a range of company policies. Some owners have already decided the strait is off-limits for their fleets. Others continue selective voyages with enhanced precautions. The diversity of responses is itself a form of market adaptation. Different firms reach different conclusions about the same set of facts.
Why The Strait Still Matters So Much
Geography has not changed. The Strait of Hormuz remains one of the most important maritime chokepoints on the planet. A large share of the world’s seaborne oil still passes through those waters. That structural reality creates the commercial gravity that continues to pull ships despite the danger. Alternative routes exist but often add time, distance, and cost. For certain cargoes and certain buyers, the direct path still looks attractive even when risk premiums climb.
Asian demand for energy underpins much of the remaining traffic. Refineries need crude. Importers need product. When prices rise because of the very risks that make the voyage hazardous, the incentive for some owners actually strengthens. It is a feedback loop that keeps a portion of the fleet moving when pure safety considerations might suggest otherwise.
Container shipping has already demonstrated that networks can adapt. The majors redesigned their services months ago. They found other ways to serve the region. Energy trades face tighter constraints. Oil and gas still need to leave the Gulf. That difference in flexibility helps explain the split we see today between tanker traffic that continues and container traffic that largely does not.
Final Thoughts On A Still-Moving Waterway
The attacks on two Singapore ships this week were serious. One vessel sank. Another was damaged. The crews survived, which is the outcome everyone hoped for. Traffic through the strait declined but did not stop. Commercial incentives, especially in the energy sector, continue to outweigh the elevated risks for a portion of the industry. Major container lines stay away. Some regional operators and many tankers keep sailing.
Experts who follow the region closely do not expect a sudden, complete withdrawal. They expect continued adjustment. Trading patterns will shift. Costs will rise for certain voyages. Some owners will opt out while others stay in. The system as a whole will keep functioning under stress rather than grinding to a halt. That assessment feels realistic based on everything I have seen and heard.
The open question remains how much further the risk can rise before the remaining traffic thins out more dramatically. Another round of attacks, or an expansion of the danger zone into the Gulf of Oman, could change the calculation quickly. For the moment the commercial case still holds for enough operators to keep ships moving through one of the world’s most closely watched waterways. The strait is narrower than it looks on a map, and the pressures on it are greater than many people realize. Yet the ships keep coming. That simple fact tells you a great deal about how global trade actually works when risk and reward collide.
Whether that continues will depend on the next set of incidents, the next movement in oil prices, and the next round of decisions by owners who must weigh crew safety against commercial opportunity. The story is still unfolding. The traffic numbers next week will offer the first clear signal of how the industry is absorbing the latest shocks. Until then the strait remains open, contested, and stubbornly relevant to the energy flows that keep large parts of the world running.



