
Have you noticed how quickly the oil market can shift from cautious optimism to outright nervousness? Just when some traders thought the worst of the regional disruptions might be easing, two more tankers took hits off the Saudi coast and Brent crude closed the week above $110 a barrel for the first time since May. That kind of combination tends to grab attention, and for good reason.
What Happened Off The Saudi Coast And Why It Matters
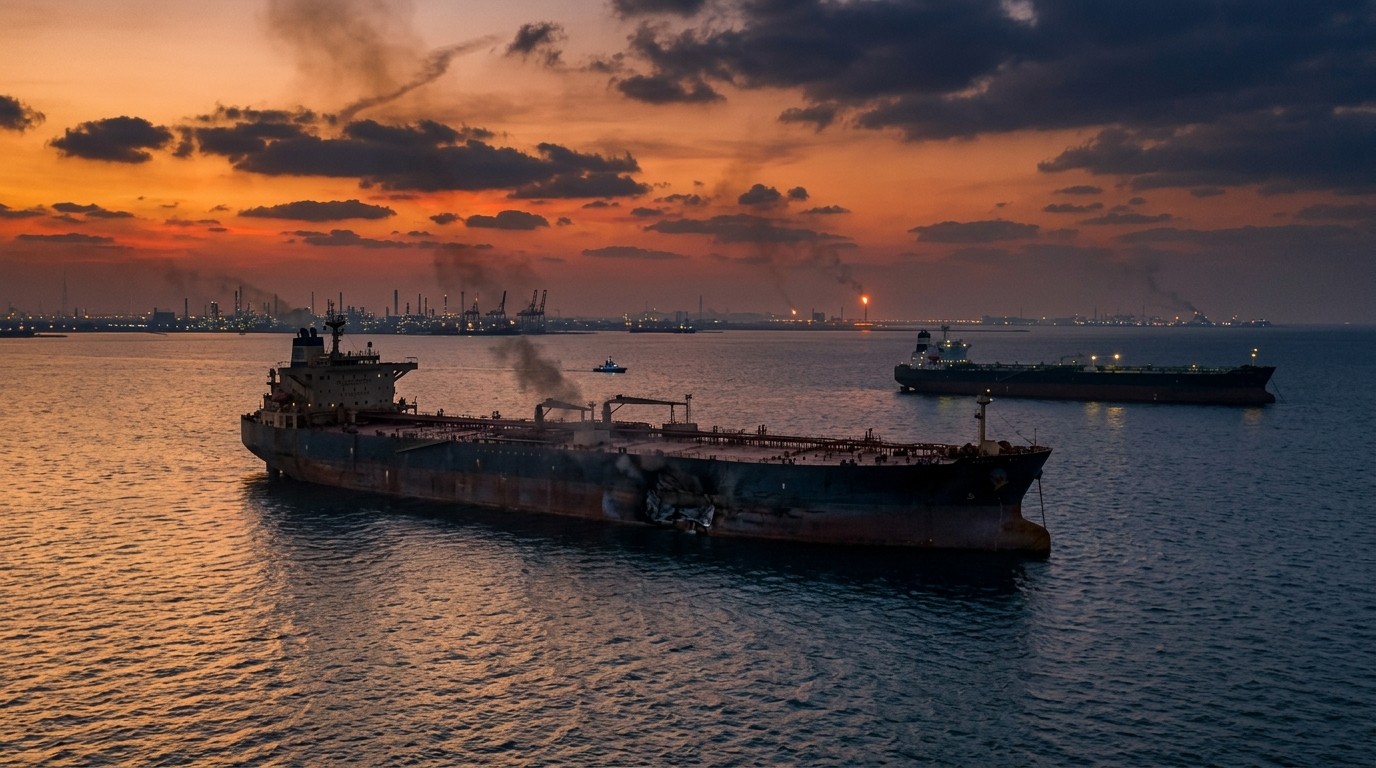
Late last week reports emerged of two separate incidents involving commercial tankers operating northeast of Jubail, a key industrial port city on Saudi Arabia’s eastern coast. The first vessel was struck by a rocket-propelled grenade launched from a small boat roughly 78 nautical miles from the port. Damage was confirmed but no one on board was hurt. The second tanker, positioned a bit closer at about 68 nautical miles out, was hit by an unidentified projectile. Its crew was safely evacuated.
These were not isolated curiosities. They fit into a broader pattern of low-level but persistent pressure on energy shipping lanes. I’ve been following these developments for a while now, and what stands out is the growing comfort some actors seem to feel in operating closer to major shipping routes. When small boats start firing RPGs at tankers in the central Persian Gulf, the risk calculus for every commercial operator changes.
How The Market Reacted In Real Time
Brent crude responded almost immediately. The global benchmark climbed 3.7 percent on Friday alone, locking in a second straight week of gains. Traders who had been sitting on the sidelines began adding bullish positions heading into the weekend. That kind of price action does not happen in a vacuum. It reflects genuine concern that the physical risks to supply are expanding at the same time seasonal demand is set to rise.
Diesel futures settled near $4.90 a gallon in New York while gasoline also moved higher. Both products are now trading at their strongest levels for this time of year. That detail matters more than many casual observers realize. When refined products start outrunning the crude complex, it often signals that the real bottleneck sits further downstream in the refining system.
The Wider Web Of Regional Pressure
The tanker incidents did not occur in isolation. Iran-backed groups have continued launching missiles and drones toward Saudi targets. Activity around the Strait of Hormuz remains elevated. At the same time, Ukrainian forces keep hitting Russian energy infrastructure. The combined effect is a market that has to price multiple overlapping risks rather than a single neat narrative.
One modest positive this week was the volume of oil that still managed to move through the key waterway. More than 100 million barrels passed through, bringing flows close to levels seen before the latest round of tensions. That is encouraging on the surface. Yet it does little to ease worries about what happens if the situation deteriorates further.
After a brief reprieve, the oil market is having to price risk back in, particularly heading into the weekend.
That assessment from a senior energy trader captures the mood accurately. Markets hate uncertainty, and the current environment is full of it. The question is no longer whether risk exists. It is how much of that risk is already reflected in the price and how much remains underpriced.
Why Diesel Is The Real Story Beneath The Headlines
Crude prices grab the headlines, but the tighter story sits with middle distillates. Restrictions on Russian diesel have forced refiners elsewhere to run harder and process more crude simply to keep product markets supplied. Inventories in the West have been drawn down for months. One major trading house executive recently noted that there are essentially no more inventories left to drain in Western markets.
That observation should give anyone pause. When spare barrels of diesel are gone, any new disruption carries a higher multiplier effect. The International Energy Agency has already flagged that the diesel squeeze is likely to persist through at least the first half of next year. Goldman analysts have been saying something similar. In my view, those calls look increasingly realistic rather than alarmist.
Winter demand is about to ramp up across the Northern Hemisphere. Heating oil and diesel compete for the same molecules in many refining systems. If cold weather arrives on schedule, the pressure on already thin stocks will intensify. That is the quiet risk sitting underneath the more dramatic tanker headlines.
The Hormuz Chokepoint Remains The Ultimate Wild Card
Everyone in the energy business knows the numbers. A significant share of global seaborne oil still moves through the Strait of Hormuz. Even temporary interruptions can send prices sharply higher. The current environment has revived talk of tail risks that once seemed remote. Some market participants have begun discussing scenarios in which crude could approach extreme levels if a hard shutdown of the waterway materializes.
I do not believe such an outcome is the base case. Most actors in the region still appear to prefer controlled pressure over all-out escalation. Yet the threshold for miscalculation feels lower than it did even a few months ago. When small boats are launching RPGs at tankers in relatively open water, the margin for error shrinks.
How Traders Are Positioning Ahead Of Winter
Positioning data has shown a clear shift toward more bullish crude exposure. That makes sense given the combination of geopolitical noise and seasonal demand. What is less clear is how much further the market can stretch before physical balances start to reassert themselves.
Some of the more measured voices in the industry point out that high prices eventually destroy demand and incentivize additional supply. That process takes time, however. In the short run, the market can remain tighter than pure fundamentals might suggest, especially when logistics and insurance costs keep rising for vessels operating in the region.
- Insurance premiums for Gulf transit have climbed
- Some owners are already rerouting vessels on longer paths
- Charter rates for certain vessel classes have firmed
- Refiners are competing more aggressively for available crude
These secondary effects often matter as much as the headline incidents themselves. Higher operating costs eventually filter into the price of the final product that consumers and businesses pay.
Looking At The Refining Bottleneck More Closely
Global refining capacity has been under strain for several years. Pandemic-era closures removed significant capacity that has never fully returned. New projects take years to complete and face their own set of political and environmental hurdles. The result is a system with less spare capacity than many assumed was still available.
When Russian product flows are restricted, that missing capacity becomes more visible. European and Asian refiners have had to adjust crude slates and operating rates. In some cases they are running less optimally simply to maximize diesel and jet fuel output. That kind of operational stress is not sustainable indefinitely, yet it is the reality the market faces heading into the colder months.
Perhaps the most interesting aspect is how little public attention this refining constraint still receives compared with the more dramatic geopolitical headlines. Tanker attacks make for vivid news. The slow grind of a refining system running near its limits is less cinematic but ultimately more consequential for everyday fuel prices.
What History Suggests About Similar Episodes
Markets have lived through periods of elevated Gulf risk before. In most cases the physical flows proved more resilient than the initial price spikes suggested. Yet each episode leaves its own imprint on insurance markets, shipping patterns and inventory policies. Companies that get burned once tend to become more conservative the next time around.
That institutional memory is already visible. Some charterers are building extra time into voyage planning. Others are exploring alternative supply sources even when they cost more. These adjustments rarely reverse quickly once they take hold. They become part of the new baseline cost structure for moving oil.
The Demand Side Of The Equation Is Not Standing Still
While supply risks dominate the conversation, demand continues to evolve. Jet fuel recovery remains incomplete in some regions but is still improving. Petrochemical demand has been uneven. The bigger near-term swing factor remains winter heating needs across Europe, North America and parts of Asia.
A colder-than-average winter would tighten balances further. A milder season would offer some relief. Weather forecasts at this stage of the year still carry wide uncertainty bands, which itself becomes another source of market volatility. Traders have to hold positions through that uncertainty, and the premium they demand for doing so tends to keep prices elevated.
How Far Could Prices Travel If Risks Escalate
Some of the more aggressive forecasts circulating among trading desks point to the possibility of much higher prices if a major disruption hits Hormuz or if refining problems deepen. Those scenarios remain low probability for now. Still, the asymmetry is real. Downside from current levels requires a clear de-escalation that is not yet visible. Upside requires only one or two additional incidents that further tighten already stretched logistics.
In my experience, markets often underestimate the speed with which sentiment can shift once a threshold is crossed. The move above $110 already shows that threshold is closer than it appeared a few weeks ago. Whether the next leg higher materializes will depend on whether the recent tanker attacks remain isolated or become part of a more sustained campaign.
Practical Implications For Different Market Participants
For refiners the priority is securing reliable crude feedstock and protecting margins on middle distillates. For traders the focus is managing inventory risk and basis exposure. For end users the concern is simpler: higher and more volatile fuel costs at a time when many budgets are already stretched.
Airlines, trucking companies and shipping operators are all watching the same set of variables. Hedging programs that looked adequate a few months ago may need recalibration. The same is true for industrial consumers who rely on diesel or residual fuel oil.
- Review existing hedge coverage against current forward curves
- Assess exposure to potential freight and insurance cost spikes
- Consider alternative supply routes or product grades where feasible
- Build contingency plans for possible short-term product shortages
None of these steps is revolutionary. Most large operators already have frameworks in place. The difference now is the higher probability that those frameworks will be tested in the coming months.
The Information Fog Around Attribution
One persistent challenge in these situations is the difficulty of firm attribution. Claims and counter-claims circulate quickly. Independent verification often lags. Markets tend to price the worst reasonable interpretation until clearer information emerges. That dynamic can amplify short-term volatility even when the physical impact of any single incident remains limited.
The latest tanker strikes fit this pattern. Early reports described the methods and approximate locations with reasonable consistency. Responsibility remains harder to pin down with public certainty. Until that fog lifts, risk premiums are likely to stay elevated.
Seasonal Timing Makes The Current Window Especially Sensitive
Energy markets always feel more fragile heading into the Northern Hemisphere winter. Inventories that look comfortable in August can look thin by January. Refinery maintenance schedules often cluster in the shoulder seasons, reducing flexibility just when demand starts to climb. Adding geopolitical friction on top of that seasonal pattern raises the stakes.
I have found that the market’s tolerance for disruption shrinks noticeably once heating demand becomes a daily factor rather than a distant forecast. We are approaching that transition now. The next few weeks of weather and incident data will carry more weight than they would in the middle of summer.
Longer-Term Questions The Market Still Needs To Answer
Beyond the immediate price action, several structural questions remain open. How much additional refining capacity will actually come online over the next two to three years? Will shipping companies permanently alter their risk tolerance for Gulf routes? How quickly can alternative export routes from other producing regions expand?
These questions will not be resolved by a single week’s price move. They will shape the medium-term balance of the oil market long after the current set of headlines fades. For now the market is focused on the nearer-term risks, and those risks have clearly increased.
The combination of two tanker attacks, a move above $110 in Brent, and an already tight diesel market creates a backdrop that feels distinctly different from the relative calm of earlier months. Whether this proves to be a temporary scare or the start of a more prolonged period of elevated risk remains to be seen. What is already clear is that the margin for error has narrowed, and market participants are adjusting accordingly.
In the end, energy markets reward those who stay alert to shifting probabilities rather than those who wait for perfect clarity. The latest incidents off the Saudi coast have shifted those probabilities in a more cautious direction. How far that shift ultimately travels will depend on events that have not yet occurred, which is precisely why the market remains so attentive.
For anyone watching fuel costs, refining margins or broader inflation trends, the message is straightforward. The period of relatively contained risk premiums appears to be over for the moment. The next chapter will be written by a combination of weather, diplomacy and the willingness of various actors to keep testing the boundaries of what commercial shipping will tolerate. That chapter is only beginning.