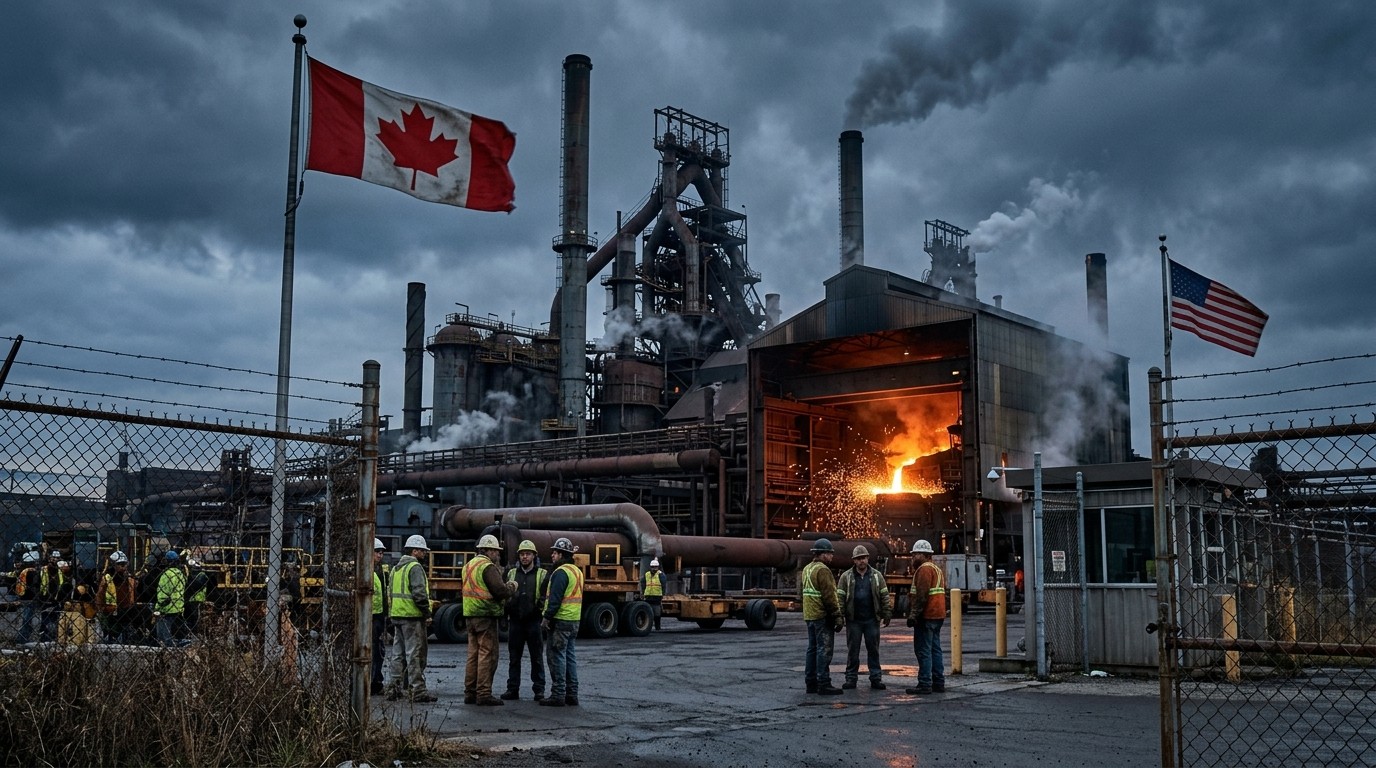

I’ve been watching the back-and-forth between Ottawa and major manufacturers for months now, and this latest development still managed to catch me off guard. A U.S.-owned steel company that invested heavily in Canadian operations is being told it cannot lay off workers even when tariffs make those jobs financially unsustainable. The government is reviewing legal options, including possible fines or forced asset sales, because the company refused to reverse planned cuts. It feels less like standard regulatory oversight and more like an attempt to rewrite basic business realities.
Why This Standoff Matters Right Now
The core issue is straightforward yet deeply complicated. Cleveland-Cliffs, the American parent of Canadian steelmaker Stelco, plans to reduce roughly 500 positions. These cuts come after trade measures disrupted the cost structure that once made Canadian production competitive. Ottawa’s response has been to point to earlier commitments the company made under investment rules and insist those promises still bind the firm regardless of changed market conditions.
In my view, that stance reveals a fundamental tension. Governments want the jobs and capital that foreign investment brings. They also want the political credit for protecting employment. When the two goals collide under pressure, the pressure often falls on the company rather than on the policy choices that created the pressure in the first place.
The Numbers Behind Canada’s Exposure
Canada sends more than three-quarters of its exports to the United States. Exports themselves account for roughly one-third of Canadian economic output. By comparison, the United States sells a much smaller share of its goods north of the border, and overall exports play a lighter role in American GDP. The imbalance is not abstract. It means disruptions in cross-border commerce hit Canadian factories, workers, and provincial budgets far harder than they hit the larger U.S. economy.
Recent employment data already reflect the strain. Tens of thousands of jobs disappeared in consecutive months, many linked to manufacturers scaling back or relocating capacity. Steel is only one sector, yet it carries symbolic weight. When a high-profile producer begins shedding staff, the political cost rises quickly for any administration that campaigned on job growth.
I’ve found that these statistics rarely stay confined to spreadsheets. They show up in local communities, in union halls, and eventually in election messaging. That is why the current confrontation feels larger than one company’s payroll decision.
How Investment Commitments Became a Lever
When the U.S. firm acquired the Canadian steel assets, it agreed to maintain certain employment levels for a defined period. Those undertakings covered unionized roles and the bulk of non-union positions. Officials now argue that a shift in market conditions or a pure business decision cannot excuse non-compliance. The language is firm: everything remains on the table.
Possible measures include financial penalties, court orders compelling continued operations, or even a requirement to divest Canadian assets. The last option carries its own irony. Forcing a sale could trigger deeper job losses than the original restructuring plan. Yet the threat itself serves as leverage.
A change in market conditions cannot justify walking away from employment promises made to secure regulatory approval.
That position is understandable from a political standpoint. It is harder to defend from an economic one. Tariffs alter input costs, customer demand, and relative competitiveness almost overnight. Expecting a private firm to absorb those costs indefinitely while competitors adjust is asking it to operate as a quasi-public utility.
The Broader Pattern of Pressure
This episode fits a longer pattern. Successive Canadian governments have leaned on proximity to the large U.S. consumer market while maintaining policies that sometimes disadvantaged American producers. When the larger partner began using tariffs more assertively, the reaction in Ottawa mixed defiance with attempts to lock in existing advantages. The steel dispute is simply the most visible current example.
Companies that expanded in Canada under earlier assumptions now face a different cost environment. Some are shifting production, others are mothballing capacity, and a few are exploring legal avenues of their own. The government’s message, however, remains consistent: the jobs stay, or consequences follow.
Perhaps the most interesting aspect is how quickly the conversation moved from trade negotiation to domestic enforcement. Instead of focusing primarily on securing better market access or adjusting domestic policy, attention turned to compelling one firm to keep workers on the payroll. That sequence says a great deal about priorities under stress.
What the Layoffs Actually Represent
The planned reductions at the Canadian steel operations are not abstract numbers. They represent real people in real communities who expected relative stability after a major ownership change. At the same time, they also represent the arithmetic of running a capital-intensive business when selling prices and input costs move against you.
Management has already started implementing the cuts. The government continues to review the company’s formal response and says it remains open to discussion. That openness is welcome, yet the public framing has already raised the stakes. Any climb-down now risks looking like weakness; any escalation risks looking heavy-handed.
In my experience following these kinds of standoffs, the middle ground tends to shrink once legal options enter the conversation. Both sides dig in, and the practical options narrow to either a negotiated compromise that both can claim as victory or a prolonged process that damages the underlying business.
Economic Reality Versus Political Messaging
Leaders in Canada have at times suggested that alternative trading partners can replace lost U.S. volume. The logistics, transportation costs, and customer relationships involved make that substitution far more difficult than the rhetoric implies. No other single market offers the same combination of size, proximity, and integrated supply chains.
Meanwhile, the domestic political narrative emphasizes resilience and the search for partners who “share values.” Those phrases poll well. They do less to fill order books or keep blast furnaces running at efficient rates. The gap between messaging and operational reality is where the current friction lives.
I keep returning to a simple observation: when a country depends so heavily on one customer, the customer’s policy shifts inevitably force hard choices. Pretending otherwise only postpones the adjustment and raises the eventual cost.
Possible Paths Forward
Several outcomes remain possible. A quiet negotiation could produce a temporary support package or a revised employment plan that both sides accept. Courts could become involved, creating precedent for future foreign investment reviews. The company could accelerate asset sales or further capacity reductions. Or the broader trade environment could improve enough to restore some of the lost competitiveness.
None of these paths is cost-free. Support packages carry fiscal implications. Litigation creates uncertainty for other investors watching the process. Accelerated cuts deepen the immediate employment hit. Even an improved trade climate would take time to reverse decisions already set in motion.
- Negotiated temporary relief that preserves core operations
- Formal legal proceedings under investment legislation
- Further restructuring or potential divestiture
- Broader policy adjustments on the trade front
Whatever path emerges, the episode has already illustrated the limits of trying to freeze employment levels by regulatory decree when underlying economics shift.
Lessons for Investors and Policymakers
Foreign investors will read this situation carefully. Commitments made at the time of acquisition can become binding long after the assumptions behind them have changed. That knowledge will factor into future capital allocation decisions, risk premiums, and the willingness to expand in the same jurisdiction.
Policymakers face a different set of lessons. Protecting jobs is a legitimate goal. Doing so by compelling private firms to ignore market signals risks reducing the very investment that creates jobs in the first place. The short-term political benefit can carry longer-term economic costs.
I’ve noticed that the most durable industrial strategies tend to focus on competitiveness rather than on locking in headcount. Training, infrastructure, energy costs, and predictable regulation matter more over a decade than any single enforcement action.
The Human Dimension Often Overlooked
Behind the legal language and the trade statistics sit workers who planned their lives around steady industrial employment. Sudden layoffs disrupt more than paycheques. They affect local suppliers, municipal tax bases, and family stability. Governments feel pressure to respond precisely because those effects are visible and concentrated.
At the same time, companies cannot run indefinitely at a loss without jeopardizing the remaining jobs and the capital that supports them. Balancing those realities requires more than public statements. It requires realistic assessment of what tariffs actually change and what policy tools can productively address.
The current approach leans heavily on enforcement of past undertakings. Whether that proves sufficient, or whether it simply prolongs uncertainty, will become clearer in the coming weeks.
Looking Further Ahead
Trade relationships of this scale rarely reset overnight. Adjustments occur through a series of smaller decisions by companies, workers, and governments. The steel confrontation is one of those decisions made visible. Others are already underway in different sectors as firms reassess North American footprints.
Some capacity will remain in Canada because of specific advantages in location, workforce, or product mix. Other capacity will migrate. The speed and scale of that migration will depend partly on how confrontations like the present one are resolved.
In the end, the fundamental arithmetic does not change. An economy that sells the majority of its exports to one partner remains sensitive to that partner’s policy choices. Attempts to compel individual firms to absorb the consequences indefinitely tend to meet practical limits. The sooner that recognition shapes the response, the lower the cumulative cost is likely to be.
For now, the government continues to review its options while the company proceeds with its planned reductions. The gap between those two positions is where the real story sits. How that gap closes, or fails to close, will say a great deal about the next chapter of cross-border economic relations.
Watching the process unfold, I keep thinking about the ordinary tension between political timelines and commercial ones. Elections arrive on fixed schedules. Markets move continuously. When the two collide, the resulting friction can be instructive, even when it is uncomfortable. This particular friction is already teaching lessons that extend well beyond one steel producer and a few hundred positions.
The coming months will show whether dialogue produces a workable middle path or whether the confrontation hardens into a longer legal and commercial dispute. Either way, the underlying pressures created by the changed trade environment are unlikely to disappear quickly. Companies will continue adapting. Governments will continue responding. And the workers caught in the middle will continue measuring the distance between official statements and the reality on the shop floor.
That distance, more than any single threat or counter-move, may prove the most lasting feature of the current moment.