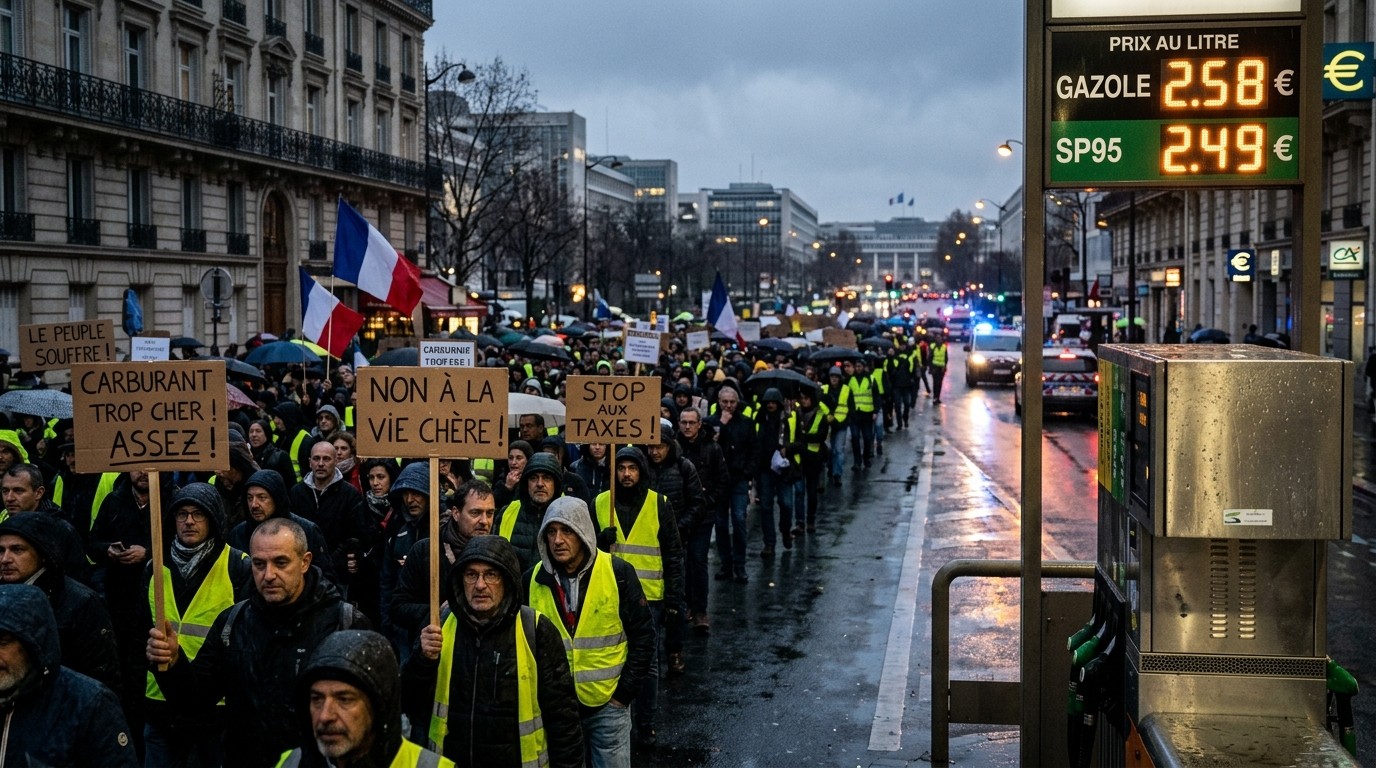

Have you ever filled up your tank and felt that quiet sting of watching the numbers climb faster than your paycheck seems to keep up? Right now that feeling is hitting hard across France. Average retail gasoline prices have climbed to roughly 2.39 dollars per liter, a level that sits about 50 percent above the global average. For ordinary workers earning around 2,950 dollars a month, that single fill-up of a standard 40-liter tank can swallow nearly 70 percent of a full day’s wages. It is no surprise that streets are filling with protesters who say the cost of simply getting to work is becoming unsustainable.
Why Fuel Costs Are Crushing Everyday Budgets In France
The numbers alone tell a story that feels almost personal. An average French worker brings home about 134 dollars for each of the 22 working days in a typical month. Spending close to 96 dollars just to fill the tank leaves very little room for everything else that life demands. Food, rent, school supplies, the occasional night out—those everyday items start competing for the same limited cash. Toward the end of the month the pressure often becomes visible. Reports suggest a growing number of employees are asking for payroll advances simply to bridge the final days until the next paycheck arrives.
I have watched similar patterns in other high-cost economies, and the pattern rarely stays contained. When transportation costs rise this sharply, people begin cutting back on discretionary spending. Local shops feel the squeeze. Small businesses that rely on daily foot traffic notice fewer customers. The frustration then moves from private conversations into public spaces. Protests that start around fuel quickly expand into broader complaints about the overall cost of living. That is exactly the dynamic unfolding on French streets right now.
The Daily Math That Leaves Households Short
Let us walk through the arithmetic that many families face. A 40-liter tank at current prices costs nearly 96 dollars. For someone earning 134 dollars a day, that single transaction removes the majority of their daily income. Multiply the same expense across a month of commuting, and the portion of household income devoted to fuel becomes striking. In many cases it rivals or even exceeds the share spent on housing in lower-cost regions. The result is a slow tightening of cash flow that becomes most noticeable in the final week of each pay cycle.
Some workers have begun requesting early access to wages. Others are simply driving less, which can limit job opportunities or force longer, more complicated public transport routes. The cumulative effect is a quieter form of economic stress that does not always make headlines but shapes daily decisions for thousands of households. When fuel becomes this expensive relative to income, the sense of fairness erodes. People start asking why the price at the pump keeps rising while their own earnings remain largely static.
How Protests Reflect Deeper Living Cost Pressures
The demonstrations visible across French cities are not only about gasoline. Fuel sits at the center of frustration because it is impossible to ignore. Every trip to the station becomes a reminder of wider price pressures. Food inflation, energy bills, and housing costs have already stretched many budgets thin. Adding a sharply higher fuel bill pushes the total burden past what many consider manageable. The streets then become the place where that accumulated pressure finds expression.
In my view, the intensity of the current protests signals more than temporary anger. It points to a structural mismatch between the cost of essential goods and the income levels of large parts of the working population. When filling a tank consumes nearly three-quarters of a day’s wage, the social contract starts to feel strained. Governments that fail to address that gap often find the political temperature rising faster than they expected.
France Fiscal Deficit Limits Room For Quick Relief
Addressing public discontent usually requires money—targeted subsidies, temporary tax cuts, or direct support for lower-income households. France currently has limited space for such measures. The fiscal deficit is projected to reach 5.4 percent of gross domestic product this year, well above the European Union’s 3 percent ceiling. At the same time, public debt has climbed to approximately 3.6 trillion euros, equivalent to roughly 119 percent of GDP. That ratio marks the highest level recorded since the mid-1940s.
These figures matter because they constrain policy choices. High deficits and elevated debt make it harder to introduce large new spending programs without further alarming investors. The European Central Bank has repeatedly stressed its independence and the importance of market credibility. That stance reduces the likelihood of an easy bailout if French borrowing costs rise sharply. In practical terms, the government must find ways to respond to street pressure while operating inside tighter fiscal boundaries than many citizens might prefer.
The tools available were designed during earlier periods of stress, yet any intervention would still depend on clear political commitment to medium-term adjustment.
Analysts note that the current predicament could eventually force more ambitious structural changes. Spending restraint, carefully designed tax adjustments, and faster progress toward deeper European capital market integration are all being discussed as possible paths forward. Whether those discussions turn into concrete action remains an open question, but the fiscal arithmetic leaves little room for pure delay.
Public Debt Levels And The Maturity Profile
France’s public debt stock of 3.6 trillion euros is large by any standard. At 119 percent of GDP it exceeds the ratios seen in several other major European economies. Yet the maturity structure offers some breathing room. The average residual maturity stands at roughly eight years and 158 days. Redemptions are relatively well staggered rather than clustered into a short window. That distribution reduces the risk of an immediate liquidity crunch caused by a sudden wall of maturing bonds.
Investors still watch the situation closely. The 10-year French sovereign yield briefly approached 5 percent, a level not seen since the early 2000s. The move reflected both fiscal concerns and broader political uncertainty. Higher yields raise the cost of new borrowing and of rolling over existing debt. Even with a favorable maturity profile, sustained elevation in borrowing costs can gradually tighten the fiscal envelope further.
One senior investment officer observed that an immediate European Central Bank rescue is not the base case. The existing toolkit could be activated if needed, but the absence of a concentrated maturity wall removes the most urgent form of pressure. The more relevant question is whether political leaders can deliver a credible path back toward the 3 percent deficit target over the coming years.
Political Uncertainty And Market Reaction
Markets dislike uncertainty almost as much as they dislike large deficits. Recent movements in French bond yields have been driven in part by questions about whether a budget targeting a 5 percent deficit will ultimately be adopted and implemented. Political debate over the precise mix of spending cuts and revenue measures continues. Each delay or public disagreement tends to keep risk premia elevated.
The Governor of the Bank of France has expressed confidence that a return to a 3 percent deficit by 2029 remains achievable. That timeline is longer than some market participants would prefer, yet it provides a concrete reference point. The key variable is credibility. If investors believe the trajectory is realistic and backed by genuine political will, yields can stabilize even while absolute debt levels remain high. If doubts persist, the premium demanded for holding French debt may stay elevated for longer.
I find the interplay between street protests and market pricing particularly interesting. Public frustration over living costs can push governments toward short-term relief measures that temporarily worsen the deficit. Markets then react by demanding higher yields, which in turn raises the cost of any future support. Breaking that feedback loop requires careful sequencing—visible progress on fiscal adjustment combined with targeted help for the households feeling the sharpest pressure.
Possible Paths Toward Fiscal Stabilization
Several avenues are under discussion. Spending reviews that identify lower-priority outlays could free resources without immediate tax increases. Targeted efficiency gains in public administration often deliver gradual savings. On the revenue side, base-broadening measures that close loopholes tend to be less distortionary than across-the-board rate hikes. Neither path is painless, and both require political capital that is currently scarce.
At the European level, faster progress on a genuine Capital Markets Union could improve the overall funding environment. Deeper and more liquid markets would make it easier for governments and private borrowers alike to raise capital on favorable terms. France has long supported such integration. Turning that support into concrete institutional steps could deliver medium-term benefits that ease some of the current pressure.
- Careful prioritization of public spending to protect essential services while trimming less critical programs
- Revenue measures focused on broadening the tax base rather than sharp rate increases
- Accelerated European initiatives that improve capital market depth and resilience
- Clear multi-year deficit reduction targets backed by transparent monitoring
None of these options will eliminate the short-term pain felt at the fuel pump. They can, however, create a more sustainable fiscal foundation that eventually allows greater flexibility when external shocks hit. The alternative—continued high deficits financed at rising yields—gradually narrows the room for any future response.
Household Coping Strategies And Longer-Term Implications
While policymakers debate the larger picture, households are already adjusting. Some are consolidating trips, carpooling more frequently, or shifting toward smaller vehicles when replacement becomes necessary. Others are exploring public transport options even when the routes are less convenient. A portion of the workforce is requesting schedule flexibility that reduces commuting days. These micro-adjustments add up. They also highlight how energy costs influence labor market behavior and urban mobility patterns.
Over a longer horizon the current episode may accelerate interest in alternative energy solutions and more efficient transport systems. Higher relative prices create stronger incentives for both consumers and businesses to seek substitutes. Whether those incentives translate into faster adoption depends on the availability of practical, affordable options and on the policy framework surrounding them.
From a purely observational standpoint, the French experience underscores a broader European tension. High public debt ratios limit the ability of governments to cushion citizens against sharp price increases. At the same time, visible hardship fuels political pressure for exactly that kind of cushion. Resolving the tension requires a combination of fiscal discipline and carefully designed social support that does not undermine the discipline itself. Achieving both at once is rarely simple.
Investor Perspective On French Sovereign Risk
For those watching bond markets, the recent rise in French yields serves as a reminder that even large, developed economies can face sudden shifts in risk perception. The move toward 5 percent on the 10-year note was brief, yet it illustrated how quickly sentiment can change when fiscal numbers and political noise coincide. The staggered maturity profile remains a supportive technical factor. Still, sustained higher funding costs would gradually increase the interest burden within the budget.
Perhaps the most interesting aspect is the potential catalytic effect of the current stress. Periods of elevated pressure sometimes produce the political conditions needed for reforms that prove difficult in calmer times. Spending reviews, tax base reforms, and European-level capital market initiatives have all been discussed for years. The combination of street protests and market scrutiny may finally push some of those ideas from the discussion stage into actual implementation.
Of course, outcomes are never guaranteed. Political fragmentation can just as easily produce stalemate. The coming months will reveal whether the pressure generates constructive adjustment or prolonged uncertainty. For households currently stretching to cover fuel and other essentials, the distinction between those two paths will matter in very concrete ways.
Looking Ahead At Living Costs And Policy Choices
Fuel prices alone will not determine France’s economic trajectory, yet they have become a powerful symbol of wider cost-of-living pressures. When a basic necessity consumes such a large share of daily earnings, the sense of economic security weakens. Restoring that sense requires both immediate attention to household budgets and a credible medium-term plan for public finances.
The deficit projection of 5.4 percent of GDP and the debt ratio near 119 percent leave limited room for error. At the same time, the absence of an imminent maturity wall provides a window in which adjustment can occur without crisis conditions. Whether that window is used productively depends on political choices still being formed. Clear communication of a realistic path back toward the European fiscal reference values would help stabilize expectations. Targeted measures that ease the most acute household pressures could reduce the intensity of street protests without permanently expanding the deficit.
In the end, the story unfolding in France is about more than one commodity price. It is about the interaction between everyday living costs, public finance constraints, and the confidence of both citizens and investors. Getting that interaction right is never easy. Getting it wrong carries costs that extend well beyond the price displayed at the pump. For now, the protests continue, the fiscal numbers remain elevated, and the search for workable solutions goes on. The coming period will show which path the country ultimately chooses.
One practical observation worth keeping in mind is that high relative fuel costs tend to accelerate behavioral change even before formal policy shifts occur. People adapt because they must. Those adaptations—fewer discretionary trips, greater interest in efficiency, altered commuting patterns—feed back into the broader economy. Policymakers who understand that dynamic can design supporting measures that reinforce rather than fight the adjustments already underway. That kind of alignment between private behavior and public strategy often produces more durable results than either side acting in isolation.
The situation also highlights the value of transparent data. When households can see how their own fuel expenses compare with national averages and with wage growth, the debate becomes more grounded. When investors can track the maturity profile and the pace of deficit reduction against clear benchmarks, risk premia tend to settle more quickly. Information alone does not solve fiscal or social challenges, yet it reduces the fog in which both protests and market volatility often intensify.
As the weeks ahead unfold, attention will remain fixed on two parallel tracks: the concrete steps taken to ease the immediate burden on household budgets and the credibility of the longer-term fiscal trajectory. Progress on either front can ease pressure on the other. Delay on both risks keeping both street tension and market caution elevated for longer than necessary. The numbers are already clear. The choices that follow will determine how the story is remembered.