

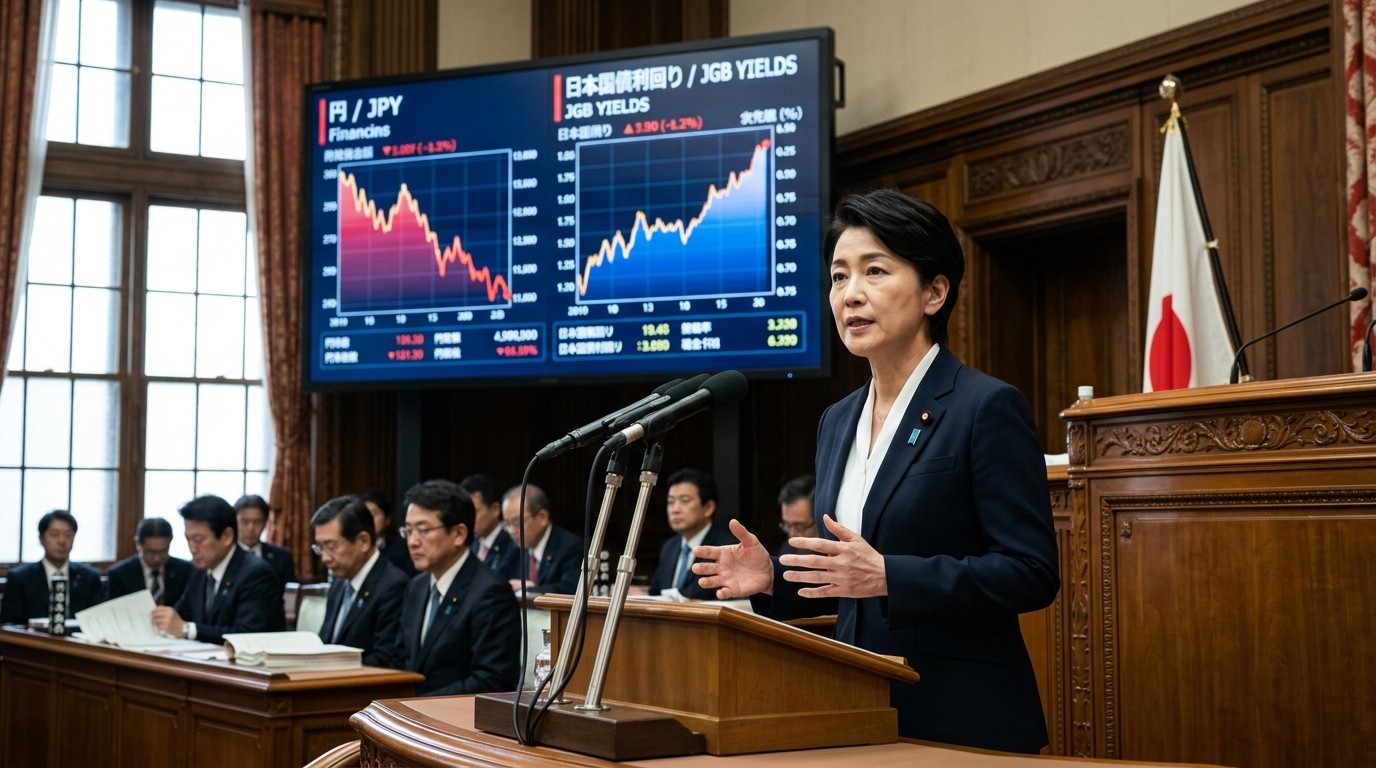

Have you ever watched a leader stand in front of parliament and simply refuse to own the problems everyone else is pointing at? That is exactly what happened in Tokyo this week when Japan’s Prime Minister faced pointed questions about the sliding yen and climbing interest rates. She did not dodge. She did not soft-pedal. She looked straight at the criticism and said, in essence, this is not on me.
Why The Yen And Bond Yields Suddenly Matter So Much
The Japanese currency has been on a rough ride. It recently touched levels not seen since the mid-1980s. At the same time, long-term Japanese government bond yields have climbed to heights that traders have not witnessed in decades. For ordinary people this might sound like distant market chatter, yet the combination hits everything from import prices to the cost of servicing public debt. When the yen weakens, imported energy and food become more expensive. When yields rise, the government pays more to borrow. Both trends create pressure that politicians cannot ignore.
I have followed these markets for years and the current setup feels different from past episodes. In earlier decades Japan could lean on ultra-low rates and a relatively stable currency. That comfort zone is gone. The central bank has been gradually normalizing policy, lifting its key rate and stepping back from aggressive bond purchases. Meanwhile fiscal plans keep evolving. The result is a market that is testing every statement that comes out of Tokyo.
The Prime Minister’s Direct Rejection Of Blame
Standing in parliament, the Prime Minister addressed an opposition lawmaker who raised the issue of a second supplementary budget. The question was not casual. It touched the sensitive link between spending plans, debt issuance, and market reactions. Her reply was unambiguous. She has heard the phrases “Takaichi’s weak yen” and “Takaichi’s high interest rates” repeated often enough. She rejects both labels outright.
I have been repeatedly criticized for those claims, but I clearly deny that.
That kind of plain language is rare in political speeches. Most leaders prefer carefully hedged sentences. Here the message was simple: the current path of the yen and the rise in yields cannot be pinned on her administration alone. She went further and offered her own theory of what would actually help the currency. Build a strong economy, she argued, and confidence in the yen will follow. Confidence is not created by talking about exchange rates. It grows when companies invest, when wages rise in real terms, and when growth looks sustainable.
On the bond side she was equally clear. The government intends to control the volume of new issuance appropriately. That sentence carries weight because markets have been watching every hint of extra spending. Earlier this year a plan to cut the food tax and the announcement of a supplementary budget raised eyebrows. Some observers wondered whether more debt would be needed. The Prime Minister has insisted that total bond issuance for the calendar year would stay in line with the original budget framework. Skeptics remain, of course. Bond markets, after all, tend to price actions more than promises.
How The Yen Reached Multi-Decade Lows
Currency moves rarely have a single cause. Interest-rate differentials between Japan and other major economies have played a large role. When other central banks kept rates higher for longer, capital naturally flowed toward higher-yielding assets elsewhere. That flow put downward pressure on the yen. At the same time, Japan’s own policy of gradual normalization has not closed the gap quickly enough to reverse the trend.
Trade dynamics also matter. A weaker yen makes Japanese exports more competitive on global markets. Automakers, electronics firms, and machinery producers have seen benefits in overseas earnings when those profits are converted back into yen. In January the Prime Minister herself noted that a softer currency could act as a buffer against external tariffs and support export industries. She later clarified that she held no fixed preference for any particular level of the exchange rate. Still, the market remembered the initial remark.
Import costs tell the other side of the story. Energy bills, food prices, and raw materials have all felt the impact. Households notice these changes at the supermarket and at the gas station. That is why currency levels quickly become political. When people feel poorer because of imported inflation, they look to the government for answers. The Prime Minister’s response has been to shift the conversation toward longer-term economic strength rather than short-term currency management.
Rising Yields And The Normalization Path
Japanese government bond yields have been climbing as the central bank continues to adjust its stance. After years of negative rates and massive asset purchases, the shift toward a more conventional policy framework was always going to raise the cost of borrowing. Long-term yields reflect not only the policy rate but also expectations about future growth, inflation, and the supply of new bonds.
Fiscal policy interacts with this process. Any signal that the government might increase spending without a clear offsetting revenue plan can push yields higher. That is why the Prime Minister’s insistence on appropriate control of issuance is closely watched. Markets want evidence that the debt trajectory remains manageable even as the economy receives targeted support.
In my view the tension here is structural. Japan carries a high public-debt-to-GDP ratio. Keeping that debt serviceable requires a delicate balance between growth-friendly policies and fiscal discipline. Raise rates too fast and the debt burden becomes heavier. Issue too many new bonds and investors demand higher compensation. The Prime Minister is trying to walk that line while still delivering on political promises around tax relief and household support.
Building Confidence Through Economic Strength
The core of the Prime Minister’s argument is straightforward. A currency ultimately reflects the underlying health of the economy. If growth accelerates, if productivity improves, and if Japan becomes a more attractive destination for investment, demand for the yen should rise. Exchange-rate interventions can buy time, and both Tokyo and Washington have stepped into the market at moments of extreme pressure. Yet intervention is not a long-term strategy. Sustainable confidence comes from fundamentals.
What does building that stronger economy look like in practice? Higher real wages would help. Companies that invest in technology and efficiency would help. Policies that make it easier for firms to expand and for workers to move into higher-value jobs would help. The Prime Minister appears to believe that focusing on these areas will eventually stabilize the currency more effectively than any short-term verbal defense.
Critics counter that markets move faster than structural reforms. While the economy is being strengthened, the yen can continue to weaken and yields can keep rising. Households and businesses feel the pain in real time. That is why the political debate remains intense. Opposition voices keep pressing for clearer commitments on spending restraint and currency stability. The government keeps answering that growth is the surest path to both.
The Role Of Supplementary Budgets And Tax Plans
Supplementary budgets are common in Japan. They allow the government to respond to changing conditions or to fulfill new political priorities. This year’s discussions around a second supplementary package and the earlier food-tax cut proposal have kept fiscal questions alive. Any extra spending raises the practical issue of how it will be financed. Will existing revenues cover it? Will new bonds be required? Or will other expenditures be trimmed?
The Prime Minister has sought to reassure markets by stating that overall bond issuance for the year should remain consistent with the original plan. That statement aims to draw a clear boundary. Yet experienced observers know that budgets can shift as the year progresses. Economic data, natural disasters, or unexpected global events can all prompt adjustments. The credibility of the commitment will be tested by the actual numbers that appear in coming months.
I find the skepticism understandable. Bond investors have long memories. They have watched previous administrations expand spending and later struggle with the resulting debt dynamics. Trust is earned through consistent delivery, not through single speeches. At the same time, a government that refuses to support households during periods of rising living costs risks political damage. The balancing act is real.
Export Gains Versus Household Costs
One of the more interesting features of the current environment is the split between corporate winners and household losers. Export-oriented companies have enjoyed improved competitiveness. Profit reports often show solid overseas contributions precisely because the yen has been softer. That strength can support stock prices and capital spending plans. It can also create room for wage increases if companies choose to share the gains.
Households face a different equation. Imported goods cost more. Energy remains a major item in family budgets. Even if some wage growth appears, it has to outpace the rise in living costs for real purchasing power to improve. Policymakers are acutely aware of this gap. Supporting real incomes while still encouraging corporate investment is another tightrope that Tokyo is trying to walk.
Perhaps the most delicate question is how long the current configuration can last. A persistently weak yen eventually feeds into broader inflation expectations. If those expectations become entrenched, the central bank may feel compelled to tighten more aggressively. Higher policy rates would then put additional upward pressure on bond yields. The feedback loop is one that officials clearly want to avoid.
Market Reactions And Political Messaging
Markets listen carefully to every nuance in official statements. When a prime minister rejects responsibility for currency and yield moves, traders immediately ask what that implies for future policy. Does it mean the government is comfortable with the current levels? Does it signal reluctance to intervene further? Or is it simply a political defense against opposition attacks?
In practice the answer is probably a mixture. Governments rarely admit full responsibility for market outcomes that are driven by global forces as well as domestic ones. At the same time, no administration can completely ignore sustained pressure on the currency or on borrowing costs. The recent history of coordinated intervention shows that Tokyo remains willing to act when moves become disorderly. The Prime Minister’s comments should be read in that broader context.
Her emphasis on economic strength as the foundation for currency confidence is a classic long-term argument. It is also a useful political framing. It shifts the focus from day-to-day market fluctuations toward the government’s growth agenda. Whether markets will grant her the time needed for that agenda to bear fruit remains an open question.
What Controlled Bond Issuance Really Means
The phrase “appropriately control the amount of government bond issuance” sounds measured and responsible. Translating it into concrete numbers is harder. Appropriate control could mean sticking rigidly to previously announced totals. It could also mean adjusting issuance in response to market conditions while still aiming for a stable debt path over the medium term. Investors will watch the monthly auction calendars and the quarterly outlooks for clues.
Japan’s debt market is unique because the central bank has been such a large buyer for so long. As that presence gradually diminishes, private investors must absorb a larger share of new supply. Their willingness to do so at current yield levels will depend on inflation trends, growth prospects, and the perceived fiscal discipline of the government. Any hint that issuance is expanding faster than expected can quickly push yields higher.
From a practical standpoint the government has incentives to keep the market calm. Sharp rises in yields raise the cost of rolling over existing debt and financing new projects. They can also spill over into mortgage rates and corporate borrowing costs. Maintaining orderly conditions is therefore both an economic and a political priority.
Looking Ahead At Policy Choices
The coming months will test the Prime Minister’s approach. Economic data will show whether growth is firming and whether wage gains are broadening. Inflation figures will reveal how much imported cost pressure is still feeding through. Bond auctions will demonstrate whether demand remains solid at current yield levels. Currency markets will continue to react to interest-rate differentials and risk sentiment.
If the economy shows clearer signs of strength, her argument that fundamentals will eventually support the yen gains credibility. If growth stays soft while the currency weakens further, pressure for more active currency measures or tighter fiscal messaging could intensify. Either way, the public debate over responsibility for market outcomes is unlikely to fade.
I have always believed that currency and bond markets are ultimately referendums on policy credibility. Leaders can reject short-term blame, and sometimes they are right to do so. Global forces are powerful. Domestic reforms take time. Yet over longer horizons the connection between policy choices and market results becomes harder to deny. The Prime Minister is betting that her growth-focused strategy will eventually be judged a success. Markets will deliver their own verdict in the meantime.
The Broader Context Of Monetary Normalization
Japan’s journey away from ultra-loose policy is one of the more significant monetary experiments of recent decades. After years of fighting deflation with every available tool, the central bank is now navigating the reverse path. Raising rates and reducing balance-sheet support in an economy still carrying high public debt requires careful calibration. Move too slowly and the yen remains under pressure. Move too quickly and domestic demand could weaken.
The government and the central bank operate with different mandates, yet their actions are closely intertwined. Fiscal decisions influence the supply of bonds that the market must absorb. Monetary decisions influence the demand for those bonds and the broader interest-rate environment. Coordination, even if informal, matters. The Prime Minister’s comments about controlling issuance can be read as an attempt to signal that fiscal policy will not undermine the normalization process.
Whether that signal is believed will depend on subsequent budget outcomes. Words are useful. Numbers are decisive. If the actual volume of new bonds stays within the ranges previously indicated, market confidence can gradually improve. If issuance drifts higher, skepticism will grow and yields may continue their upward climb.
Household Impact And Political Reality
Behind every market chart sit real households. When the yen weakens, the price of imported food and energy rises. When bond yields climb, the cost of government borrowing increases and that eventually influences the broader interest-rate environment. Families notice these changes in their monthly budgets long before they read about policy debates.
That is why the political stakes remain high. A government that appears indifferent to the cost-of-living pressures risks losing public support. At the same time, a government that expands spending without regard to market consequences can face higher financing costs that constrain future options. Navigating between those risks is the daily work of economic policy.
The Prime Minister has chosen to frame her response around economic strength and measured fiscal management. It is a coherent narrative. Delivery will determine whether it becomes a successful one. In the end, markets and voters will both deliver their assessments. For now, her rejection of direct blame sets a clear political line. The harder task of translating that line into lasting confidence in the yen and stable borrowing costs still lies ahead.
Watching this episode unfold, I am struck by how familiar the pattern feels. Leaders everywhere face moments when markets move against them. The instinct to reject personal responsibility is natural. The more constructive response is to outline a credible path that addresses the underlying pressures. Whether the current strategy achieves that remains the central question for Japan’s economy in the months to come.
Key Takeaways From The Parliamentary Exchange
- The Prime Minister explicitly rejected the idea that her policies alone caused the weak yen or the rise in bond yields.
- She argued that a stronger domestic economy is the most reliable way to restore confidence in the currency.
- On fiscal matters she committed to appropriate control of government bond issuance for the year.
- Earlier comments acknowledging some benefits of a weaker yen for exporters were later clarified as not reflecting a preferred exchange-rate level.
- Markets continue to watch actual issuance numbers and economic data more closely than any single speech.
These points capture the essence of the exchange. They also highlight the gap that often exists between political messaging and market pricing. Closing that gap requires consistent policy execution over time. Japan has the institutional capacity to manage the transition. The test is whether the political will and the economic results align closely enough to satisfy both voters and investors.
In the end, currency and bond markets are unforgiving scorekeepers. They respond to incentives, data, and credibility. The Prime Minister has made her position clear. She does not accept the blame narrative. She offers an alternative story centered on growth and disciplined issuance. The coming chapters of that story will be written not in parliament but in the daily movements of the yen and the yield curve. That is where the real judgment will be rendered.



