

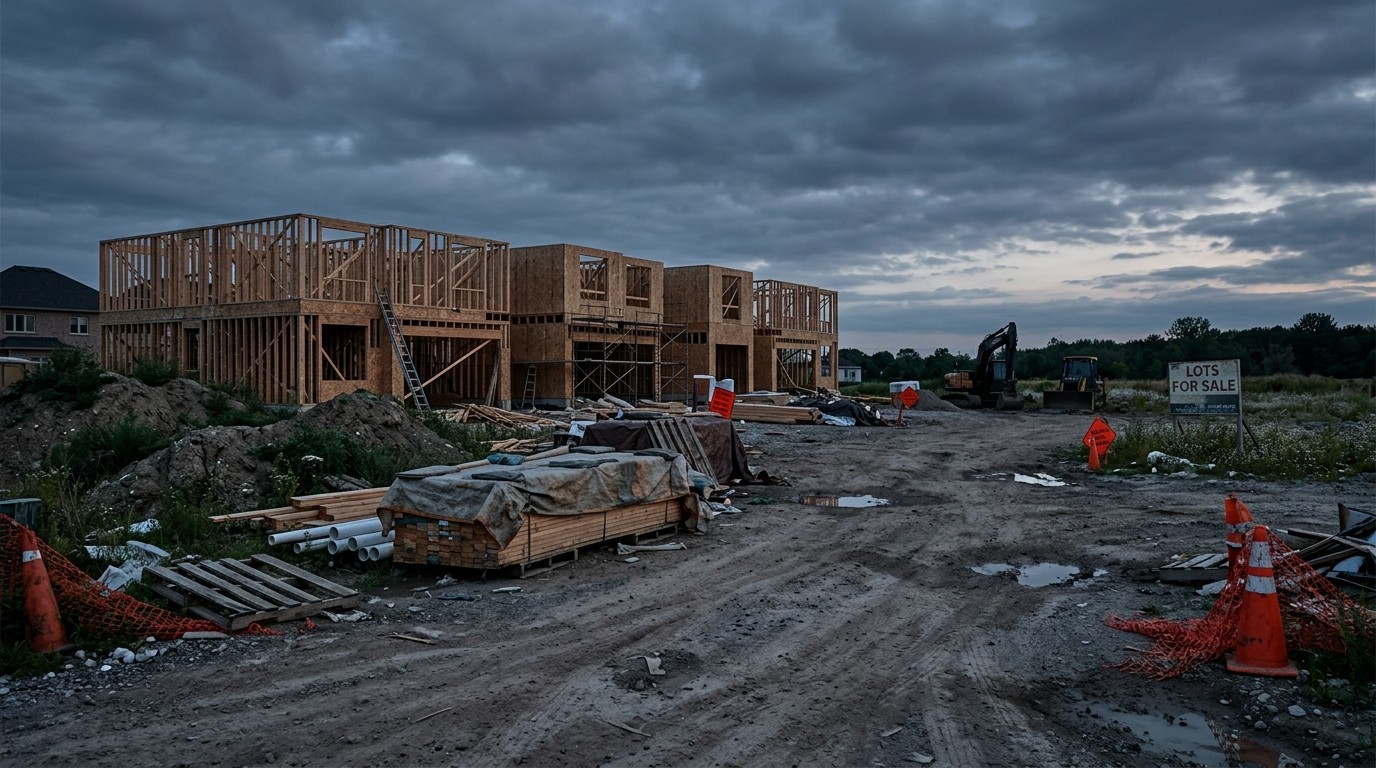

Have you ever watched a once-busy construction site suddenly go quiet? That feeling of stalled progress hit the entire housing industry this month. Builder confidence just dropped to a level not seen in fourteen years, and the reasons feel painfully familiar to anyone trying to buy or sell a home right now.
Why Builder Sentiment Just Collapsed
The latest reading on homebuilder confidence came in at 29. That is down from 32 the previous month and worse than most analysts expected. All three core measures moved lower at the same time. Current sales conditions slipped to 33. Future sales expectations tumbled five points to 32. And the traffic of prospective buyers fell sharply to 18, a number that has not looked this weak since the early recovery years after the last major downturn, setting aside the brief pandemic shock.
In my view, the speed of this drop is what stands out. Confidence does not usually fall this cleanly across every category unless something fundamental has shifted. Higher borrowing costs are the obvious culprit, yet they are not working alone. Material prices, labor shortages, and tighter conditions for construction loans are all stacking on top of one another.
Mortgage Rates Crossing The 7 Percent Line
Mortgage rates have climbed well above 7 percent in recent weeks. That single move changes the monthly payment calculation for almost every buyer. A family that could stretch for a house six months ago now faces payments that feel out of reach. The gap between today’s rates and the average rate locked in by existing homeowners sits at an extreme level. Most current owners hold rates closer to 4.3 percent. That difference creates a powerful lock-in effect. People who might otherwise sell stay put because trading up means accepting a much higher payment on the same size home.
I’ve found that this rate gap does more than just slow transactions. It freezes the entire chain. When sellers stay put, inventory remains tight. When buyers stay on the sidelines, builders see fewer people walking through model homes. The result is a market that feels stuck even though underlying demand has not disappeared.
Higher mortgage rates, elevated construction costs and weaker consumer confidence are keeping more buyers on the sidelines.
That observation captures the current reality well. Demand still exists. People still want homes. They simply cannot make the numbers work at present pricing and financing levels.
Rising Costs Beyond Interest Rates
Builders face pressure on multiple fronts. Construction loan rates have moved higher. Building materials remain expensive. Diesel prices add to the cost of moving equipment and supplies. Energy costs filter through every stage of the process. These expenses do not vanish just because sales slow down. They sit on the books while houses wait for buyers.
Labor conditions have grown more complicated as well. More than one-third of builders reported enforcement activity in their market areas during the past month. That activity has caused delays and, in some cases, discouraged legal workers from showing up consistently. The net effect is longer build times and higher labor costs for the same amount of work.
Perhaps the most interesting aspect is how these cost pressures interact with regulatory changes. Some recent efforts to reduce regulatory burdens have provided modest relief. Yet the relief has not been enough to offset the broader rise in financing and material expenses. Builders still feel squeezed.
Price Cuts And Sales Incentives Reach New Levels
In response, builders are adjusting. Forty-three percent reported cutting prices in the latest survey, the highest share seen in this cycle. The average reduction held steady at 6 percent for the seventh straight month. At the same time, 65 percent of builders offered sales incentives. That figure has stayed above 60 percent for nineteen consecutive months.
These moves tell a clear story. Builders would rather move inventory at a lower margin than hold finished homes that carry financing costs. Incentives take many forms: rate buydowns, closing cost assistance, upgraded finishes, or flexible deposit structures. Each one chips away at the final price the buyer effectively pays.
Still, even with these concessions, traffic remains weak. Prospective buyers continue to hesitate. The combination of high monthly payments and lingering uncertainty about the broader economy keeps many on the fence.
Regional Differences Tell Part Of The Story
Looking at three-month moving averages, the regional picture shows variation but no real bright spots. The Northeast slipped one point to 38. The Midwest fell three points to 40. The South declined one point to 30. The West dropped two points to 26. Every region moved lower. The West continues to post the weakest readings, reflecting both higher prices and greater sensitivity to rate changes in many of its major markets.
These numbers matter because regional differences often signal where the next wave of adjustments will appear. Markets that already carry high price-to-income ratios feel the rate shock more intensely. Builders in those areas face greater pressure to cut prices or slow new starts.
The Growing Gap Between Builders And Buyers
One striking feature of the current environment is the distance between builder confidence and buyer confidence. Homebuyers appear even more cautious. Many feel the American Dream of ownership has moved further out of reach. Affordability metrics support that sense. The combination of elevated prices and higher rates has pushed monthly payments to levels that strain typical household budgets.
In my experience watching housing cycles, this kind of divergence rarely lasts forever. Either rates ease enough to bring buyers back, or prices adjust further until the two sides meet. Right now neither side seems ready to blink first. Sellers who locked in low rates years ago feel little urgency. Buyers who face 7 percent-plus rates feel equally reluctant. Builders sit in the middle, trying to clear inventory without destroying margins.
What happens next will depend heavily on the path of interest rates and the broader employment picture. If rates stay elevated for an extended period, builders will likely continue trimming production plans. New supply will arrive more slowly. That slowdown could eventually support prices once demand returns, but the path there looks bumpy.
Supply Side Constraints Refuse To Ease
Housing remains squeezed by supply-side constraints even as demand softens. Lot availability, entitlement timelines, and labor shortages continue to limit how quickly builders can respond when conditions improve. These structural issues predate the recent rise in rates. They simply become more visible when financing costs climb.
Some builders have already slowed the pace of new starts. Future sales expectations at 32 suggest that caution will persist. Few companies want to break ground aggressively when the pipeline of committed buyers looks thin. The risk of carrying finished inventory at high financing rates is simply too large.
- Higher mortgage rates above 7 percent reduce purchasing power
- Elevated material and labor costs squeeze builder margins
- Labor disruptions add delays and uncertainty
- Existing homeowners remain locked into lower rates
- Buyer traffic has fallen to multi-year lows
Each of these factors reinforces the others. The market has entered a period where traditional levers of adjustment work more slowly than in past cycles.
What Price Reductions Really Signal
The fact that 43 percent of builders cut prices this month deserves closer attention. Price cuts of this breadth do not appear casually. They reflect a recognition that list prices set earlier in the year no longer clear the market. The consistent 6 percent average reduction suggests a measured response rather than panic. Builders are testing the level at which transactions resume without giving away the entire margin.
Incentives layered on top of those cuts further soften the effective price. Rate buydowns in particular have become popular because they directly address the monthly payment problem. A temporary reduction in the interest rate for the first few years can bring the payment back into a range many households can manage. The cost of that incentive is real, yet many builders prefer it to letting houses sit empty.
I’ve noticed that these strategies work better in some markets than others. In areas with strong underlying job growth, modest incentives often restart activity. In markets already dealing with oversupply or weaker employment trends, deeper concessions may be required.
The Longer-Term Affordability Challenge
Affordability challenges did not begin with the latest rate move. Years of rising home prices, limited new construction in many regions, and steady demand created a baseline that was already stretched. Higher rates simply pushed the situation into more difficult territory. Younger buyers and first-time purchasers feel the pressure most acutely. Many have delayed household formation or continued renting longer than planned.
This delay has broader implications. When large cohorts of potential buyers stay on the sidelines, the normal progression of the housing ladder slows. Existing owners who might have moved to larger homes or different locations remain in place. The entire market turns more slowly.
Some observers hope that a combination of modest price adjustments and eventual rate relief will restore balance. Others worry that structural cost increases in construction will keep new homes expensive even if rates ease. Both perspectives contain truth. The eventual clearing level will likely involve some of each.
How Builders Are Adapting Day To Day
On the ground, builders are making practical changes. Many have shifted product mix toward smaller floor plans or more efficient designs that can be priced more competitively. Others have slowed the release of new phases in larger communities, waiting for clearer signals from the market. Speculative building has been dialed back in favor of more build-to-order approaches where possible.
Cash flow management has become critical. Carrying costs on finished inventory add up quickly when sales velocity drops. Some companies have increased their use of joint ventures or other capital structures that share risk. These adjustments are rarely visible to the average homebuyer, yet they shape how much new supply reaches the market in the coming quarters.
Regulatory reform efforts have provided some offset. Streamlining certain approval processes or reducing specific fees can lower the cost of bringing a lot to market. Those gains help, but they operate on a longer timeline than the monthly swing in mortgage rates.
Looking Ahead Without Easy Answers
The current environment leaves little room for complacency. Builder confidence at a fourteen-year low is not a temporary blip. It reflects a genuine squeeze between the cost of delivering homes and the price buyers are willing and able to pay. Until that gap narrows, activity will remain subdued.
Will rates retreat enough to reopen the market? Will prices adjust further? Will new construction techniques or policy changes meaningfully lower costs? No one can answer those questions with certainty today. What seems clear is that the housing market has entered a more cautious phase. Builders are protecting capital. Buyers are protecting monthly budgets. The resulting standoff will shape inventory levels and price trends for the next several quarters.
In the meantime, the data points keep arriving. Traffic numbers, price-cut percentages, and regional sentiment readings will continue to reveal how both sides of the market are adapting. For anyone watching the industry, the message is straightforward. The easy growth years have paused. Careful navigation is required until conditions improve.
The quiet construction sites scattered across the country are more than a temporary inconvenience. They are a visible sign of deeper tensions in housing affordability, financing costs, and supply constraints. How long those sites stay quiet will depend on forces that extend well beyond any single confidence survey. For now, the industry waits, adjusts, and watches the next move in rates and demand.
One final thought stays with me. Housing has always been cyclical, yet the present combination of rate lock-in, elevated construction costs, and cautious consumers feels distinct. Previous downturns often featured one dominant pressure. Today several pressures operate at once. That complexity makes forecasting harder and the eventual recovery path less predictable. Patience and flexibility will matter more than bold predictions in the months ahead.
Builders who survive this period intact will likely emerge with leaner operations and a clearer sense of which product types still work. Buyers who can wait may eventually find more selection or better terms. Those forced to act in the current window face a narrower set of choices. The market will clear eventually. The only question is the price of the wait.
Understanding these dynamics helps explain why confidence has fallen so sharply. It also highlights why a quick rebound looks unlikely without meaningful relief on the rate side or further concessions on the price side. The next several surveys will show whether the bottom is near or whether further declines remain ahead. For the moment, the direction of travel remains lower, and the industry is adjusting accordingly.
Anyone involved in residential real estate—whether building, buying, selling, or simply observing—should treat the current confidence reading as more than a headline. It is a signal that the old assumptions about steady demand meeting available supply no longer hold in the same way. New assumptions will form only after the market tests the current boundaries of affordability and cost. That testing process is underway now, and its outcome will shape the housing landscape for years to come.



