
Have you ever watched a market theme run so hard that every new deal looked like free money until one day it simply stopped working? That moment rarely arrives with a loud announcement. It creeps in through smaller, quieter failures that most people dismiss as one-offs. I have seen this pattern more times than I care to count, and the current wave of AI infrastructure spending is starting to show some of those same early fractures.
The Quiet Shift From Fear Of Missing Out To Fear Of Holding The Bag
In the late stages of every major investment cycle the conversation changes. At first everyone talks about growth, adoption curves, and the size of the prize. Then the talk slowly turns to who will fund the next project and at what price. The cost of capital begins to matter more than the story. That is the stage we appear to be entering now.
Think about the classic pattern. The easiest projects get financed first. The more complex and harder-to-understand structures appear later. Eventually the last deals require buyers who either do not fully grasp the risks or who believe someone else will take them off their hands at a higher price. When those buyers step back, the whole process slows.
Recent examples in the data-center space have started to look familiar. Marginal projects that once would have sailed through are now struggling to clear the market. When that happens, the psychology flips. Investors stop worrying about missing the next leg higher and start worrying about being left with the last, most expensive pieces. The change does not happen overnight. It is a process. Yet by the time it becomes glaringly obvious, the damage is usually already done.
How Rising Funding Costs Crack The Supporting Structure
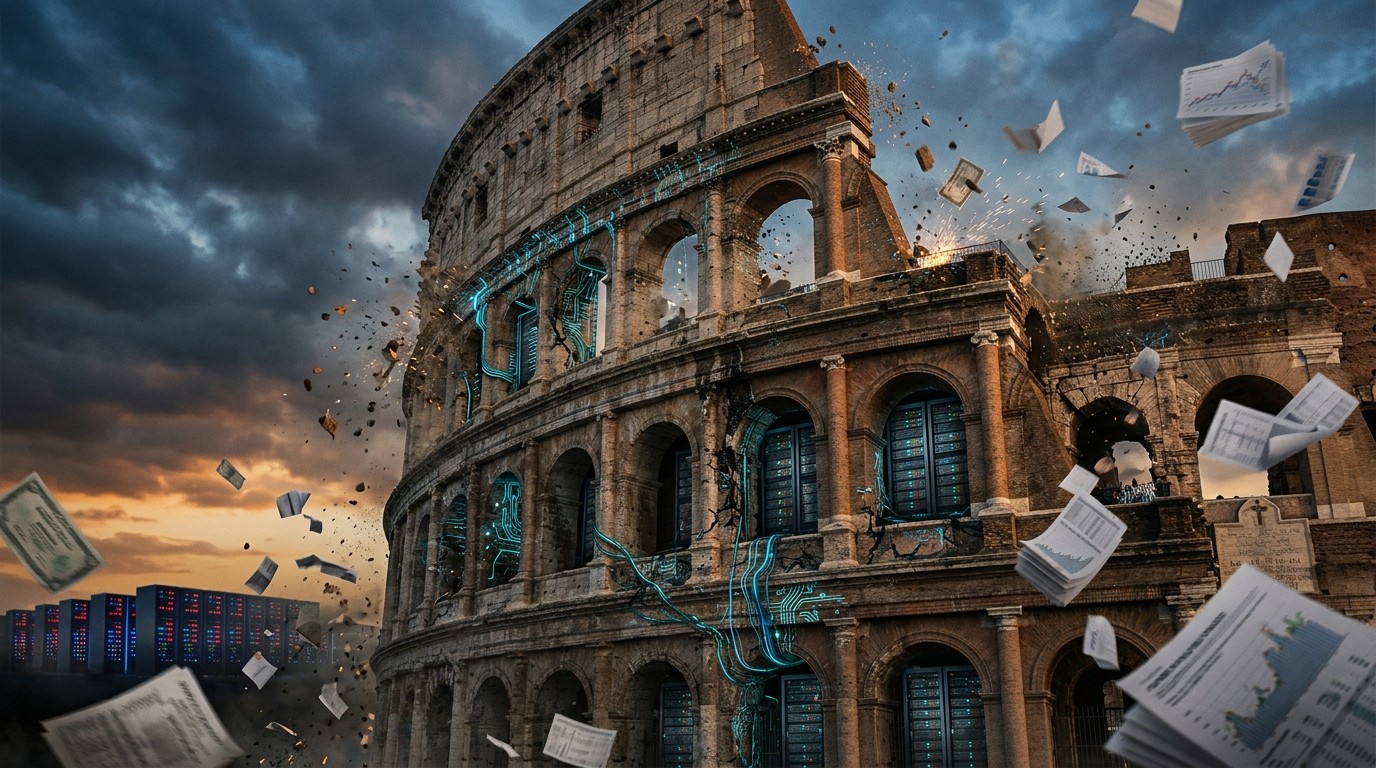
Once the cost of capital rises for the weaker players, the hidden pillars that held the edifice together begin to loosen. Imagine a massive stone arena held by hundreds of tons of iron clamps. Remove enough of those clamps and the structure can no longer withstand the next tremor. Markets work in a similar way. The fasteners in this case are the continuous flow of cheap capital into ambitious projects.
Consider a bond issued only months earlier to fund a large data-center build that is now trading well below par. At the same time newer projects are forced to offer significantly higher yields to attract the same investors. The difference is not subtle. When capital that once cost a certain rate suddenly costs much more, the math on many deals stops working. Developers pause. Equity sponsors reassess. The flywheel slows.
By the time these sorts of things are glaringly obvious, it is too late. The process has already become self-fulfilling.
That self-fulfilling quality is what makes late-cycle transitions so powerful and so difficult to time precisely. Once enough participants begin to demand higher returns or simply sit on their hands, the available pool of capital shrinks. Projects that depended on the next round of financing find themselves stranded. Secondary market prices of existing securities weaken further. The feedback loop strengthens.
The Greater Fool Theory In Reverse
For a long stretch the dominant force was the greater-fool theory operating in reverse order: buy because someone else will pay more. When that dynamic flips, it does not need a single dramatic catalyst. It only needs a critical mass of investors who decide they would rather wait. The first movers who recognize the shift can reposition. Those who wait for absolute clarity often find the exits already crowded.
I have always found that the most useful question at this stage is not “when exactly does it break?” but “what does the portfolio look like once the process is clearly underway?” Stocks that benefited most from the prior funding environment rarely continue to make new highs once capital becomes selective. The rough ceiling forms earlier than most expect. That knowledge alone can change how a portfolio is constructed.
Instead of chasing the final upward surge, capital can be directed toward positions that benefit from higher volatility, wider credit spreads, or the eventual need for stronger balance sheets. The sacking and looting phase, when it arrives, tends to create its own set of opportunities for those prepared in advance.
What The AI Buildout Really Resembles
Step back from the daily noise and the current wave of artificial-intelligence infrastructure spending starts to look less like the creation of durable monopolies and more like an earlier era of utility expansion. Electricity demand exploded over decades. Owning the power plants and transmission lines rarely produced the largest fortunes. The real economic gains flowed to the users of the electricity who built new industries on top of it.
A similar logic may apply here. Even if almost every corner of the economy eventually runs on AI tokens of one form or another, the manufacturers of those tokens may not capture the lasting economic surplus. Competition, rapid technological change, and the sheer capital intensity of continuous upgrades all work against durable pricing power. The companies that figure out how to use the tokens most productively could end up the bigger winners.
That distinction matters enormously for investors. Paying peak valuations for the pure infrastructure providers assumes they will look more like the highest-margin technology platforms than like capital-intensive utilities. History suggests the second outcome is more common once the initial land-grab phase ends.
Monopoly Power Versus Competitive Reality
In pure capitalism the ideal outcome is to spend as little capital as possible while creating the largest possible monopoly. Everything else is secondary. Demand curves and adoption rates are important, of course, but they primarily tell you how large the eventual monopoly can become. They do not automatically create one.
Look at the difference between a true high-margin platform and a large but competitive logistics and retail operation. Strip away certain high-margin segments from the latter and what remains often looks far more ordinary: capital intensive, low margin, and subject to constant competitive pressure. The valuation gap between those two models is enormous for a reason.
As the AI cycle matures, the same question will hang over the frontier labs and the infrastructure builders. Will they look more like the highest-margin platforms or more like the competitive, capital-heavy businesses that underpin them? The answer will determine which investments survive the eventual shakeout with their multiples intact.
Early Warning Signals Already Visible
Several concrete developments already point toward tighter conditions. Certain data-center related offerings that once would have been snapped up have struggled to clear. Yields demanded by lenders on new projects have moved higher in a relatively short period. Bonds issued only a few months earlier for similar purposes now trade at meaningful discounts. These are not yet systemic failures, but they are the kind of incremental pressure that historically precedes broader caution.
- Marginal projects beginning to fail at the financing stage
- Noticeable increase in required yields for new infrastructure debt
- Secondary market prices of recent issues trading well below par
- Shift in investor conversations from growth potential to capital availability
None of these on their own prove the cycle has peaked. Taken together they suggest the cost of capital is no longer a free variable. Once that variable starts moving against the weaker players, the structure that supported aggressive expansion begins to weaken from the inside.
Building A Portfolio For The Next Phase
The practical question for most investors is what to do with this information. Waiting for absolute confirmation usually means accepting lower prices. Acting too early can mean sitting through continued strength. The middle path involves recognizing that the upside from here is more limited than the downside once the process is underway.
In my own thinking I have found it useful to reduce exposure to the most capital-intensive stories that depend on continuous cheap funding. At the same time I look for businesses that benefit from higher volatility, wider spreads, or the eventual need for stronger balance sheets. Cash and short-duration instruments regain their value as optionality rather than as a drag on returns.
Perhaps the most interesting aspect is that the eventual beneficiaries of the technology itself may not be the companies currently attracting the bulk of the capital. The users who can turn the new capabilities into durable competitive advantages in their own industries could emerge far stronger. Identifying those second-order winners requires a different lens than simply following the largest fundraising announcements.
Why Timing The Exact Peak Matters Less Than Understanding The Process
Everyone wants a precise date. Markets rarely oblige. What they do provide is a sequence of steps that, once started, tend to follow a recognizable path. The first projects that cannot clear the market. The first notable increase in required returns. The first secondary market discounts that refuse to recover quickly. Each step reinforces the next.
Once that sequence is clearly in motion, the probability of the broadest indexes making dramatic new highs diminishes. The fear of looking foolish by selling too early loses some of its force. Capital can then be repositioned for the environment that follows rather than the one that is ending.
This is not a call for panic. It is a call for realism about where we sit in the cycle. Late-cycle environments reward preparation more than they reward optimism. The investors who treat the early cracks as noise often discover later that the noise was the signal.
The Historical Parallel That Keeps Returning
Every major technological wave produces an infrastructure boom. Railroads, electricity, telecommunications, fiber optics, and now artificial-intelligence compute all followed variations of the same script. Enormous capital is raised. Capacity is built ahead of demand. Eventually the cost of that capital rises or the expected returns disappoint. A period of consolidation follows in which the strongest operators survive and the weaker ones are absorbed or disappear.
The survivors often go on to generate solid returns, but the peak valuations paid during the frenzy rarely look attractive in hindsight. The companies that learned to use the new infrastructure most effectively frequently create more lasting wealth than the pure infrastructure providers themselves.
That pattern does not guarantee the same outcome this time. It does suggest that treating the current phase as permanent is a risky assumption. Cycles end. The process that ends them is usually visible in advance to those willing to look past the prevailing narrative.
Practical Steps Worth Considering Now
First, examine every holding that depends on continuous access to low-cost capital. Stress-test the economics under higher funding rates. Second, increase attention to balance-sheet strength and free-cash-flow generation rather than pure growth metrics. Third, maintain enough liquidity to take advantage of the dislocations that tend to appear once the process accelerates.
- Review capital intensity and refinancing calendars across the portfolio
- Prefer businesses with pricing power and high incremental margins
- Keep dry powder for opportunities that appear only after the first wave of forced selling
- Watch secondary market pricing of recent issues as a real-time indicator of sentiment
These steps will not eliminate risk. They do improve the odds of navigating the transition with capital intact. In late-cycle environments that is often the most realistic goal.
The Human Element That Algorithms Miss
Markets are ultimately collections of people making decisions under uncertainty. When the dominant emotion shifts from greed to caution, models calibrated on the previous environment lose some of their edge. The qualitative change in conversation among sophisticated capital allocators is itself a data point. When those conversations move from “how large can this get” to “who will fund the next tranche,” the underlying process has already begun.
I have found that listening carefully to that shift in tone provides as much information as any single chart. The numbers matter, of course. The stories people tell about those numbers matter at least as much when the cycle is turning.
Looking Beyond The Current Buildout
If the technology delivers even a fraction of what its strongest advocates claim, the eventual economic transformation will be profound. The question for investors is not whether that transformation occurs but who captures the economic surplus along the way. History leans toward the users rather than the pure producers of the enabling infrastructure once the initial wave of capital spending peaks.
That possibility opens a different set of research questions. Which industries stand to reduce costs or raise barriers most dramatically once advanced models become widely available and reasonably priced? Which companies already possess the data, distribution, or domain expertise to turn the new tools into durable advantage? Those questions may prove more valuable over the next decade than simply tracking the largest capital raises in the infrastructure layer.
None of this requires predicting the exact month the current enthusiasm cools. It only requires recognizing that the process has started and positioning accordingly. The investors who treat the early signs as irrelevant noise often discover, too late, that the noise was the beginning of the end.
A Final Thought On Checkmate Moments
The most expensive mistakes in markets are rarely the ones made at the absolute bottom. They are the ones made while waiting for confirmation that the top is in. By the time confirmation arrives, the best prices have usually disappeared. The process that produces that outcome is already visible in the rising cost of capital, the failure of marginal deals, and the quiet shift in investor psychology.
Recognizing that process early does not guarantee perfect timing. It does improve the chance of exiting the most vulnerable positions before the exits become crowded. In the end that may be the difference between participating in the next cycle with intact capital and spending years recovering from the last one.
The arena still looks impressive from a distance. The missing clamps are only visible up close. Once enough of them are gone, the next tremor does the rest. The time to notice is while the structure still stands.