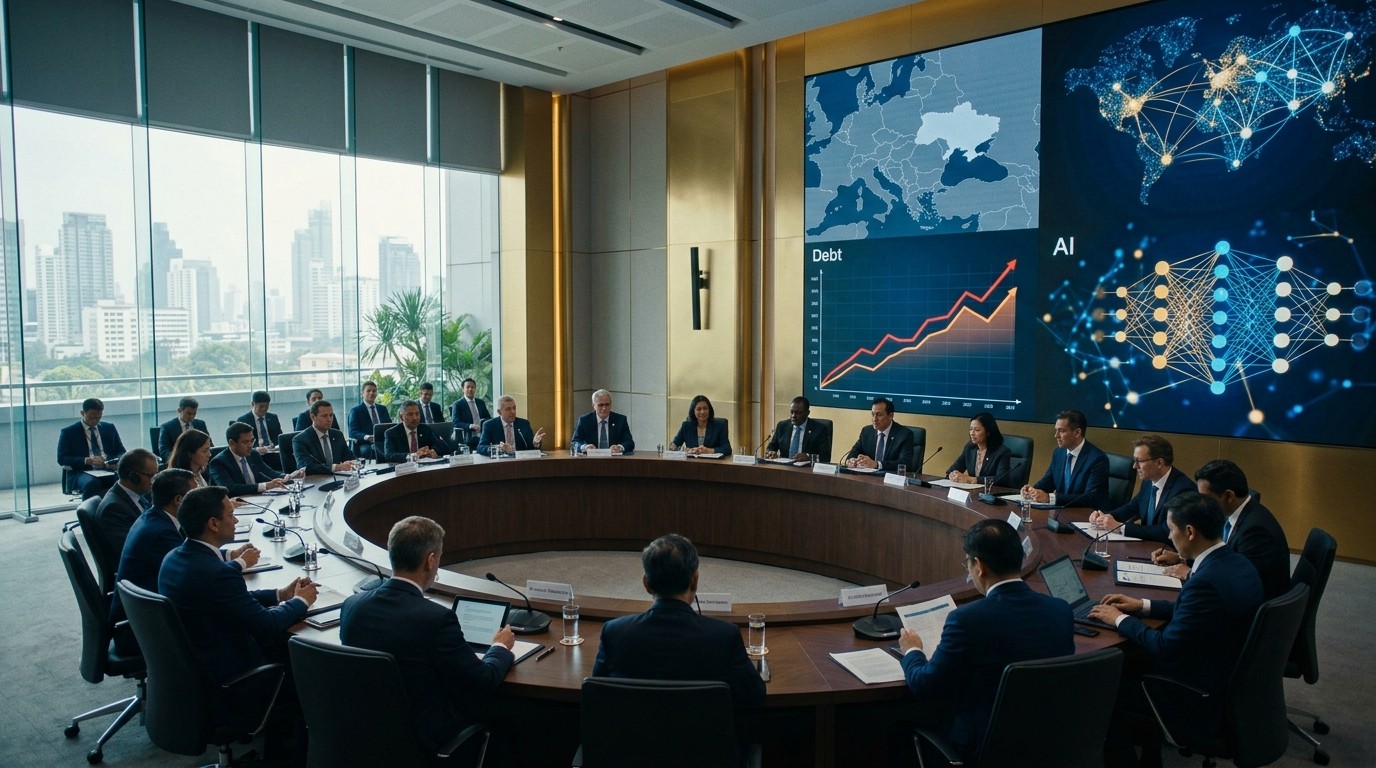

I still remember the first time I sat through an entire day of finance minister briefings years ago and walked out feeling the world had tilted just a little. Last week in Bangkok something similar happened, only this time the tilt felt sharper. The usual suspects that used to dominate every hallway conversation simply were not the main topic. Instead three very different forces kept pulling attention: the mountain of debt sitting in advanced economies, the breakneck pace of artificial intelligence investment, and the renewed political heat around Ukraine. China, once the automatic headline risk, barely registered as a special concern.
What Really Dominated the Bangkok Conversations
Walking the corridors of the Queen Sirikit National Convention Center felt different from previous gatherings. People were still trading forecasts and private assessments, of course. Yet the tone had shifted. Rather than endless speculation about export surges or currency moves from one particular large economy, the talk kept circling back to whether the global system could absorb the combined pressure of heavy public borrowing, massive private capital flows into new technology, and ongoing geopolitical strain.
I’ve found that these meetings often reveal more in the informal moments than in the official communiqués. A central bank governor might downplay risks in a panel and then, over coffee, admit the real worry is something else entirely. That pattern held true again. The formal sessions stayed measured. The side conversations were more candid about where the next fracture might appear.
The Growing Weight of Advanced Economy Debt
One figure kept surfacing in almost every serious discussion. Federal debt in the United States has pushed past the forty-trillion-dollar mark. That number alone is enough to make any fiscal planner sit up straighter. Strong growth helps, but several voices inside the meetings made clear that growth by itself will not put the trajectory on a comfortable path.
The pushback was immediate and familiar. Some officials close to the U.S. Treasury side argued that past forecasts from international institutions have been messy more than once, so a healthy dose of skepticism is warranted. Fair point. Forecasts are imperfect tools. Still, the sheer scale of the debt stock means even modest changes in interest rates or growth assumptions can alter the fiscal math in meaningful ways.
China’s central bank governor made a pointed observation during one of the committee sessions. He argued for stronger monitoring of spillovers that can come from fiscal risks in major advanced economies. The message was straightforward: countries running large deficits need to address them, while those with surpluses should do more to lift domestic consumption and investment. It was a classic call for rebalancing, delivered without drama yet carrying clear implications.
What struck me most was how little disagreement existed on the diagnosis. Almost everyone accepted that debt levels in the so-called Global North have become a structural feature rather than a temporary post-crisis overhang. The real debate was about timing and coordination. Can major central banks and finance ministries move in roughly the same direction, or will divergent paths create additional stress?
Anything from global imbalances to the AI boom or a massive debt buildup could trigger the next financial crisis.
That assessment came from an academic who had just left the meetings. It captured the mood better than most official statements. The risk is not necessarily an immediate explosion. It is the slow accumulation of vulnerabilities that leave less room for error when the next shock arrives.
Artificial Intelligence as Both Opportunity and Pressure Point
The second major thread running through Bangkok was the AI investment wave. The official view was cautiously optimistic about economies well positioned along the supply chain. Places that already have strong semiconductor, hardware or advanced manufacturing capabilities stand to gain. Others risk falling further behind.
That widening gap matters. It is not just about relative growth rates. Capital is finite. When private markets pour enormous sums into data centers, specialized chips and energy infrastructure to support AI, those funds are no longer available for other uses. Governments themselves compete for the same pool of savings when they issue debt. The result can be higher borrowing costs across the board.
There was also an explicit warning about delivery risk. If the technology fails to produce the productivity gains currently priced into valuations and public expectations, the disappointment could ripple widely. Markets have a long history of overestimating near-term technological impact and underestimating the time required for broad economic diffusion. The current cycle may prove no different.
I keep coming back to one practical question. How do policymakers coordinate when one set of institutions is focused on containing inflation while another is trying to foster technological leadership? The Federal Reserve, the European Central Bank and the People’s Bank of China each face domestic constraints. Perfect alignment is unrealistic. Even modest coordination on the fiscal-monetary mix would help reduce the chance of policy mistakes amplifying each other.
Perhaps the most interesting aspect is how quickly AI has moved from abstract future risk to present-day balance-sheet concern. Companies are borrowing to fund the build-out. Sovereigns are watching their own borrowing costs react. The feedback loop is already visible.
Ukraine Returns to Center Stage
Geopolitics never really left the room, of course. Yet last week it became impossible to ignore. Russian finance officials attended key sessions in person. The reaction from many European counterparts was immediate and public. Nearly half the delegates at one major committee meeting walked out when the Russian minister began speaking. That kind of visible protest is rare in these settings and says a great deal about the depth of feeling.
Ukraine’s central bank leadership noted the unexpected breadth of solidarity expressed privately by many finance officials. After years of war fatigue in some capitals, the emotional response still runs strong among a significant group of policymakers. Concrete support followed. A group of major economies announced fresh funding for critical infrastructure repairs at a nuclear facility, with expectations of additional commitments at a later donor gathering.
There is a quiet fiscal reality underneath the political theater. Rising public debt in many countries is already limiting room for new spending priorities, including defense and reconstruction support. Every additional commitment has to be weighed against domestic pressures. That tension will not disappear soon.
I’ve always believed that these meetings function partly as safety valves. They allow governments to signal positions without the full weight of a formal diplomatic summit. The walkouts and public statements served that purpose. They also reminded everyone that the conflict remains an active variable in the global risk equation rather than a background condition.
Why China No Longer Feels Like the Unique Risk
Contrast the energy around debt, AI and Ukraine with the relative quiet surrounding China. In earlier years the same gathering would have featured long panels on trade imbalances, industrial policy and currency dynamics. This time those topics surfaced far less often.
One experienced market participant who has attended these events for years put it simply. Conversations that once automatically drifted toward bilateral tensions or manufacturing shocks now treat the country as one risk among many rather than a special category of its own. The perception of greater stability in the relationship with Washington appears to have reduced the sense of urgency.
That does not mean investors have suddenly become enthusiastic about direct investment. Many remain cautious on that front. At the same time there is clear interest in certain technology listings and a healthy appetite for local bonds, especially while the currency has shown relative stability and occasional strength.
The shift feels pragmatic rather than ideological. Markets are good at recalibrating once a narrative loses its monopoly on attention. China remains important. It simply no longer crowds out every other concern the way it once did.
How These Risks Interact With One Another
Looking at each issue in isolation misses the more interesting connections. Heavy debt loads reduce fiscal space precisely when geopolitical needs and technological transitions demand new public resources. AI investment absorbs private capital that might otherwise fund traditional infrastructure or help absorb government issuance. Geopolitical uncertainty raises risk premia just as borrowers need lower costs to keep debt service manageable.
The system is more tightly coupled than the official language sometimes admits. A sharp rise in long-term yields in one major market can quickly affect funding conditions elsewhere. A sudden reassessment of AI productivity potential could hit equity valuations and credit spreads simultaneously. Any escalation that forces larger fiscal commitments in Europe or elsewhere would further tighten the constraints already visible in debt dynamics.
Coordination is the missing piece that keeps coming up. Not perfect harmony, which is impossible, but at least an awareness that national policy choices have international consequences. The seating arrangements at some of the smaller meetings last week told their own story. Key players were not always placed for easy informal exchange. Symbolism matters in these environments.
What Markets Seem to Be Pricing In
Equity and credit markets have remained relatively resilient through all of this. That resilience itself becomes part of the story. When asset prices stay elevated, the incentive to confront medium-term fiscal and structural issues softens. Why take politically difficult steps today if markets are still willing to fund the status quo at manageable rates?
Yet the conversations in Bangkok suggested that many official participants are less complacent than price action might imply. They see the potential for non-linear outcomes. A sudden loss of confidence in one large sovereign’s fiscal path, a sharper-than-expected correction in technology valuations, or a geopolitical shock that forces rapid resource reallocation could all test the system’s flexibility.
In my experience the most dangerous periods are not the ones filled with obvious crisis rhetoric. They are the ones where everything looks manageable until it suddenly is not. The current environment has that quality. Debt is high but serviceable. AI investment is large but still producing visible activity. Geopolitical tensions are elevated yet contained within known channels. Each element alone looks navigable. Their combination deserves more attention than it often receives.
Practical Implications for Policy and Investors
For policymakers the message is clear enough. Fiscal frameworks need greater credibility over the medium term even if near-term stimulus remains tempting. Regulatory approaches to the AI build-out should try to preserve innovation while reducing the chance of sudden capital misallocation. Geopolitical support needs realistic multi-year planning rather than ad-hoc packages that create their own uncertainty.
Investors face a different set of calculations. Traditional country risk rankings may need updating. The old hierarchy that placed one large emerging market in a unique category of concern looks less relevant. Attention is shifting toward sovereigns with large existing debt stocks, sectors exposed to the full cycle of AI capital expenditure, and assets sensitive to shifts in geopolitical funding priorities.
- Monitor fiscal trajectories in major advanced economies more closely than headline growth numbers alone
- Watch capital intensity and funding conditions in AI-related industries for early signs of strain
- Treat geopolitical support packages as multi-year commitments that will compete with other budget priorities
- Reassess whether older narratives about unique bilateral risks still drive portfolio decisions
None of these points is revolutionary. The value lies in keeping them simultaneously in view rather than treating each as a separate silo.
Looking Ahead From Bangkok
The meetings closed without dramatic breakthroughs or sudden market moves. That outcome itself is informative. Officials returned home with a clearer sense of the risks that now occupy center stage and a quieter acknowledgment that an older set of concerns has receded, at least for now.
Whether the shift proves durable depends on events still outside anyone’s full control. A renewed flare-up in trade tensions could quickly restore earlier narratives. A major technological disappointment could elevate AI from growth story to financial vulnerability. Further escalation or unexpected de-escalation around Ukraine would rewrite fiscal and political calendars in multiple capitals.
For the moment, though, the hierarchy of worries has changed. Sovereign debt dynamics, the AI investment cycle and ongoing geopolitical commitments sit higher on the list than they did a few years ago. China occupies a more ordinary place among global risks. That reordering is the single most useful takeaway from a week of dense discussions in Bangkok.
I left the city thinking about how often the biggest risks are the ones that feel familiar until they suddenly stop being manageable. Debt is familiar. Technology booms are familiar. Geopolitical friction is familiar. Their simultaneous presence at elevated levels is less so. The officials who spent last week comparing notes seemed to understand that distinction. Markets would do well to keep it in mind as well.
The next set of meetings will tell us whether the new ranking of concerns holds or whether older patterns reassert themselves. Until then the practical task is straightforward. Track the debt numbers carefully. Watch the real economy effects of AI capital spending. Stay alert to the fiscal and political costs of sustained geopolitical support. And resist the temptation to treat any single country as the unique source of global risk simply because that was the habit of previous cycles.
Those four habits of mind would have served participants well in Bangkok. They remain useful long after the conference badges have been put away.
The Quiet Shift in How Risk Is Discussed
One of the more subtle changes last week was linguistic. Officials spoke less about “systemic threats from a single large economy” and more about “overlapping vulnerabilities.” That phrasing matters. It acknowledges complexity without pointing fingers. It also makes coordination more politically feasible because no single capital is singled out as the primary source of trouble.
Language shapes the possible responses. When a risk is framed as unique and external, the policy toolkit tends toward confrontation or isolation. When the same risk is framed as one element in a broader set of domestic and international pressures, the toolkit expands to include domestic reforms, multilateral monitoring and quiet technical cooperation.
I noticed that shift most clearly in the side meetings that never appear in the official schedule. Participants compared notes on debt sustainability metrics, stress-tested AI investment scenarios under different productivity assumptions, and discussed the multi-year budgeting implications of continued support for Ukraine. Those conversations felt more technical and less theatrical than equivalent discussions from a few years earlier.
Whether the new framing survives the next geopolitical or market shock remains an open question. For now it offers a more useful map of the terrain than the older, more polarized narratives.
Lessons From Previous Asian Hostings
Bangkok last hosted these meetings more than three decades ago. The intervening years include the Asian financial crisis that began with a currency unpegging not far from the same city. That history was not lost on participants. Several mentioned the long arc from the late 1990s vulnerabilities to the current configuration of risks.
The comparison is imperfect, of course. Capital markets are deeper. Policy frameworks are more sophisticated. Cross-border surveillance is far more developed. Yet the core insight remains relevant. Vulnerabilities that appear manageable in isolation can interact in unexpected ways when conditions change.
The officials who lived through earlier crises tend to carry a different posture into these gatherings. They listen more carefully to the soft signals. They ask more questions about contingent liabilities and second-round effects. That institutional memory is one of the quieter strengths of the current process.
It is also a reminder that the location of these meetings is never entirely neutral. Holding them in Asia after a long interval invited a different set of regional perspectives into the conversation. Those perspectives helped keep the focus on practical transmission channels rather than abstract ideology.
Where Attention Should Focus Next
In the months ahead several concrete markers will reveal whether the Bangkok assessment holds. Watch the path of long-term interest rates in the largest advanced economies. Track the volume and financing terms of AI-related capital expenditure. Follow the size and duration of any new support packages related to Ukraine. Observe whether trade and investment flows with China settle into a more predictable pattern or reintroduce volatility.
None of these indicators will move in isolation. A sharp rise in yields could slow AI investment just as productivity hopes need confirmation. Larger geopolitical spending could crowd out other fiscal priorities and raise questions about debt sustainability. A sudden shift in trade patterns could reawaken older risk narratives that currently sit in the background.
The useful discipline is to keep all three domains in view at once. That is harder than it sounds. Specialists naturally focus on their own silos. Markets often rotate attention from one narrative to the next. The value of gatherings like the one just concluded is that they force a temporary integration of perspectives.
Whether that integration lasts beyond the flight home is the real test. From what I observed in the hallways and meeting rooms, a meaningful number of participants left Bangkok with a revised mental model. Debt, technology investment and geopolitics now share the top tier of concerns. An older set of bilateral worries has been demoted, at least for the time being. That reordering, more than any single communiqué, is the story worth carrying forward.
The coming quarters will show whether markets and policymakers continue to operate with that updated map or whether familiar habits reassert themselves at the first sign of stress. For now the clearer risk ranking offers a modest improvement in collective awareness. In a system as tightly linked as the current global economy, even modest improvements in shared understanding can matter when the next unexpected pressure arrives.