
Have you ever watched a company quietly keep raising its numbers while the rest of the market debates political noise? That is exactly what happened this week when one of the largest players in aerospace and defense updated its full-year view for the third time in a row. The move landed with a solid thud among professional investors who have been tracking the so-called rearmament supercycle for months. In my experience these kinds of repeated upward revisions rarely appear in isolation. They usually signal something deeper is shifting underneath the surface.
Why Missile Demand Is Reshaping The Entire Defense Landscape
Global tensions have not exactly cooled off. Governments across multiple regions continue to place large multi-year orders for proven systems, and companies that can deliver those systems at scale are seeing the results show up in both the top and bottom lines. The latest quarterly report from this major manufacturer showed organic sales growth in every major division, a record backlog, and higher expectations for the year ahead. Wall Street largely described the update as strong and broad-based.
I have followed this sector long enough to know that one solid quarter does not make a trend. Three consecutive raises in guidance, however, start to look like a pattern. The company now expects adjusted earnings between $7.65 and $7.75 a share for the full year. Even the low end of that range sits above the average forecast that analysts had been using. Sales and free cash flow targets moved higher as well. Those kinds of numbers tend to catch attention.
Breaking Down The Quarterly Results
Adjusted earnings came in at $2.26 a share. That figure beat expectations, though it did include a temporary benefit linked to tariff recoveries that courts had previously overturned. Revenue approached $25 billion, roughly four percent ahead of consensus. Every operating unit posted double-digit organic growth. That kind of consistency across commercial aerospace and pure defense is uncommon.
One analyst note that circulated quickly called the quarter solid and the guidance raise meaningful. Another described the defense side as accelerating. Those are not words these observers throw around lightly. When the commentary stays this positive after adjusting for one-time items, it usually means the underlying demand is real.
Here is a quick snapshot of how the pieces lined up:
- Overall organic revenue growth reached about 12 percent
- Adjusted segment operating margin expanded more than one hundred basis points
- Free cash flow for the quarter landed well above the street estimate
- Backlog climbed to a new record of roughly $340 billion
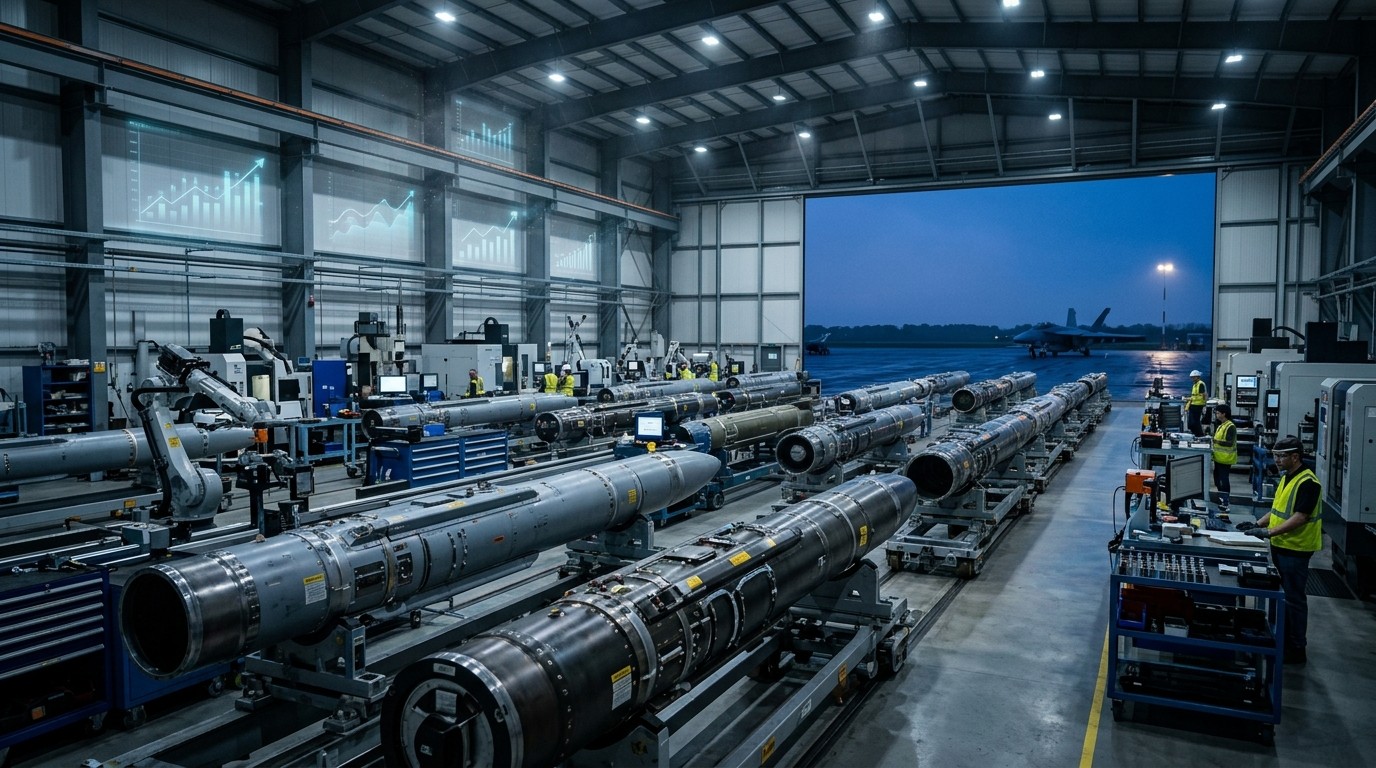
The backlog figure deserves special attention. More than $81 billion in new awards arrived during the period. Two large multi-year packages for cruise missiles and air-to-air systems alone accounted for a substantial portion of that total. When customers lock in those kinds of long-term commitments, the revenue visibility stretches out for years.
Segment Performance Shows Breadth Rather Than Concentration
It is easy to assume that missiles alone drove everything. The actual numbers tell a more balanced story. The pure defense unit grew organic sales by 14 percent. The commercial systems division posted 12 percent organic growth, helped by strong aftermarket demand. The propulsion business added 10 percent organic growth even while original equipment shipments for large commercial engines faced some mix headwinds.
Aftermarket activity remains particularly healthy. One division saw aftermarket sales rise 9 percent. Another reported a 21 percent jump. Those percentages matter because aftermarket work usually carries better margins and more predictable cash flow than new equipment sales. In my view the resilience of the commercial aftermarket has been one of the quieter strengths of the recent cycle.
Of course not every line item looked perfect. Commercial original equipment for large engines declined roughly 5 percent because of an unfavorable mix. There was also a notable charge related to a customer bankruptcy. Still, the overall picture stayed clearly positive once those items were set aside.
Updated Full-Year Guidance And What It Implies
Management lifted the 2026 sales range to $97.0–$97.5 billion. Organic growth is now expected in the 10–11 percent band, up from the previous 8–9 percent outlook. Adjusted earnings guidance moved to $7.65–$7.75. Free cash flow is projected at $9.0–$9.2 billion. Each of those midpoints sits above prior consensus levels.
Perhaps the most interesting aspect is how the raise was split between operational improvement and the temporary tariff recovery. Analysts who adjusted for the one-time items still saw an underlying operational lift. That distinction matters for anyone trying to judge sustainability. One-time benefits disappear. Structural demand does not.
The defense rearmament supercycle is accelerating.
That short observation from one closely followed analyst captures the mood fairly well. When backlog expands at a 36 percent year-over-year pace and multi-year missile awards keep arriving, the multi-year top-line trajectory starts to look more secure.
How Investors Are Weighing The News
Shares moved modestly higher in early trading after the release. The stock has spent most of the year inside a relatively wide range, so the reaction stayed measured rather than euphoric. That restrained response actually feels healthy to me. Markets that chase every positive print often give those gains back quickly. Steady accumulation on solid fundamentals tends to last longer.
Broader defense names have faced some pressure recently as investors try to price possible shifts in legislative control. Political uncertainty is nothing new for this group. What has changed is the sheer volume of already contracted work. A record backlog of that size provides a buffer against short-term policy swings. Programs already under contract continue regardless of who holds the majority in any given chamber.
Still, the question keeps circulating: will the sector regain momentum if political outcomes prove less disruptive than some had feared? I do not claim to know the answer. What I do know is that companies currently delivering double-digit organic growth and raising guidance tend to attract capital over time, politics included.
Commercial Aerospace Demand Remains Surprisingly Firm
Much of the public conversation focuses on missiles and military systems. The commercial side of the business has quietly held up better than many expected. Aftermarket strength at both the systems and propulsion units suggests airlines continue to fly existing fleets hard while they wait for new aircraft deliveries. That dynamic has been a recurring theme for several quarters now.
Original equipment volumes for large commercial engines did face some mix pressure. That is not ideal, yet it is also not a surprise given the well-known production constraints across the wider commercial aircraft industry. When supply chains eventually catch up, the installed base of engines already in service should continue to generate aftermarket revenue for years.
In my experience the combination of healthy aftermarket and rising defense work creates a more resilient earnings profile than either side alone. Cyclical softness on the commercial original-equipment side can be offset by multi-year military contracts. That balance is one reason the guidance raise carried extra weight this time.
Margin Expansion And Cash Flow Quality
Adjusted segment margins improved by roughly 110 basis points. Every division contributed to the beat even after stripping out temporary recoveries. Free cash flow for the quarter exceeded expectations by a healthy margin and included a portion of the tariff-related inflow. Looking ahead, the full-year free cash flow target now sits in a range that would represent solid conversion of earnings into cash.
Cash generation matters more than most headline numbers. A company that can fund its own growth, return capital, and still invest in capacity tends to compound value more steadily than one that relies on external financing. The updated free cash flow outlook suggests management sees a clear path to that outcome.
What The Record Backlog Actually Means
A $340 billion backlog is not just a large number. It represents years of scheduled work that has already been awarded. Multi-year awards for specific missile systems reduce the need to win new competitions every quarter. That visibility is valuable when capital markets turn volatile or when political headlines dominate the news cycle.
Of course backlog is only as good as the company’s ability to convert it into delivered products and cash. Execution risk always exists. Supply chain constraints, labor availability, and production ramp challenges can slow the translation from award to revenue. So far the company has managed those pressures reasonably well, but investors will keep watching the conversion rate closely.
Risks That Still Deserve Attention
No outlook is risk-free. Commercial original-equipment mix can remain unfavorable longer than expected. Aftermarket demand, while strong today, could moderate if airline utilization patterns change. Large one-time charges, such as the recent customer bankruptcy item, can reappear. And the broader political environment around defense budgets will continue to generate noise.
I have found that the most useful approach is to separate structural demand from temporary noise. Structural demand currently looks robust across both military modernization programs and commercial fleet utilization. Temporary noise includes tariff accounting, individual customer issues, and short-term political speculation. The guidance raise suggests management sees the structural side dominating the near-term picture.
How This Fits Into The Larger Rearmament Trend
Several countries have publicly committed to higher defense spending targets over multi-year horizons. That policy shift is now translating into actual contracts. Companies that already possess production capacity, certified systems, and established customer relationships are the first to benefit. New entrants face longer qualification timelines. That reality tends to concentrate awards among a relatively small group of established suppliers.
Missiles in particular have become a high-priority item for many defense ministries. Proven systems that can be produced at volume attract large multi-year packages. When those packages arrive, they flow through the income statement over several years and support higher confidence in long-term planning.
The same dynamic appears in other categories such as air defense, precision munitions, and advanced sensors. The common thread is urgency. Governments that previously deferred modernization are now trying to close capability gaps more quickly. That urgency supports both volume and pricing discipline for suppliers.
Investor Takeaways Worth Considering
First, repeated guidance raises often signal that internal visibility is better than external estimates. Second, a record backlog provides a multi-year revenue floor that few other industrial sectors can match. Third, the combination of defense growth and resilient commercial aftermarket creates a more balanced earnings profile than pure-play defense names sometimes offer.
Fourth, margin expansion alongside volume growth is usually a healthy sign. Fifth, free cash flow growth that tracks or exceeds earnings growth supports capital returns and further investment. None of these points guarantee future performance, of course. They simply describe the current operating environment as reflected in the latest numbers.
I keep returning to one practical observation. In periods of geopolitical uncertainty, companies that already hold large contracted backlogs and can demonstrate consistent execution tend to attract more durable investor interest than those still waiting for awards. The latest report fits that description.
Looking Ahead To The Next Several Quarters
The raised full-year targets imply that management expects the current momentum to continue through the remaining periods. Organic growth in the low double digits is a high bar for a company of this size. Meeting that bar will require continued strength in both missile deliveries and commercial aftermarket activity.
Investors will likely focus on a few recurring questions. Can the company sustain aftermarket growth rates near recent levels? How quickly will the large multi-year awards convert into revenue? Will propulsion original-equipment mix improve as production rates stabilize? Are there further opportunities for margin expansion once temporary items fall away?
Those questions are reasonable. The answers will arrive gradually through successive quarterly updates. For now the direction of travel is clear: higher sales expectations, higher earnings expectations, and higher free cash flow expectations than the market had previously modeled.
A Broader Perspective On Defense Equities
The entire group has experienced periods of both enthusiasm and skepticism over the past couple of years. Valuation debates, political headlines, and shifting budget priorities create volatility. Yet the underlying order activity has remained elevated. Companies that can translate that order activity into delivered products and expanding margins tend to separate themselves over time.
One subtle point worth noting is the difference between headline political risk and actual program risk. Headline political risk can move share prices on any given day. Actual program risk is measured by whether already-awarded contracts continue to be funded and executed. The size of the current backlog suggests that a large portion of near-term work sits in the second category.
That distinction does not eliminate uncertainty. It simply frames the risk more accurately. Investors who focus exclusively on daily political commentary can miss the multi-year contracted revenue that already exists.
Final Thoughts On The Latest Update
The third consecutive guidance raise is not a minor event. It reflects sustained demand for both military systems and commercial aerospace support. Organic growth across all three major units, a record backlog, and higher targets for sales, earnings, and cash flow paint a coherent picture. Temporary items exist and should be adjusted for, yet the operational trends remain positive even after those adjustments.
Markets will continue to debate the political overlay. That is normal. What the latest numbers demonstrate is that the underlying industrial activity continues to advance. Companies that can keep converting large backlogs into growing earnings and cash flow tend to reward patient capital over complete cycles.
I will be watching the next few quarters for confirmation that the raised targets remain intact and that margin progress continues. For the moment the data points in a constructive direction. Missile demand is real. The rearmament cycle is still gathering pace. And at least one major participant has now raised its outlook three times in a row to reflect that reality.
Whether that momentum carries the broader sector higher will depend on many factors beyond any single company’s control. Still, consistent execution and rising visibility rarely go unrewarded for long. The latest report simply adds another data point to a trend that has been building for some time.
The story is still unfolding. New awards will arrive. Production rates will be tested. Political headlines will come and go. Through it all, the companies that keep delivering on already-won contracts while expanding margins will likely remain the ones investors return to when the noise eventually settles. Right now one of those companies has just raised its hand again and said the numbers are still moving higher.