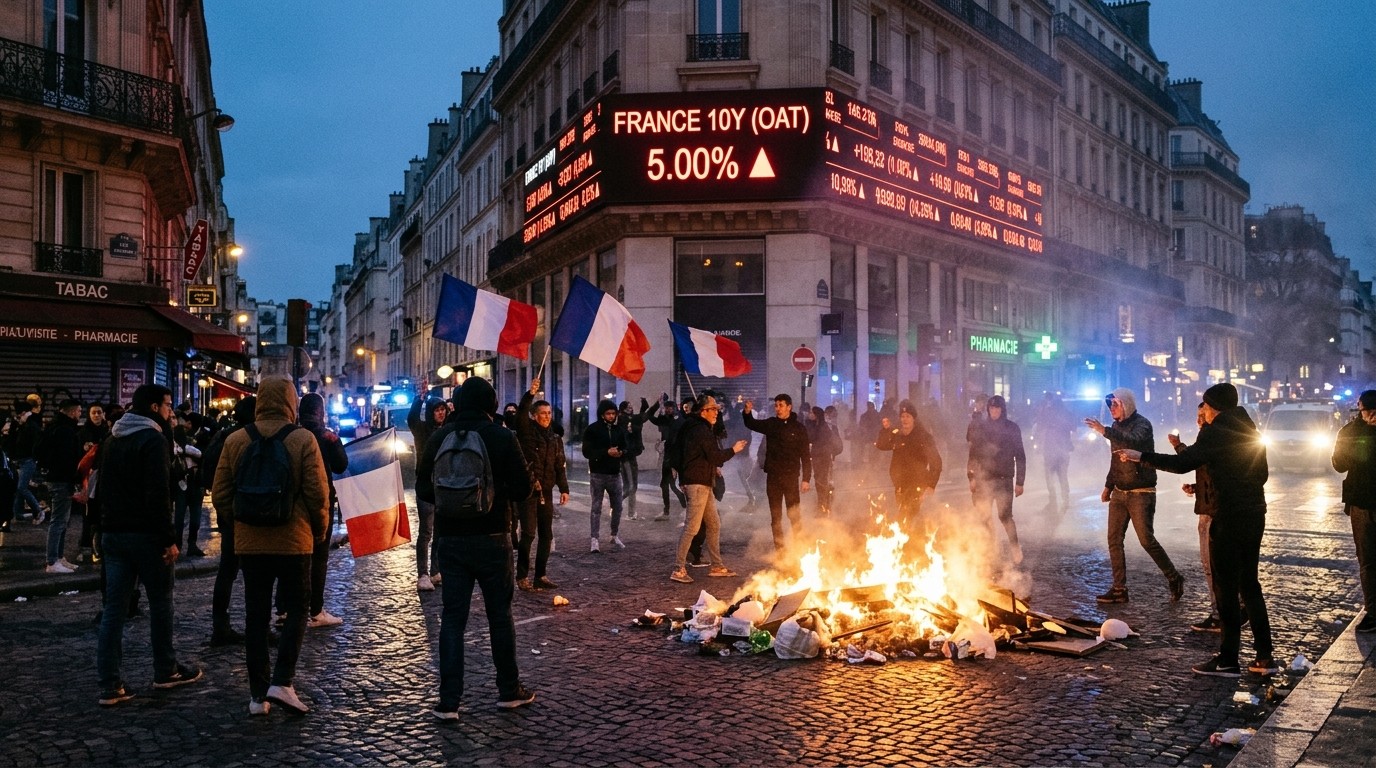

I still remember the last time French 10-year bond yields sat near 5%. It was 2002, the euro was young, and most of us still carried flip phones. Watching the same number flash across screens again this week felt strangely personal, almost like running into an old acquaintance you hoped never to see. The yield crossed that symbolic line while protesters filled streets in Marseille and beyond, waving flags past burning debris and chanting about the high cost of living. Markets rarely move in isolation. This time the connection between political heat and borrowing costs looks impossible to ignore.
Why the 5% Threshold Matters More Than the Headline
Crossing 5% is not just a round number. For years French debt carried the quiet assumption of relative safety inside the eurozone. Investors treated it as a close cousin to German paper, slightly riskier yet still solid. When the yield climbs that high, the market is effectively saying the risk premium has changed. Governments suddenly pay more to roll over existing debt and to fund new spending. Households and companies feel the ripple through higher mortgage rates and tighter credit conditions. In my view, the psychological weight of that number may prove larger than the arithmetic itself.
Consider the simple math of debt service. A country that borrows hundreds of billions each year sees interest costs climb fast once yields move. Even a one-percentage-point rise can translate into billions of extra euros that must come from somewhere, usually higher taxes or reduced services. That feedback loop is exactly what protesters are already complaining about. The timing could hardly be worse.
The Street Protests Behind the Market Move
The images coming out of Marseille and other cities show more than isolated frustration. Demonstrators have been gathering over the rising cost of living, a complaint that has simmered for months and now appears to have boiled over. Flags, smoke, and clashes with police make for dramatic footage, yet the underlying grievance is economic. Food prices, energy bills, and rents have outpaced wage growth for many households. When people feel the system is no longer working for them, they take to the streets. Markets notice.
I have watched similar episodes in other European countries. Political noise often stays contained until it starts to threaten fiscal discipline or raises questions about future policy direction. Right now investors seem to be pricing in a higher chance that the French government will face pressure to spend more, tax less, or both. Either path complicates the debt trajectory. That uncertainty shows up first in the bond market.
Markets can ignore street protests for a while. They cannot ignore sustained pressure on the fiscal numbers that follow.
Perhaps the most interesting aspect is how quickly the yield moved once the protests gained visibility. Liquidity in government bonds remains deep, yet sentiment can shift in a matter of sessions when headlines turn dark. Traders who had been comfortable holding French paper began demanding a larger cushion. The 5% level acted as a magnet once momentum built.
How Borrowing Costs Feed Back Into Daily Life
Higher government yields do not stay confined to trading desks. Banks use sovereign rates as a benchmark when pricing loans to businesses and households. Mortgage offers start to look less attractive. Corporate borrowers face steeper coupons on new debt. Over time the higher cost of capital can slow investment and hiring. That is the opposite of what an economy needs when people are already angry about living costs.
In practical terms, a family looking to buy a home or refinance may find monthly payments rising just as their grocery bill refuses to fall. Small businesses that planned expansion might delay projects. The irony is hard to miss: protests driven by the high cost of living can themselves contribute to higher costs through the interest-rate channel. I have seen this dynamic play out before, and it rarely ends cleanly.
- Mortgage rates tend to track longer-term government yields with a lag
- Corporate bond spreads often widen when sovereign risk rises
- Pension funds and insurers holding existing French debt face mark-to-market pressure
- Foreign investors may demand extra compensation for currency and political risk
None of these effects appear overnight. They accumulate. The longer yields stay elevated, the more visible the damage becomes in the real economy. That is why the 5% print has drawn so much attention even among people who normally ignore bond screens.
Historical Context: The Last Time Yields Lived Here
Back in 2002 the world looked different. The euro had just replaced national currencies for most practical purposes. Growth expectations were still optimistic. Deficits mattered, yet the idea of a sustained European debt crisis felt distant. Yields near 5% reflected a different interest-rate environment overall, one in which inflation and policy rates sat higher than the ultra-low period that followed the global financial crisis.
Today the return to that level carries a different flavor. Central banks have spent years trying to normalize policy after a long era of near-zero rates. Investors had grown used to French yields oscillating in a much lower range. The sudden break higher feels like a regime shift rather than a temporary blip. In my experience, markets often underestimate how sticky such shifts can become once they take hold.
Compare the two periods and the contrast sharpens. In 2002 political stability in France looked more solid from the outside. Today the combination of fiscal pressure and visible social unrest creates a narrative that is harder for investors to dismiss. History does not repeat exactly, yet it often rhymes in uncomfortable ways.
What Investors Are Really Pricing
Bond yields reflect a bundle of expectations: inflation, growth, monetary policy, and credit risk. Right now the credit-risk component appears to be doing more of the heavy lifting. Traders are asking whether France will maintain the fiscal path that previously kept its spreads contained relative to Germany. Any sign of slippage, whether through new spending measures or weaker growth, can push the risk premium higher.
I keep coming back to the simple observation that confidence is fragile. Once a market starts to question the long-term sustainability of debt dynamics, the adjustment can accelerate. That does not mean default risk is imminent. France remains a large, diversified economy with deep capital markets. It does mean the cost of maintaining investor trust has risen.
The Broader Eurozone Angle
France does not operate in isolation. Higher French yields tend to lift borrowing costs for other member states as well, especially those with larger debt loads. Contagion risk never fully disappears inside a currency union. When one large issuer faces pressure, the entire complex can reprice. That is why the move matters beyond Paris.
Some market participants still remember the sovereign debt tensions of the early 2010s. While the institutional architecture has improved since then, the fundamental tension between national politics and shared monetary policy remains. Street protests that force fiscal concessions in one country can raise questions about solidarity mechanisms across the bloc. Investors watch those questions closely.
In my view the most constructive path would involve clear communication from policymakers that fiscal rules still carry weight even amid social pressure. Markets reward predictability. They punish ambiguity. The current environment offers plenty of the latter.
Possible Paths Forward for the Market
No one knows exactly where yields settle from here. Several scenarios look plausible. One involves a relatively quick calming of the streets combined with reassuring budget statements. In that case the 5% print could prove temporary, a spike that fades as risk appetite returns. Another scenario sees prolonged unrest and incremental fiscal easing. Under that path yields could grind higher still, testing levels not seen in a generation.
A third possibility sits in between. Protests continue at a lower intensity while the government threads a careful path between social demands and market expectations. Yields might stabilize in a new, higher range without spiraling. That outcome would still leave borrowing costs permanently elevated relative to the post-crisis norm. For long-term investors that higher plateau matters more than any single daily close.
- Monitor the intensity and geographic spread of demonstrations
- Watch official statements on spending and taxation for signs of flexibility or restraint
- Track the spread versus German yields as a pure risk measure
- Follow secondary market liquidity and any unusual selling pressure from large holders
These signals will tell the story more clearly than any single yield level. I tend to pay closest attention to the spread rather than the absolute number. When that differential widens meaningfully, it usually means the market is differentiating more sharply between issuers. That differentiation can become self-reinforcing.
Implications for Portfolio Positioning
Anyone holding European fixed income has to decide how much exposure still makes sense. French government paper remains a core holding for many institutions because of its size and liquidity. Yet the risk-reward calculation has shifted. Some managers may choose to reduce duration or swap into higher-quality alternatives within the eurozone. Others will view the higher yields as an opportunity to lock in more attractive income if they believe the political noise will eventually fade.
Equity investors face a different set of questions. Higher sovereign yields can pressure valuation multiples, especially for rate-sensitive sectors. Banks sometimes benefit from steeper curves, yet they also carry sovereign debt on their balance sheets. The net effect depends on the path of yields from here and on the broader growth outlook. Uncertainty itself carries a cost.
I have found that the most resilient portfolios in these periods keep some dry powder. Opportunities often appear after the initial overshoot. Chasing the move higher in yields can prove expensive if calm returns faster than expected. Sitting entirely on the sidelines can prove equally costly if the higher rate regime proves durable. Balance remains the practical answer, even if it feels unsatisfying in the moment.
The Human Element Behind the Numbers
It is easy to treat bond yields as abstract data points. Behind them sit real decisions by families, companies, and governments. A protester in Marseille worried about next month’s rent is not thinking about the 10-year point on the curve. Yet the two stories are connected. Persistent social pressure can force policy choices that markets then price as higher risk. Higher risk feeds back into the very living costs that sparked the protests.
This feedback loop is what makes the current episode worth watching closely. Purely financial crises sometimes resolve through technical measures. Episodes that mix finance with visible social discontent tend to last longer and leave deeper marks. France has navigated difficult periods before. The question is how costly the navigation becomes this time.
When the street and the bond market start talking to each other, the conversation rarely stays polite for long.
I keep returning to that idea. Markets are efficient at processing information, yet they remain imperfect at pricing the full human dimension of political stress. The 5% print is a signal. What happens next will depend on how both sides of the equation, the political and the financial, choose to respond.
Looking Beyond the Immediate Spike
Over a longer horizon the French economy still possesses strengths that many other countries would envy: a large domestic market, high productivity in key sectors, and a capacity for policy innovation when circumstances demand it. Those strengths have supported the country’s credit standing through previous storms. They have not disappeared. What has changed is the starting point for public finances and the intensity of public dissatisfaction with living standards.
If policymakers can address the cost-of-living concerns without abandoning medium-term fiscal anchors, the bond market may eventually settle into a new equilibrium that still looks manageable. If the political response prioritizes short-term relief at the expense of longer-term credibility, the adjustment in yields could prove more permanent. Neither path is predetermined. Both remain open.
For observers outside France the episode offers a reminder. Sovereign risk inside the eurozone never fully vanished. It simply moved into the background during years of ultra-low rates and heavy central-bank support. As that support fades and domestic political pressures rise, the risk premium can reappear with surprising speed. The French 10-year yield at 5% is the latest illustration.
Practical Takeaways for Everyday Investors
Most individual investors will not trade French government bonds directly. They still feel the effects through mutual funds, pension performance, and the broader cost of credit. Understanding the forces at work helps set realistic expectations. Higher sovereign yields in a major economy rarely stay isolated. They influence global rate markets, currency moves, and risk appetite more generally.
One practical step is to review the duration of any fixed-income holdings. Longer-duration paper suffers more when yields rise. Another is to examine the geographic concentration of any European exposure. Diversification across issuers and across asset classes remains useful when one country’s political narrative turns turbulent. Finally, resist the urge to make large directional bets on the basis of a single yield level. Markets have a habit of overshooting in both directions.
In my own approach I prefer to treat these episodes as information rather than as immediate trading signals. The information right now is clear: political risk is back on the pricing screen for French debt, and the cost of that risk has risen enough to push yields to a multi-decade high. How long the premium stays elevated will depend on events that are still unfolding on the streets and in the halls of government.
The Quiet Role of Liquidity and Positioning
Behind every sharp yield move sits a mix of new information and existing positioning. Dealers and asset managers who had been comfortable with French exposure may have reduced risk once the protests intensified. That selling can exaggerate the initial move. Once the repositioning is complete, the market sometimes stabilizes even if the fundamental news remains mixed. Liquidity conditions matter too. Government bond markets are deep, yet they are not immune to temporary imbalances between buyers and sellers.
I have watched similar dynamics in other sovereign markets. The first few sessions after a shock often look worse than the ultimate destination. That observation does not guarantee a quick reversal this time. It does suggest that the path of yields from here will depend as much on how positioning evolves as on the next set of protest headlines.
One useful gauge is the behavior of the futures market and the willingness of dealers to warehouse risk. When those channels remain open and active, extreme moves tend to moderate. When they seize up, the adjustment can become disorderly. So far the French market has shown signs of strain without complete dysfunction. That distinction is worth monitoring in the sessions ahead.
Why This Episode Feels Different
Every market stress has its own flavor. What stands out here is the simultaneous presence of a clear social catalyst and a technical yield threshold that many investors had not expected to revisit soon. The combination creates a narrative that is easy for both domestic and international audiences to grasp. Stories that are easy to grasp tend to travel farther and last longer in market psychology.
Compare this moment with purely technical sell-offs driven by inflation data or central-bank speeches. Those episodes can reverse quickly once the data improves or the speech is digested. Social unrest is harder to time and harder to dismiss. It introduces a political dimension that pure macro models struggle to capture. That is why the current rise in French yields has drawn commentary well beyond the usual fixed-income circles.
Perhaps the most interesting aspect is how it forces a reassessment of what “safe” means inside the eurozone. Safety has always been relative. The relative ranking can change when domestic politics turn volatile. Investors are performing that ranking exercise in real time.
Final Thoughts on a Market Still in Motion
The French 10-year yield at 5% is more than a historical footnote. It is a live signal that political and social pressures can still move sovereign markets in meaningful ways. The protests over living costs have given that signal a human face. Whether the yield retreats or consolidates at higher levels will depend on how effectively policymakers balance immediate social demands against longer-term market credibility.
I do not claim to know the exact destination. What I do know is that ignoring the connection between the street and the bond market has rarely served investors well. The two arenas are talking to each other again. Listening carefully to both sides of that conversation remains the most practical course for anyone with exposure to European assets.
Markets will keep scoring the outcome session by session. The real test will come in the weeks and months ahead as the protests either fade or intensify and as fiscal choices become clearer. Until then the 5% level stands as a reminder that history can return to the present faster than most of us expect. The next chapters are still being written, both on the streets of French cities and on the screens of global trading floors.