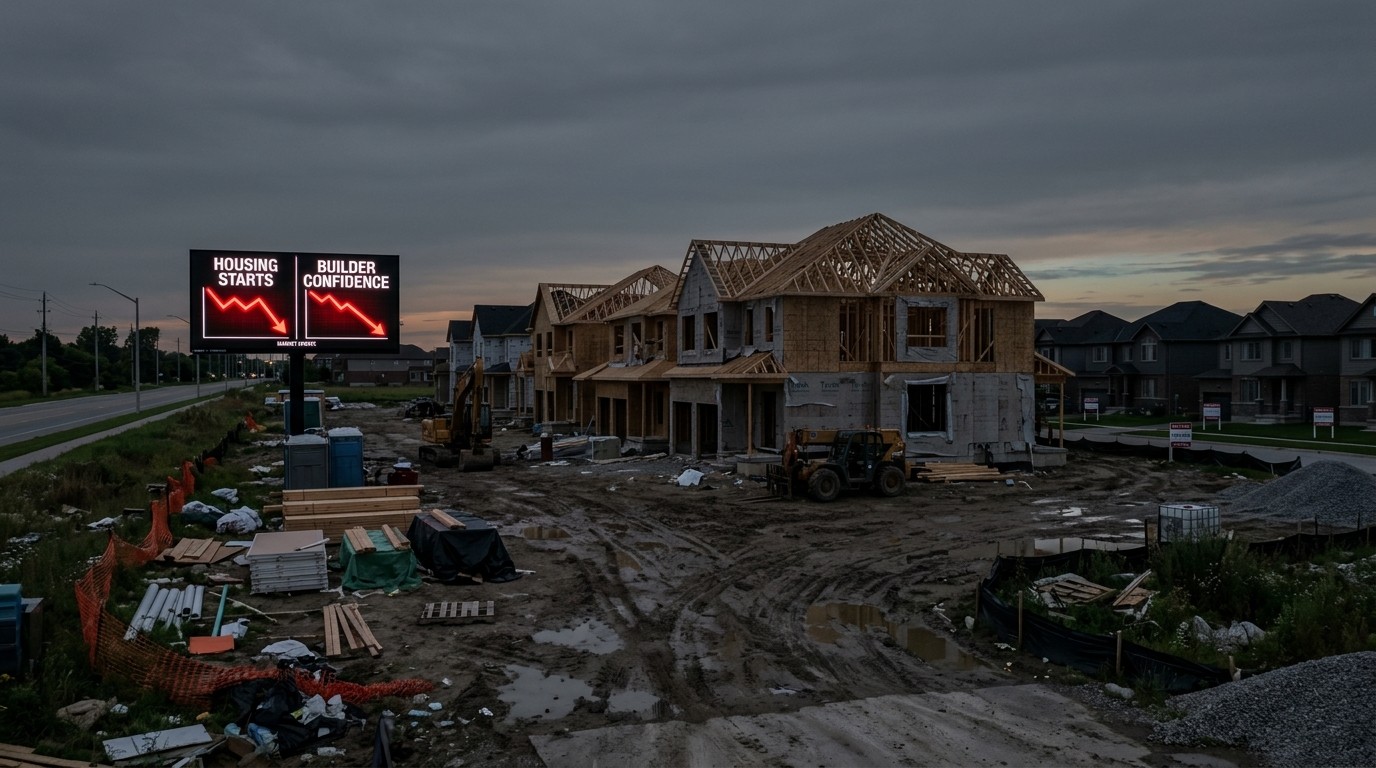

I still remember the spring of 2020 when everything stopped. Construction sites went quiet almost overnight. Fast forward a few years and here we are again, watching housing starts tumble toward those same uncomfortable lows. The latest numbers landed like a cold splash of water. Builders are pulling back hard, confidence has cratered, and the gap between what people already pay on their mortgages and what new buyers face feels wider than ever. Something has to give. The only real question is who moves first.
Why Housing Starts Are Sliding Toward Pandemic Territory
The September figures showed a clear 5.2 percent drop month over month. August got revised even lower, revealing a 5.9 percent plunge that nobody really wanted to see. On a seasonally adjusted annual rate basis, starts now sit uncomfortably close to the weakest levels recorded after the initial pandemic shock. Single-family construction, the backbone of the new-home market, hit its lowest point in a full year. That detail matters more than most people realize.
Permits, which usually give a better look at future activity, barely budged with a tiny 0.2 percent decline. They are hanging around the bottom of a four-year range. When builders stop requesting permission to build, they are telling you they do not like the outlook. I’ve watched this sector long enough to know that permits rarely stay flat for long. They either recover or they keep sliding. Right now the second option looks more likely.
The Confidence Collapse Nobody Can Ignore
Homebuilder confidence did not just dip. It crashed. Mortgage rates sit near 7.5 percent while the average rate across existing homeowners remains around 4.33 percent. That spread creates a powerful lock-in effect. Sellers refuse to give up their cheap financing. Buyers cannot stretch far enough to absorb the higher payments. Builders end up stuck in the middle with rising inventories and fading demand.
Some point to broader uncertainty, including geopolitical tension and shifting population patterns. Those factors play a role, no doubt. But the rate gap is the elephant in the room. Until that gap narrows in a meaningful way, builders have little reason to break ground on new projects. Throwing capital at a market that is already oversupplied with new homes feels like a poor bet.
When the cost of new money is nearly double the cost of old money, the entire housing ecosystem freezes. Nobody wants to be the first to move.
That observation captures the current mood better than any chart. Builders are not irrational. They simply refuse to add more supply into a market where finished homes already sit waiting for buyers who cannot quite make the numbers work.
Inventories Tell Their Own Story
New-home inventories have climbed to levels that should make any developer uneasy. When completed homes pile up, the pressure to cut prices or offer incentives grows quickly. Yet many builders still resist deep discounting because their own costs remain elevated. Labor, materials, and land have not gotten cheaper. The result is a quiet standoff. Homes sit. Time passes. Carrying costs accumulate.
I’ve spoken with people in the industry who describe the situation as a slow bleed rather than a sudden crisis. That description feels accurate. The market is not collapsing in dramatic fashion. It is simply grinding lower under the weight of financing realities that refuse to budge. Buyers keep waiting for rates to fall. Builders keep waiting for buyers to appear. Neither side is blinking yet.
The Rate Trap That Freezes Everything
Picture two families. One bought in 2021 with a rate near four percent. Their monthly payment feels manageable. The other family is shopping today and faces a payment that is hundreds of dollars higher for a comparable home. The first family has no incentive to sell. The second family has limited ability to buy. Multiply that situation across millions of households and you understand why transaction volumes have stayed depressed.
This lock-in effect is not new, but its intensity is. Previous cycles had smaller rate gaps. The current spread is extreme enough to change behavior in lasting ways. People stay put longer. They renovate instead of relocating. They delay family decisions. The ripple effects touch everything from furniture sales to local school enrollments.
- Existing homeowners enjoy payments far below current market levels
- Prospective buyers face monthly costs that strain household budgets
- Builders absorb carrying costs on unsold inventory
- Lenders see slower originations and thinner pipelines
Each of those groups is waiting for relief. The longer the wait continues, the more the market freezes in place. I’ve found that these periods of paralysis often end abruptly once rates move enough to restore some sense of normalcy. Until then, the numbers keep pointing in the same direction.
Single-Family Starts Hit a Yearly Low
The detail that stands out most is the drop in single-family construction to a one-year low. Multifamily activity can swing for its own reasons, often tied to apartment demand in specific metro areas. Single-family homes reflect broader household formation and confidence in long-term ownership. When that segment weakens, it signals deeper caution among both builders and buyers.
Some markets still show relative strength, particularly in areas with strong job growth or limited existing inventory. Those pockets are exceptions. The national picture remains soft. Builders who once raced to meet demand now carefully ration new starts. They prefer to finish what they already have under construction rather than open new phases of development.
In my view, this restraint is rational. Adding more homes into an environment of high rates and elevated finished inventory would only increase the eventual need for price adjustments. Better to wait and preserve margin than to force volume at any cost.
What the Numbers Really Mean for Buyers
Prospective buyers face a difficult calculation. Rates remain elevated. Home prices have not corrected enough in most places to offset the higher financing cost. The result is reduced purchasing power. Many households that could have comfortably afforded a home three years ago now find themselves priced out or forced to consider smaller properties farther from preferred locations.
Some buyers are adapting. They are bringing larger down payments, choosing adjustable-rate options, or looking at markets where prices have already softened. Others are simply waiting on the sidelines, hoping the next few months bring lower rates or more motivated sellers. Both strategies carry risk. Waiting too long can mean missing any eventual rebound. Acting too soon can lock in a high payment that feels burdensome later.
| Market Factor | Current Condition | Impact on Buyers |
| Mortgage Rates | Near 7.5 percent | Higher monthly payments |
| New Home Inventory | Elevated | More choices, possible incentives |
| Existing Home Supply | Still constrained | Limited options in many areas |
| Builder Confidence | Very low | Fewer new projects starting |
The table above simplifies a complex reality. Every local market has its own flavor. Still, the national trends create a consistent headwind. Buyers who can stay flexible on location or property type currently hold more leverage than they did during the frenzy years. That leverage is real, but it is not unlimited.
Builders Face Hard Choices Ahead
For homebuilders the path forward looks narrow. They can keep cutting starts and hope demand eventually improves. They can increase incentives and accept thinner margins. Or they can attempt to wait out the rate environment while managing cash flow carefully. None of those options feels ideal.
Labor availability has improved in some regions, yet skilled trades remain costly. Material prices have eased from their peaks but still sit well above pre-pandemic levels. Land positions acquired years ago now carry different economics than when they were purchased. Every new project has to clear a higher bar for expected returns.
I’ve noticed that the most disciplined builders are treating this period as a chance to clean up their balance sheets and focus on quality rather than quantity. They are finishing existing communities, improving specifications, and preparing for the moment when rates finally cooperate. That approach requires patience and strong financial backing. Not every company has both.
The Broader Economic Ripple Effects
Housing does not exist in isolation. When starts slow, the effects spread. Construction employment softens. Demand for lumber, concrete, appliances, and furnishings declines. Local governments collect less in permit fees and eventual property taxes. The multiplier is real and well documented.
At the same time, the lack of new supply helps support prices for existing homes in many markets. That support is a double-edged sword. It protects current owners from sharp declines but keeps affordability stretched for the next generation of buyers. The tension between those two groups sits at the center of the current debate.
Perhaps the most interesting aspect is how this cycle differs from past downturns. We are not seeing widespread forced selling or credit contraction of the kind that defined earlier crises. Instead we are watching a slow-motion adjustment driven almost entirely by the cost of money. That distinction matters for how the eventual recovery might unfold.
Looking at Historical Parallels Without the Panic
Every cycle invites comparisons. Some observers reach for 2008. Others point to the early 1980s when rates were even higher. Neither parallel fits perfectly. Credit standards today remain far tighter than they were before the financial crisis. Household balance sheets, while stretched for some, do not show the same level of over-leverage that existed then.
The closer comparison might be periods of rapid rate increases that simply paused activity until financing conditions improved. In those episodes the market did not disappear. It waited. When rates eventually declined enough to restore affordability, pent-up demand returned with surprising force. Whether that pattern repeats this time remains an open question.
What feels different now is the sheer size of the rate gap. Previous pauses did not feature such a large disparity between existing and new financing costs. That gap may prolong the current pause longer than historical averages would suggest.
Regional Differences Still Matter
National numbers hide important variation. Some Sun Belt markets that expanded rapidly in recent years now show clearer signs of oversupply. Other regions with stronger job markets and tighter land constraints continue to see more resilient demand. Coastal markets often behave differently from inland ones. Understanding those differences is essential for anyone trying to interpret the data.
Migration patterns continue to shift. Remote work has lost some of its pandemic-era intensity, yet enough flexibility remains to influence where people choose to live. Builders who positioned themselves in high-growth corridors still have advantages. Those who chased the hottest temporary trends face harder adjustments.
- Identify local inventory levels relative to historical norms
- Track job growth and household formation in the specific metro
- Monitor how aggressively local builders are cutting prices or offering incentives
- Watch for any signs that existing homeowners are becoming more willing to list
Those four steps form a practical checklist for anyone evaluating a particular market. National headlines provide the backdrop. Local data determine the actual opportunity or risk.
What Would Need to Change for a Turnaround
Several things could unlock the market. A sustained decline in mortgage rates would help the most. Even a move back toward six percent would restore meaningful purchasing power for many households. Greater willingness among existing owners to sell, perhaps driven by life events that outweigh the rate advantage, would increase available inventory of lower-rate homes. Builders offering more aggressive pricing or financing incentives could also clear some of the current backlog.
None of those catalysts appears imminent. Rates have proven sticky. Existing owners remain reluctant. Builders prefer to protect margins when possible. The stalemate continues.
In my experience, markets like this often resolve through a combination of gradual rate relief and selective price adjustments rather than a single dramatic event. The process feels slow while it is happening. Looking back later, the adjustment usually appears more orderly than it felt at the time.
The Human Side of the Numbers
Behind every start and every permit sits a family decision. Young couples delaying their first purchase. Growing households staying in smaller homes longer than planned. Older owners postponing downsizing because the math no longer works. These individual choices add up to the aggregate data we watch so closely.
I’ve heard stories of people who stretched to buy at the peak and now feel trapped by both high payments and limited equity cushions. I’ve also heard from renters who keep waiting for the perfect moment that never quite arrives. The emotional weight of housing decisions has always been heavy. The current environment makes it heavier still.
That human element is easy to lose when staring at charts. Yet it remains the core of the market. Homes are not just assets. They are the places where life happens. When the system that delivers those places slows down, the effects reach far beyond construction statistics.
Practical Considerations for Different Players
For potential buyers the current environment rewards preparation and patience. Strengthening credit profiles, accumulating larger down payments, and remaining open to a wider range of locations all improve options. Some will find opportunities in the new-home sector where builders are more motivated to negotiate.
For existing owners the calculation is different. Those who need to move for work or family reasons may have to accept that their next mortgage will cost more. Others can continue to enjoy the advantage of their lower existing rates and simply wait for better conditions.
Investors face their own set of trade-offs. Cap rates, financing costs, and rent growth expectations all look different than they did a few years ago. Selective opportunities still exist, particularly where motivated sellers appear or where local fundamentals remain strong. Broad, leveraged bets on rapid appreciation look less attractive.
Why This Moment Feels Different
Previous soft patches in housing often came with clearer signals of an approaching bottom. Excess inventory would clear. Rates would fall. Builders would eventually respond. The current episode features high finished inventory alongside still-constrained existing supply and a rate environment that shows little urgency to improve. That combination is unusual.
Another difference is the sheer volume of homes built during the low-rate years that now sit with owners who have no desire to trade out of their financing. That stock of low-rate mortgages acts like a giant weight on transaction volume. Until enough of those owners decide the benefits of moving outweigh the cost of higher rates, the market will remain less fluid than normal.
I’ve come to see this period as a structural adjustment rather than a typical cyclical downturn. The adjustment will end eventually. The path and the timeline remain uncertain.
Keeping Perspective Amid the Noise
It is easy to get lost in monthly releases and confidence surveys. The longer view still matters. Household formation continues. People still need places to live. Construction technology and building practices continue to evolve. The fundamental demand for housing has not disappeared. What has changed is the cost of financing that demand.
When financing costs eventually ease, the response could be sharp. Years of delayed purchases and postponed moves create a reservoir of potential activity. The timing of that release remains the great unknown.
Until then, the data will likely keep showing soft starts, cautious builders, and a market waiting for its next clear signal. Watching that process unfold requires patience. Acting within it requires clear eyes and realistic expectations.
The housing market has always moved in long waves rather than straight lines. We are currently in one of the quieter, more frustrating stretches of the cycle. Those stretches do not last forever. They do, however, reward the people who stay informed, stay flexible, and refuse to force decisions that the numbers do not yet support.
For now the message from the latest starts and confidence data is straightforward. Builders are stepping back. Buyers remain hesitant. Inventories of new homes sit elevated. The rate gap continues to dominate every conversation. Who blinks first will determine how the next chapter is written. Until that moment arrives, the market will keep grinding forward in its current constrained fashion, one cautious decision at a time.
The numbers are clear enough. Housing starts have fallen close to levels last seen during the depths of the pandemic disruption. Builder sentiment has followed the same downward path. The forces holding the market in place are powerful and interconnected. Understanding those forces, rather than simply reacting to each new data point, offers the best chance of navigating what comes next.
Whether you are watching from the sidelines, actively shopping, or managing a construction business, the same principle applies. Respect the rate environment. Watch inventory carefully. Stay ready for the shift when it finally arrives. The market always moves again. The only real question is how prepared you will be when it does.