

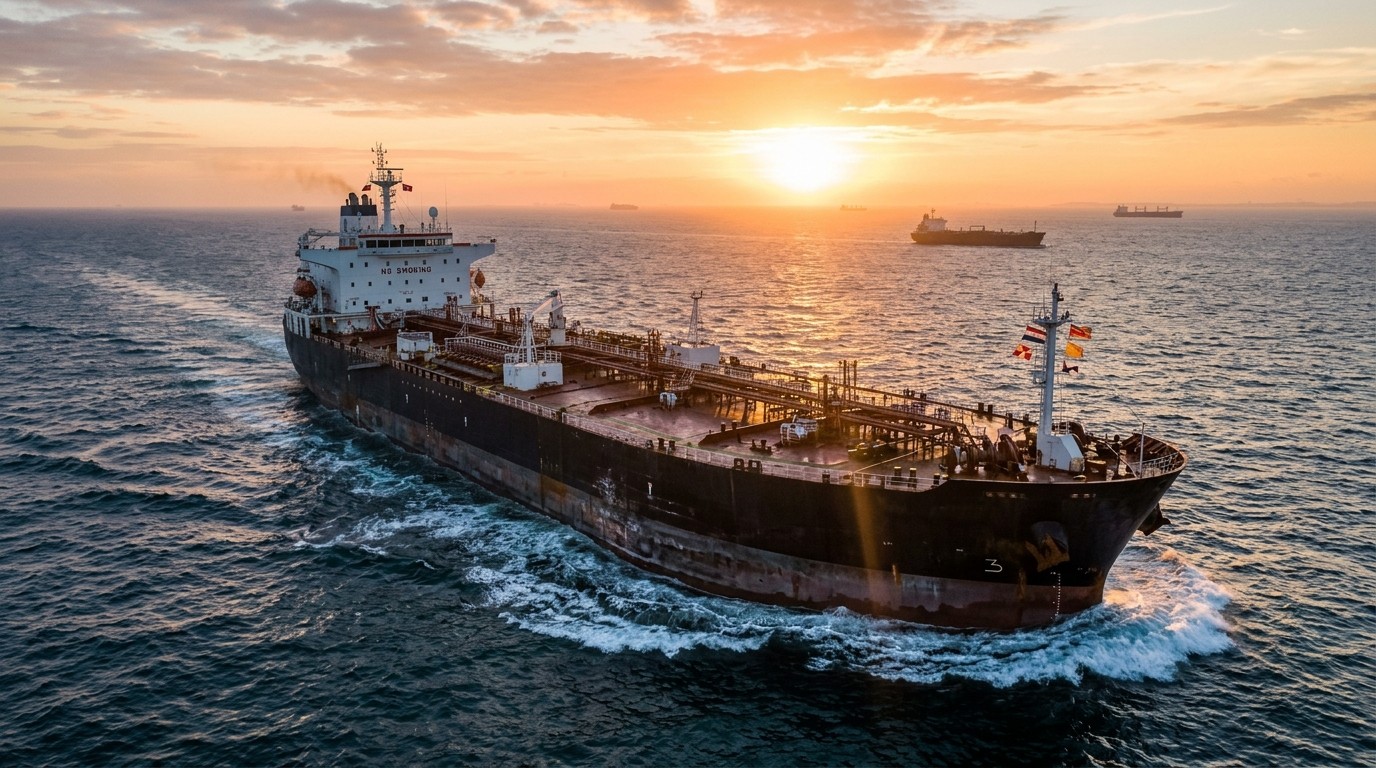

Have you noticed how the price at the diesel pump has climbed faster than almost anything else lately? Last week I was talking with a friend who runs a small trucking outfit out of the Midwest, and he told me his fuel bill had jumped so high he was considering cutting routes just to stay solvent. That conversation stuck with me because it isn’t an isolated story. Across farms, logistics yards, and construction sites, people who rely on diesel every day have been feeling a squeeze that started months ago and shows no sign of easing on its own. Then, almost overnight, news broke that a Russian tanker loaded with 40,000 metric tons of diesel is setting sail for the United States. It is the first shipment under a fresh understanding between Washington and Moscow, and it arrives at a moment when refining capacity worldwide is under real stress. Whether this single vessel changes the picture remains an open question, but the timing alone makes it hard to ignore.
Why This Tanker Matters Right Now
The vessel is not just another cargo ship. It is the opening move in a sequence of deliveries that Russian officials say will continue through the coming weeks. The first load equals roughly 300,000 barrels of industrial fuel. Additional volumes are expected later in the month and into November, with the possibility of substantially larger quantities after that. On paper the numbers look meaningful. In practice they have to be measured against a market that has already absorbed repeated shocks.
What makes the moment unusual is the combination of factors that pushed diesel into short supply in the first place. Ukrainian strikes on Russian energy infrastructure reduced the volume of refined products leaving Russian ports. At the same time, uncertainty around the Strait of Hormuz has kept a risk premium embedded in crude and product prices. When one major refining region is impaired and a critical transit route remains under threat, the downstream effects show up quickly in the price of diesel and heating oil. American farmers who need fuel for harvest equipment and long-haul truckers who move goods across the country have both felt the impact. In my experience watching these cycles, once diesel inventories tighten, the recovery tends to be slower than most people expect because refining capacity cannot be switched on overnight.
The Immediate Logistics of the First Shipment
According to statements from Russian energy officials, the tanker will begin its transit shortly. The cargo is already loaded, and the vessel is positioned to leave port within days. Financial arrangements still need to be finalized so that payment clears without friction, but both sides appear confident that the mechanics can be completed. A U.S. special envoy who met with Russian leadership this week publicly thanked Moscow for lifting export controls on diesel and for agreeing to sell into the American market as well as more broadly. That public acknowledgment is worth noting. It signals that the arrangement is not purely commercial; it carries a political dimension as well.
The first cargo is modest relative to total U.S. diesel consumption, which runs in the millions of barrels per day. Still, in a market that is already tight, an incremental 40,000 tons can influence sentiment and, at the margin, physical availability. Subsequent vessels are expected to follow in relatively quick succession. Russian officials have indicated they are preparing several ships at once so that deliveries can arrive one after another rather than in a single large batch. That staggered approach may help avoid port congestion while still providing a steady flow.
We are preparing deliveries of several vessels right now. They will go one after another. The financial component should be provided.
– Senior Russian official
Those words capture the practical side of the arrangement. The hardware—the ships and the cargo—is ready. The remaining work is administrative and financial. Once that is settled, the physical movement of fuel can begin in earnest.
Volumes and the Timeline Ahead
The initial commitment involves 300,000 metric tons in the near term, followed by another 500,000 tons in November, with the potential for one million tons thereafter. Converted into barrels, the early tranche equals about 2.25 million barrels. That is not enough to flood the market, but it is enough to register on trading screens and in inventory reports. Markets reacted almost immediately to the announcements. Global diesel prices eased by roughly five to six percent in the hours after the statements were made public. The move was modest, yet it showed that traders are pricing in at least some additional supply.
I’ve found that product markets often overreact to headlines and then settle once the actual barrels start to move. If the tankers arrive on schedule and the fuel is of acceptable quality, the price response could deepen. If delays appear or if quality issues surface, the relief may prove temporary. Either way, the next several weeks will provide clearer data points than the current statements alone.
| Shipment Window | Approximate Volume (metric tons) | Notes |
| Immediate | 40,000 | First tanker now loading or under way |
| Near term | 300,000 total | Initial agreed tranche |
| November | 500,000 | Follow-on commitment |
| Thereafter | Up to 1,000,000 | Conditional on continued agreements |
The table above lays out the publicly discussed numbers. Actual delivered volumes will depend on vessel availability, weather, and the speed with which payment channels are confirmed. Still, the sequence suggests a deliberate effort to move product rather than a one-off gesture.
The Broader Refining Backdrop
To understand why this arrangement is drawing attention, it helps to look at the refining picture that developed over the past year. Multiple Ukrainian operations targeted Russian refining and storage sites. Those strikes reduced the volume of diesel and other products available for export. At the same time, several refineries in other regions have been operating below capacity because of maintenance, unplanned outages, or feedstock constraints. The result has been a tighter global balance for middle distillates—the category that includes diesel and heating oil.
Compounding the issue is the ongoing uncertainty surrounding the Strait of Hormuz. When a major producer signals that it may assert greater control over the waterway, traders embed a risk premium in crude prices. That premium flows through to refined products. Even if the physical disruption never materializes, the mere possibility keeps prices elevated. Energy analysts at major banks and at the International Energy Agency have both cautioned that relief is unlikely to arrive quickly. The refining system simply does not have spare capacity that can be brought online in a matter of weeks. Any recovery will be gradual and will depend on both new supply and a reduction in the geopolitical risk premium.
Perhaps the most interesting aspect of the current situation is how quickly the U.S. and Russian sides found a channel for diesel specifically. Crude oil has faced various restrictions for years, yet refined products have sometimes moved under different rules. The decision to lift export controls on diesel and to direct a portion of that flow toward the United States appears to reflect a calculation that both sides benefit from lower prices and from reduced tension around energy. Farmers and truckers were mentioned explicitly in the public remarks. Those groups form a politically visible constituency, and their costs feed directly into food prices and consumer goods.
Effects on American Consumers and Businesses
Diesel is not the fuel most people put in their personal cars, but it powers the trucks that deliver almost everything else. When diesel prices rise, the cost of moving goods rises with them. Those costs eventually appear on store shelves, in construction bids, and in farm operating expenses. A sustained decline in diesel prices would therefore offer broader relief than a drop in gasoline alone. The question is how much of the new Russian supply will actually reach U.S. terminals and how quickly it will be distributed inland.
U.S. Energy officials have indicated that retail prices may have already peaked, yet independent analysts remain more cautious. They point out that inventories of distillates remain low relative to seasonal norms and that refining margins, while elevated, have not yet collapsed. If the Russian cargoes arrive and are accepted by refiners or blenders, they could help rebuild those inventories. If, on the other hand, the volumes are smaller than advertised or face logistical hurdles, the market may stay tight into next year. In my view the prudent assumption is that any relief will be partial and uneven rather than sudden and complete.
- Truckers and logistics firms will watch terminal prices closely over the next month.
- Farmers preparing for spring planting will look for signs that fertilizer and fuel costs are stabilizing together.
- Retailers may begin to factor lower transportation costs into their pricing decisions if the trend holds.
- Refiners on the U.S. Gulf Coast and East Coast will evaluate whether the incoming material complements their own production.
Each of those groups has a slightly different exposure. A national average price tells only part of the story; regional differentials matter as well. Ports that can receive the tankers will see the benefit first. Areas farther inland may wait longer for the barrels to move through pipelines or by rail.
Fertilizer as a Parallel Track
Russian officials also noted that large quantities of fertilizer could be supplied alongside the diesel. Fertilizer markets have been volatile for their own reasons, and many American growers have faced higher costs for nitrogen and other nutrients. A reliable additional source of fertilizer would complement the diesel arrangement and could ease another major input cost for agriculture. Details on volumes and timing for fertilizer have not been spelled out as clearly as the diesel numbers, yet the mention itself suggests that the broader energy-and-agriculture dialogue is continuing.
From a practical standpoint, fertilizer shipments often move on different vessels and through different terminals than refined fuels. Coordinating both flows would require additional logistical planning, but the willingness to discuss both commodities in the same meetings indicates a wider scope than diesel alone. If those fertilizer cargoes materialize, the combined effect on farm economics could be more noticeable than the diesel shipments by themselves.
Geopolitical Context and Market Sentiment
The diesel arrangement sits inside a larger set of conversations between the two governments. A U.S. envoy held talks in St. Petersburg this week, and the public remarks about diesel formed part of that exchange. Markets tend to treat such statements as signals. When both sides publicly confirm that export controls have been lifted and that shipments are being prepared, traders reduce the probability they assign to further disruption. That adjustment in probabilities is what produced the immediate five-to-six-percent decline in diesel prices.
At the same time, crude oil remains elevated. Brent has traded near multi-year highs, driven primarily by the Hormuz risk premium. One analyst noted that the primary driver continues to be the threat to flows through the strait, with officials from a key regional producer stating they have little choice but to assert influence over the waterway. As long as that uncertainty persists, crude—and therefore the feedstock for diesel—will carry a higher floor price. The Russian product shipments can ease the refined-product balance, yet they cannot remove the crude risk premium by themselves.
I’ve watched similar episodes before. In past periods of tight distillate markets, incremental supply from unexpected sources has sometimes calmed prices for a few weeks only to see them rebound when the next geopolitical headline appears. The durability of any relief this time will depend on whether the tanker program continues without interruption and whether the Hormuz situation stabilizes. Neither outcome is guaranteed.
What Traders and Analysts Are Watching
Several concrete data points will shape the next phase of market reaction. Vessel tracking will show whether the first tanker departs on schedule and whether additional ships load behind it. Customs and terminal data in the United States will reveal when the cargo actually arrives and how it is distributed. Weekly inventory reports from government agencies will indicate whether distillate stocks begin to rebuild. Finally, statements from both governments about further volumes or about related issues such as fertilizer will either reinforce or undercut the initial narrative.
Price action itself will provide a running commentary. If diesel futures continue to ease relative to crude, that would suggest the market is pricing in additional product supply. If the crack spreads remain wide, traders are signaling that they still see scarcity. Either reading can change quickly once the physical barrels start to move.
- Confirm departure of the first tanker and its estimated arrival window.
- Track subsequent loadings to verify that the staggered delivery plan is holding.
- Monitor U.S. distillate inventory builds over the next four to six weeks.
- Watch for any clarification on fertilizer volumes and timing.
- Assess whether the Hormuz risk premium in crude begins to recede.
These five items form a practical checklist. None of them requires special access; most of the information will appear in public shipping data, government reports, and market commentary. What differs this time is the direct involvement of senior officials on both sides in confirming the commercial flow.
Potential Complications and Uncertainties
No arrangement of this kind is free of friction. Payment channels must function smoothly, especially given the layers of financial restrictions that have accumulated over recent years. Insurance for the vessels and cargoes must be available at acceptable rates. Port authorities on the U.S. side must clear the ships and the product. Quality specifications must be met so that the diesel can be blended or sold without extensive reprocessing. Any of these steps can introduce delays even when both governments support the overall plan.
There is also the question of sustainability. The current volumes are framed as an initial response to acute tightness. If refining capacity elsewhere recovers or if the geopolitical risk premium falls, the commercial incentive for continued large-scale shipments may diminish. Conversely, if disruptions persist, both sides may have reason to expand the flow. The public statements so far have been carefully worded to leave room for either outcome.
From a market perspective, the most useful stance is to treat the announced volumes as a base case rather than a ceiling or a floor. Additional barrels help, yet they do not eliminate the underlying constraints on global refining or the residual risk around major transit routes. Prices can still move sharply on news that has nothing to do with this particular tanker program.
Longer-Term Implications for Energy Trade
If the diesel shipments continue and expand, they would represent a partial reopening of refined-product trade between the two countries. That trade had narrowed considerably in prior years. A sustained flow would not restore the pre-existing pattern overnight, but it would demonstrate that commercial channels can be reactivated when both sides see mutual advantage. Other products—fertilizer being the most obvious—could follow a similar path if the diesel experiment proceeds without major obstacles.
For American consumers the practical test is simpler: do pump prices and wholesale diesel costs stabilize or decline over the next two to three months? For refiners and traders the test is whether the incoming material alters crack spreads and inventory trajectories in a measurable way. For policymakers the test is whether the arrangement reduces one source of inflationary pressure without creating new complications elsewhere. Each of those tests will take time to answer.
In the meantime the first tanker is preparing to leave port. Its departure will not solve the refining shortfall by itself, nor will it remove the risk premium that still sits in crude prices. It does, however, mark a concrete step that was not on the calendar a few weeks ago. Markets will price the barrels as they move, and businesses that consume diesel will adjust their plans accordingly. The next several weeks of shipping data and inventory reports will show whether this opening shipment is the start of a steadier flow or simply a one-time response to an acute shortage. Either result will be informative. For now, the vessel is the clearest signal yet that both governments are willing to move product rather than merely discuss it.
Additional context on related market dynamics continues to develop. Refining margins in other regions remain elevated, and several independent analysts have noted that spare capacity is limited even if the Russian volumes arrive as planned. Seasonal demand for heating oil in the Northern Hemisphere will add another layer of pressure if inventories do not rebuild before colder weather sets in. Those factors sit alongside the tanker program rather than being replaced by it. The combination suggests that while the new supply is welcome, it forms only one piece of a still-constrained global balance.
Observers who follow physical oil markets have also pointed out that the quality and specification of the Russian diesel will matter once it reaches U.S. terminals. Different refineries and blenders have different requirements. If the material meets standard specifications with minimal adjustment, it can enter the supply chain relatively quickly. If adjustments are needed, the effective volume available for immediate use could be smaller than the headline tonnage. Early indications from officials have been positive, yet the real test occurs when the cargo is sampled and cleared.
Another variable is the pace at which financial channels are confirmed. Both sides have stated that the commercial terms can be arranged, yet the practical work of opening accounts, confirming compliance, and arranging payment still has to be completed for each vessel. In past episodes involving restricted counterparties, those steps have occasionally taken longer than the physical loading itself. Any lag would push the arrival of subsequent cargoes further into the future and would limit the near-term impact on inventories.
Looking beyond the immediate shipments, the broader question is whether this episode leads to a more regular pattern of refined-product trade or remains an exceptional response to a specific shortage. The public language so far has emphasized meeting needs “to the extent of our capabilities,” which leaves the scale flexible. If demand stays strong and other supply sources remain constrained, the incentive to continue will be clear. If alternative barrels appear or if consumption softens, the volumes could taper. Markets will have to price that optionality rather than treat the current numbers as fixed.
For businesses that budget fuel costs months in advance, the prudent approach is to treat the new supply as a helpful but not decisive factor. Hedging strategies that already account for elevated distillate prices do not need to be abandoned overnight. At the same time, the existence of an additional source reduces the probability of an even sharper spike if other disruptions occur. That modest reduction in tail risk is itself valuable, even if the central forecast for prices changes only gradually.
In conversations with logistics managers over the past month, the dominant theme has been uncertainty rather than outright shortage. Most operators have been able to obtain fuel, yet the price has forced them to reexamine routes, loads, and customer contracts. A visible decline in wholesale diesel would give those managers more room to plan. Whether the Russian cargoes produce that decline will become clearer once the first tanker reaches its destination and the second and third vessels are confirmed under way. Until then, the market is operating on statements and on the initial price reaction rather than on delivered barrels.
The same caution applies to agricultural buyers. Fertilizer discussions remain preliminary, and diesel for spring fieldwork is still months away. Growers who locked in portions of their fuel and nutrient needs earlier in the year are relatively insulated. Those who delayed purchases are watching the tanker program more closely. A combination of lower diesel and additional fertilizer availability would improve margins, yet neither outcome is assured until the cargoes are booked and shipped.
Energy-market participants have also noted that the arrangement does not alter the fundamental refining capacity picture outside Russia. Several large refineries in other countries remain offline or reduced for maintenance or damage. Bringing that capacity back online will take time regardless of how many Russian tankers sail. The new supply can fill part of the gap, but it cannot substitute for repairs and restarts elsewhere. That distinction helps explain why many analysts continue to forecast tight conditions well into next year even after accounting for the announced volumes.
One under-appreciated element is the signaling effect on other potential suppliers. When a major producer publicly commits to directing product toward a specific market, other exporters sometimes adjust their own allocations. If the Russian program proceeds smoothly, it could encourage additional offers from elsewhere or, conversely, prompt some sellers to hold back in anticipation of lower prices. Those second-order reactions are difficult to predict in advance and usually become visible only after several weeks of actual trade.
For now the focus remains on the first vessel and the vessels queued behind it. Their movement will provide the first hard data on whether the stated intentions translate into physical supply. Markets have already priced a portion of that supply; the remainder will be priced as the ships leave port and as the cargoes clear U.S. terminals. In the interim, diesel consumers continue to operate under elevated costs, and the broader crude complex continues to reflect risks that sit outside this particular commercial channel. The tanker is a tangible development, yet it is still only one development inside a larger and still unsettled energy landscape.
Further updates will likely arrive through shipping reports, official inventory statistics, and any additional comments from the officials involved in the talks. Each new piece of information will either confirm the trajectory outlined this week or introduce adjustments. Until those data points accumulate, the most accurate description is that a previously closed channel for diesel has been reopened on a limited scale, with the explicit goal of easing pressure on American users and on global prices. How far that channel extends, and how long it remains open, will be determined by the practical results of the shipments now being prepared.



