
When a defense company suddenly reports that its new orders have more than tripled in a single quarter, you sit up and take notice. That is exactly what happened with Saab this week. The Swedish aerospace and defense group delivered third-quarter numbers that not only beat expectations but painted a picture of a sector finally shifting from long-term pledges to actual contracts.
I have followed defense stocks for years, and moments like this feel rare. Governments talk about higher spending for months or even years. Then, almost overnight, the orders land and the numbers jump. Saab’s latest results capture that transition in real time.
What the Latest Quarterly Numbers Actually Reveal
Third-quarter sales came in at 20.6 billion Swedish kronor. That figure sat comfortably ahead of the consensus estimate of around 20 billion. Earnings before interest and taxes reached 1.95 billion kronor, also slightly better than the 1.9 billion most analysts had penciled in. Solid, but not spectacular on their own.
The real story sits in the order book. New orders hit 65.8 billion kronor, up sharply from 20.9 billion in the same period a year earlier. That is more than a threefold increase. The market had expected something closer to 56.4 billion, so the beat was meaningful. In my view, order intake of this scale changes the narrative for the entire company.
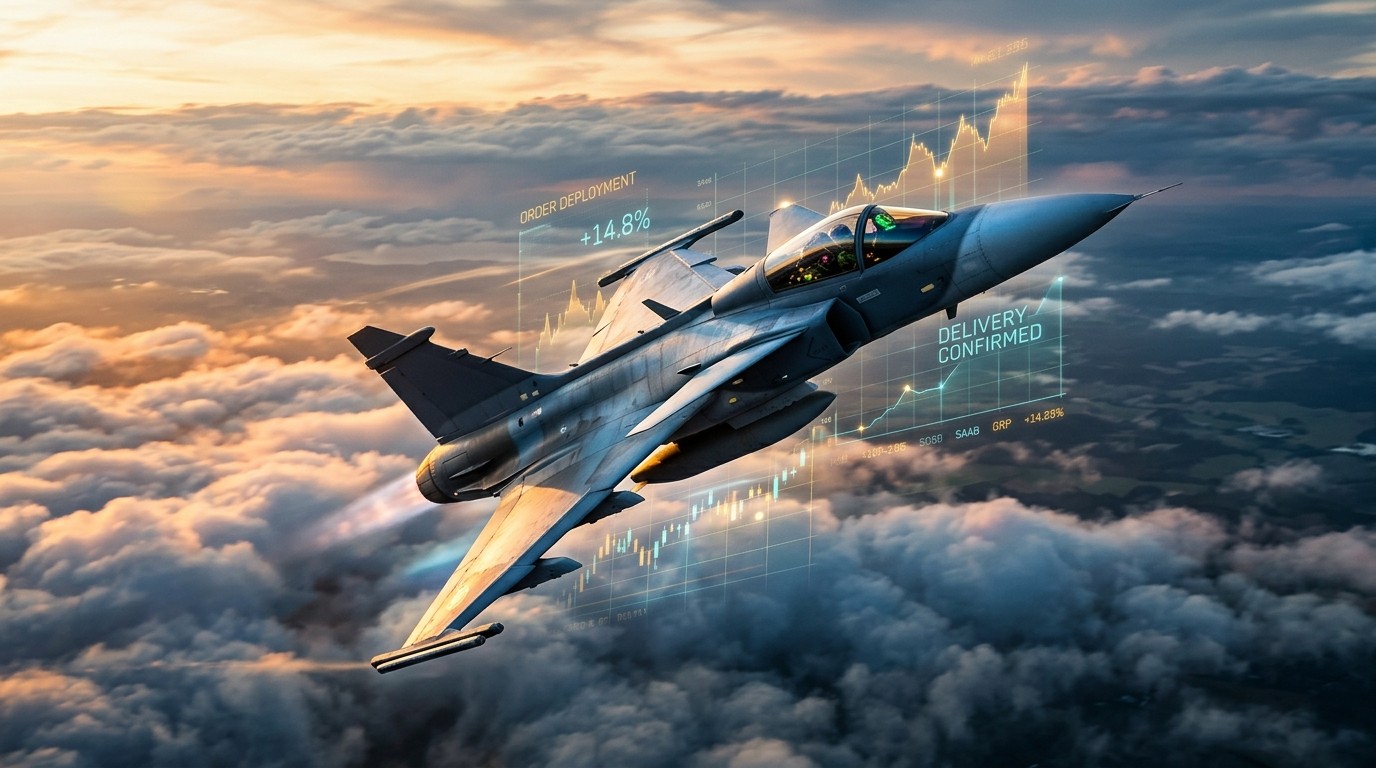
One single contract explained a large portion of the jump. A deal for 16 Gripen E fighter jets destined for Ukraine, valued at roughly 24.6 billion kronor, was signed earlier in the year and formally booked during the third quarter. That single line item alone accounts for a substantial share of the overall order growth.
The Gripen Contract That Moved the Needle
The Ukraine order is not just another sale. It represents a concrete step in Europe’s effort to support a partner under pressure while simultaneously building industrial capacity at home. The Gripen E is a modern, multi-role fighter designed for high performance with relatively lower operating costs than some larger Western jets. For a nation needing capable aircraft quickly, that combination matters.
Saab’s chief executive noted that growing customer demand shows up in major awards, including the Gripen package for Ukraine, GlobalEye systems, and work connected to Germany’s new frigate program. Those comments feel measured rather than boastful. The company is simply stating what the numbers already show.
The growing customer demand is reflected in major contract awards, including Gripen for Ukraine, GlobalEye and an order related to Germany’s new frigates.
I find the breadth of that demand particularly interesting. Fighter jets grab headlines, yet the company is also booking surveillance platforms and naval systems. That diversity reduces reliance on any single product line and gives the order book more resilience.
Why European Defense Spending Is Finally Turning Into Contracts
For the better part of two years, European governments have talked about raising defense budgets. Pledges made at various summits created optimism among investors. Actual contracts, however, lagged. Production lines need firm orders before they can expand capacity with confidence.
What we are seeing now looks like the beginning of that conversion process. Nations are moving from announcements to signed deals. Ukraine’s need for modern aircraft created urgency, while other European programs continued in parallel. The result is a noticeable uptick in order flow for companies that already possess proven platforms and production experience.
Perhaps the most interesting aspect is the speed. Defense procurement traditionally moves at a glacial pace. When geopolitical pressure intensifies, that process can accelerate. Saab appears to be one of the beneficiaries of that acceleration.
Breaking Down the Financial Highlights
Looking past the headline order number, a few other details deserve attention. Sales growth remained healthy even without the full impact of the largest new contracts yet flowing through the income statement. That suggests the underlying business continues to execute on previously booked work.
Profitability held up as well. Hitting 1.95 billion kronor in EBIT while still ramping certain programs indicates reasonable cost control. Defense companies often face margin pressure during periods of rapid order growth because they invest ahead of revenue recognition. Saab seems to be managing that balance carefully so far.
The order backlog itself provides multi-year visibility. Large fighter jet programs typically span several years from first delivery to final handover. Once booked, those contracts support production planning, workforce decisions, and supplier relationships for a long stretch of time.
- New orders of 65.8 billion kronor versus 20.9 billion a year earlier
- Sales of 20.6 billion kronor, ahead of the 20 billion consensus
- EBIT of 1.95 billion kronor versus expected 1.9 billion
- Major contribution from the 24.6 billion kronor Gripen package
Those four data points together form a coherent picture of a company whose commercial momentum has improved markedly.
Broader Implications for the Defense Sector
Saab is not operating in isolation. Other European defense firms have also reported stronger order intake over the past year. The common thread is government prioritization of capability over pure cost minimization. Speed of delivery and proven technology now carry greater weight in many procurement decisions.
Investors watching the sector should note that order growth tends to lead revenue growth by a noticeable lag. The contracts signed this year will support sales figures well into the second half of the decade. That lag can create periods where stock prices react to order news while actual earnings still reflect older, smaller programs.
In my experience, markets sometimes underestimate how long it takes for a large defense order to translate into steady cash flow. The opposite can also occur. Once production stabilizes and learning curves improve, margins often expand. Timing those transitions requires patience.
The Role of Diversified Product Lines
Beyond the headline Gripen deal, Saab continues to win work in airborne early warning and naval systems. GlobalEye represents a sophisticated surveillance solution that several countries have already selected or are evaluating. Naval programs, including components for German frigates, add further breadth.
This mix matters because fighter jet sales can be lumpy. A company that also sells sensors, command systems, and underwater technology enjoys smoother order patterns over time. The current quarter illustrates that advantage. Multiple product areas contributed to the elevated intake rather than a single outlier contract carrying everything.
I have always preferred defense companies that maintain several strong franchises. Concentration risk in one platform can create volatility when political or budgetary winds shift. Saab’s current portfolio looks reasonably balanced on that score.
What Investors Should Watch Next
Several follow-up questions emerge from these results. First, how quickly can production capacity expand to meet the new demand? Fighter jet manufacturing involves complex supply chains and skilled labor. Accelerating output without quality issues is never trivial.
Second, will additional European nations place further Gripen orders or expand existing fleets? Momentum in one country often influences decisions elsewhere, especially when industrial participation packages form part of the negotiation.
Third, how will the company manage working capital as it ramps larger programs? Defense firms frequently experience cash outflows early in production cycles before customer payments catch up. Strong order books can coexist with temporary pressure on free cash flow.
Finally, the broader geopolitical environment remains fluid. Continued support for Ukraine and sustained commitment to higher European defense spending will influence the duration of the current upcycle. Any significant shift in political priorities could alter the trajectory, though that does not appear imminent.
Comparing Current Momentum With Past Cycles
Defense industry cycles tend to last longer than many other industrial cycles. Once budgets rise and programs launch, they often continue for a decade or more. The opposite is also true. Periods of underinvestment can stretch for years until a crisis forces reassessment.
The current environment feels different from the post-Cold War drawdowns or the more recent years of constrained European spending. Threat perception has shifted. Industrial base concerns have become more prominent. Both factors support a multi-year period of elevated demand.
Saab entered this period with established products and existing production infrastructure. That positioning allowed the company to capture early contracts while competitors still ramped capacity. First-mover advantages in defense can prove durable because switching costs and certification requirements are high.
Looking at the Numbers in Context
Putting 65.8 billion kronor of new orders into perspective helps. The figure represents more than three times the prior-year level and exceeds consensus by a clear margin. Even if one adjusts for the large Ukraine contract, underlying demand still appears stronger than a year ago.
Sales growth of roughly the magnitude reported here keeps the company on a solid trajectory. More importantly, the composition of that growth includes both volume and the gradual shift toward higher-value systems. Over time that mix improvement can support margins.
I tend to focus less on any single quarter’s profit figure and more on the direction of the order book. Orders today become revenue tomorrow and cash flow the day after. On that measure, Saab’s third-quarter report looks constructive.
Risks That Still Deserve Attention
No outlook is risk-free. Execution risk on large programs always exists. Delays, cost overruns, or technical issues can erode the economics of even well-structured contracts. Saab has a track record of delivering complex systems, yet every new production ramp brings fresh challenges.
Currency movements also matter for a company that reports in Swedish kronor while many costs and revenues involve other currencies. Significant swings can affect reported results even when the underlying business performs steadily.
Political risk remains present as well. Defense budgets ultimately depend on elected governments. A sharp change in the security environment or in domestic priorities could slow the current pace of contract awards. That said, the structural drivers behind higher spending look reasonably durable at present.
How the Market Might Interpret These Results
Equity markets often react more strongly to order surprises than to modest earnings beats. The scale of Saab’s order intake should therefore attract attention from both existing holders and potential new investors. Whether that attention translates into sustained share price strength depends on follow-through in subsequent quarters.
Some investors will focus on valuation relative to the improved outlook. Others will wait for clearer evidence that production is scaling smoothly and that margins are holding or expanding. Both approaches have merit. The key is matching the investment horizon to the multi-year nature of the underlying contracts.
In my own view, the most constructive signal is the combination of strong demand across several product areas rather than reliance on a single large deal. That breadth increases the probability that elevated order levels can be sustained.
The Human and Industrial Side of Rising Orders
Behind the financial figures sit real industrial decisions. Factories need to schedule shifts. Suppliers need visibility to invest in their own capacity. Engineers and technicians need to be hired and trained. Large order books create employment and industrial activity that extends well beyond the prime contractor.
For Sweden, the defense sector has long represented a high-technology industrial capability. Successful export programs reinforce that position. The current wave of contracts supports both national security interests and industrial employment goals at the same time.
I sometimes think investors under-appreciate this dual role. Defense companies deliver products that governments need while simultaneously anchoring skilled manufacturing ecosystems. When both aspects align, political support for the sector tends to strengthen.
Putting It All Together
Saab’s third-quarter report shows a defense company whose commercial pipeline has strengthened significantly. Sales and earnings modestly exceeded expectations. New orders dramatically surpassed them. The Gripen contract for Ukraine provided a major boost, yet other programs contributed as well.
The broader context is a European defense market that is finally converting spending pledges into firm contracts. That process still has further to run. Capacity constraints, political commitments, and the need for modern capability all point toward continued elevated demand for companies that can deliver proven systems.
Of course, execution remains critical. Turning a large order book into profitable, on-time deliveries is the real test. Saab enters that phase with experience and a diversified portfolio. Those attributes should help, though they do not eliminate the challenges ahead.
For anyone tracking the sector, the message from these results is reasonably clear. Demand is materializing. Orders are arriving in size. The companies best positioned to meet that demand stand to benefit over a multi-year horizon. Saab currently sits among them.
Whether this quarter marks the start of a sustained upcycle or simply one strong period will become clearer with time. What already seems evident is that the conversation around European defense has shifted from intentions to actual industrial activity. That shift is now visible in the numbers.
Looking ahead, the next few quarters will reveal how quickly production can respond and whether additional large contracts continue to appear. For now, the third-quarter figures provide a solid data point in what looks like a longer-term story of rising European defense investment.
The numbers themselves are straightforward. The implications stretch further. A company that once operated in a more constrained spending environment is now booking work at a markedly higher rate. That change reflects both specific contract wins and a broader realignment of priorities across the continent.
I will be watching the order intake figures in coming periods with particular interest. Sustained strength would confirm that the current surge is more than a one-off event. Moderation would suggest the Ukraine contract was the primary driver. Either outcome carries useful information for assessing the durability of the current defense spending cycle.
In the meantime, Saab has delivered a set of results that exceed what most observers expected. The combination of solid current performance and a sharply higher order book leaves the company in a stronger position than it occupied a year ago. That is the core takeaway from this quarter’s report.