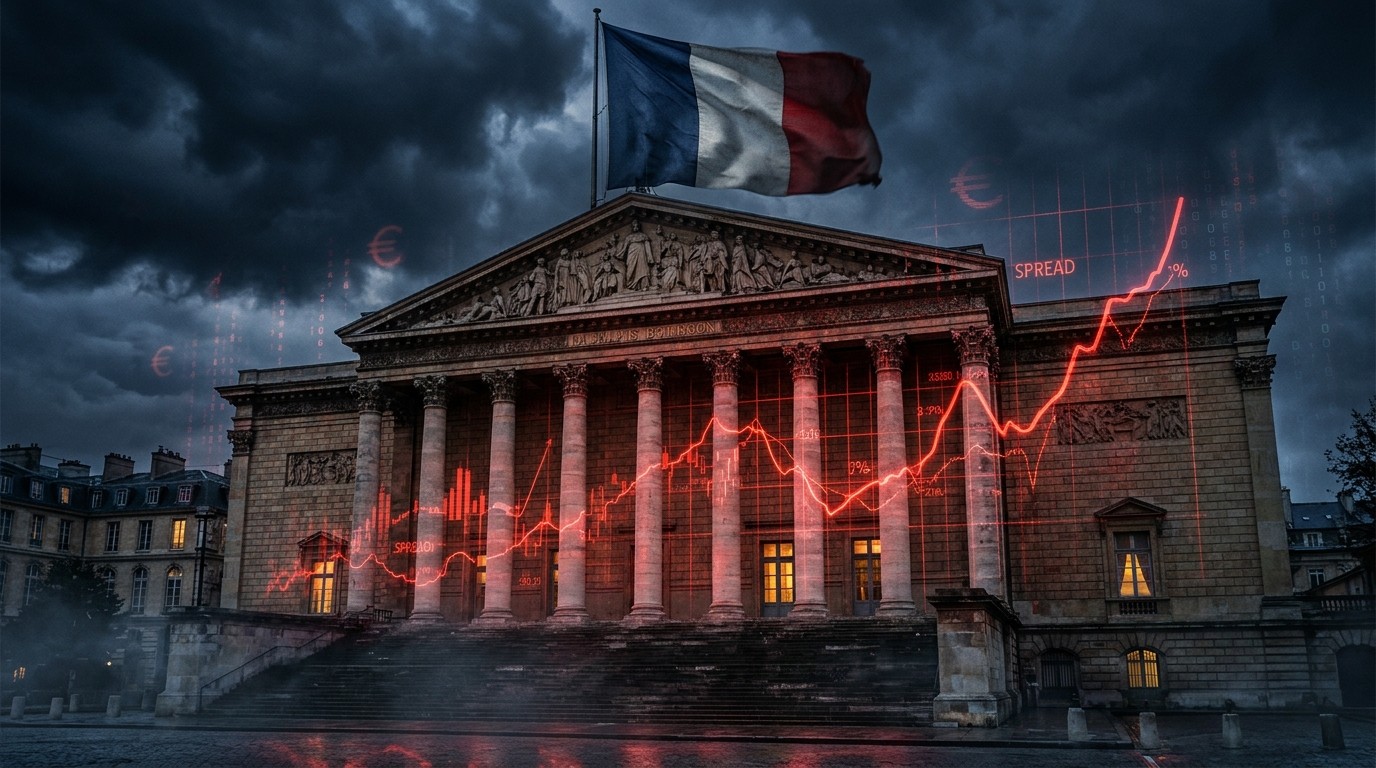

I’ve been watching European bond markets for years, and the recent jump in the gap between French and German 10-year yields still caught me off guard. That spread, known as the OAT-Bund differential, climbed to around 175 basis points this week. Levels like that last appeared during the height of the eurozone sovereign debt troubles more than a decade ago. It feels less like a temporary blip and more like a warning light flashing across the entire single-currency area.
Why France’s Fiscal Path Suddenly Matters So Much
France currently sits at the center of investor attention for a simple reason: its public finances look increasingly difficult to control. The government is trying to push the budget deficit down toward 5 percent of GDP next year from roughly 5.4 percent this year. Yet the lower house of parliament recently stripped out several key savings measures from the 2027 budget plan. Opposition groups show little interest in compromise. With a presidential election approaching, the political incentive to cut spending appears almost non-existent.
In my view, this combination of high spending commitments and limited room for adjustment creates a classic credibility problem. Markets notice when numbers stop adding up. When funding costs rise and growth remains modest, the arithmetic of debt stabilization becomes harsh. Analysts have pointed out that under realistic assumptions of 1 percent real growth, 2 percent inflation, and borrowing costs near 4 percent, France would need a primary surplus close to 1 percent of GDP just to keep the debt ratio stable. If yields stay closer to where they trade today, that requirement edges higher still.
The Moody’s Decision and Market Positioning
Rating agencies have already begun adjusting their views. Two major firms have the French sovereign rating one notch lower than the remaining agency that is scheduled to update its assessment. Market participants largely expect a downgrade, which means the event itself may not trigger a dramatic further widening. Still, the confirmation of weaker credit quality keeps the spotlight firmly on political uncertainty and soft economic fundamentals.
I’ve found that these rating actions often act more as a catalyst for attention than as the primary driver of price moves. Spreads had already widened substantially before the latest review. The 10-year OAT-Bund differential moved roughly 90 basis points wider from the beginning of September. That kind of shift rarely happens without a deeper story underneath.
Deteriorating fiscal indicators are compounded by political constraints that hinder efforts to place public finances on a more sustainable path.
Credit default swap levels now price French sovereign risk closer to low single-A or even high-BBB territory. That gap between official ratings and market-implied risk is never comfortable for policymakers. It raises the cost of new borrowing and can feed on itself if investors demand higher premiums for holding the debt.
Political Reality Versus Fiscal Targets
Recent large-scale protests added another layer of complexity. Demonstrations of the scale seen recently recall earlier periods of social tension. Polling after the events suggested shifting political preferences that could influence the next presidential contest. Growth forecasts already look soft, and additional social disruption does little to improve the picture. Even in a relatively constructive scenario where the 5 percent deficit target survives the legislative process, weaker growth could still leave the actual outcome higher.
Perhaps the most interesting aspect is how little appetite appears to exist for the scale of adjustment that numbers imply. Stabilizing debt ratios would require sustained primary surpluses that France has rarely achieved in recent decades. When funding costs rise, the required surplus grows larger. Society’s willingness to accept the necessary spending restraint remains an open question.
Investors are not only looking at today’s deficit. They are trying to price the path over the next several years and the risks surrounding the presidential election. That longer horizon tends to keep risk premiums elevated even after short-term positioning adjustments have played out.
Market Structure and Investor Behavior
Positioning data suggests that some of the forced selling seen earlier has eased. Yet real-money buyers have remained cautious even as fair-value models indicate that French government bonds look relatively cheap on a spread basis. Value alone has not been enough to generate strong inflows. Lower volatility or a broader duration rally driven by external factors could help, but a genuine improvement in the fundamental outlook would likely prove more decisive.
The near-term calendar contains several potential headwinds rather than clear catalysts for a reversal. Additional protests, economic data releases that may disappoint, and further political events all sit on the horizon. Under these conditions, further widening remains a risk, and the moves can become more pronounced once certain thresholds are crossed.
In my experience, when spreads start behaving this way, the absence of strong buying interest itself becomes part of the story. Portfolio managers often prefer to wait for clearer signals before adding exposure, which can leave markets more sensitive to negative news.
Broader Implications for the Eurozone
France is not a small peripheral economy. Its government bond market ranks among the largest and most liquid in the euro area. Persistent pressure on French yields therefore carries implications that extend well beyond Paris. Higher core spreads can influence financing conditions across the currency union and complicate the task of the central bank.
Some market participants have already begun discussing the possibility of verbal intervention if spreads fail to stabilize. Whether such comments would prove sufficient remains uncertain. The deeper issue is fiscal sustainability and political capacity to deliver credible multi-year adjustment plans.
Energy prices and geopolitical tensions add further layers of uncertainty. None of these factors operate in isolation. When several risk elements move in the same direction, the overall market reaction can intensify.
What Investors Are Watching Closely
Several metrics stand out right now. The absolute level of the OAT-Bund spread remains the most visible gauge of relative stress. Cross-market relationships, such as the comparison between French and Italian yields, also draw attention. France currently trades through Italy on a spread basis, a reversal of the more typical ranking seen in calmer periods.
- Trajectory of the primary deficit over the medium term
- Political capacity to pass meaningful fiscal measures
- Evolution of growth forecasts and associated revenue risks
- Behavior of real-money and leveraged investors around key levels
- Any signals from the central bank regarding financial stability concerns
I’ve noticed that once spreads reach crisis-era territory, the psychological barrier itself can influence behavior. Traders and portfolio managers begin to treat further widening as more probable, which can feed momentum in the short run.
The Challenge of Debt Stabilization
Debt dynamics follow relatively straightforward arithmetic, yet the political translation of that arithmetic is rarely straightforward. When interest rates were extremely low, the burden of high debt ratios felt lighter. As funding costs have normalized, the same stock of debt requires larger primary balances to keep ratios from rising.
France has run primary deficits for extended periods. Moving into sustained surplus territory would represent a meaningful shift in fiscal stance. Whether the current political environment can support that shift is the core question markets are trying to answer.
Some observers argue that the situation remains manageable because France retains strong institutional frameworks and a large domestic investor base. Others counter that the combination of high debt, soft growth, and limited political consensus creates vulnerability if confidence erodes further. Both perspectives contain elements of truth. The balance between them will likely determine how spreads behave in the coming months.
Historical Context Without Overstatement
Comparing current spreads to the peaks of 2011 provides useful perspective, yet the broader environment differs in important ways. The banking system is better capitalized. Policy tools available to the central bank have expanded. Still, the underlying tension between national fiscal policies and shared monetary policy has never fully disappeared.
When a large core country experiences sustained pressure, the transmission channels to the rest of the currency area become more relevant. Asset managers with euro-denominated benchmarks must decide how to allocate risk, and those decisions can amplify moves across related markets.
In my experience, the most persistent pressure tends to emerge when fiscal plans lack political ownership. Technical packages that survive one parliamentary vote but lack broader support often struggle to deliver the intended results over multiple years.
Possible Paths Forward
Several scenarios remain open. One involves a gradual narrowing of spreads if the government manages to reintroduce credible savings measures and growth holds up better than feared. Another sees continued pressure if political fragmentation intensifies and rating agencies move further into lower investment-grade territory. A third, less discussed possibility involves external factors providing temporary relief through lower energy costs or a broader risk-on environment that supports duration assets.
None of these paths is predetermined. Markets will continue to update probabilities as new information arrives. The presidential election cycle will keep the political dimension highly visible for the foreseeable future.
Investors who treat the current episode purely as a short-term trading opportunity may find the risk-reward less attractive than those who incorporate a longer-term view of fiscal sustainability. The difference between the two approaches often shows up in how positions are sized and how much volatility is tolerated.
What the Numbers Actually Show
Looking at the data more carefully, the recent widening has occurred against a backdrop of reduced forced selling in some segments of the market. That observation suggests the move is driven more by fundamental reassessment than by pure positioning dynamics. When models flag relative value yet buying remains limited, it usually means participants are waiting for greater clarity on the policy path.
Borrowing costs just above 5 percent for 10-year paper would raise the primary surplus needed for debt stabilization toward 2 percent of GDP under standard assumptions. Achieving and maintaining such a surplus would require a sustained shift in the fiscal stance that has not been evident in recent years.
The interaction between growth and fiscal outcomes deserves particular attention. Even modest shortfalls in growth relative to official projections can leave deficits higher than targeted. That feedback loop can become self-reinforcing if higher yields further dampen activity.
Investor Sentiment and Risk Appetite
Equity markets and credit spreads have shown some correlation with the moves in French government bonds. When risk assets sell off at the same time that sovereign spreads widen, the overall environment can reinforce caution. Short covering in certain rate products has supported a duration rally in other parts of the curve, yet that support has not fully translated into tighter French spreads.
I’ve found that these cross-asset relationships often provide early clues about the durability of a move. Isolated widening in one market can reverse quickly. Coordinated pressure across equities, credit, and sovereign spreads tends to last longer and require more substantial positive catalysts to reverse.
Portfolio managers appear to be treating the situation as a fundamentals story first and a positioning story second. That hierarchy matters because it changes the type of news that can produce a meaningful shift in direction.
Looking Ahead Without False Certainty
Predicting the exact path of spreads is a difficult exercise. What can be said with more confidence is that attention will remain elevated as long as the fiscal trajectory and political outlook stay uncertain. Rating actions may confirm existing market views rather than create entirely new ones, yet they still influence the conversation among official-sector investors and risk managers.
The coming months will test whether France can generate a credible multi-year plan that markets find believable. Technical adjustments that survive a single vote but lack broader political buy-in rarely deliver lasting confidence. Structural improvements that address both spending and revenue dynamics would carry more weight, yet such packages are harder to assemble in fragmented political environments.
For now, the OAT-Bund spread sits near levels that once signaled serious stress across the currency union. Whether that comparison proves overstated or understated will depend on the ability of policymakers to close the gap between fiscal targets and political reality. Markets will keep testing that ability with every new piece of data and every political development.
In the end, sovereign spreads are a continuous referendum on credibility. France currently faces a more searching version of that referendum than it has in many years. How the country responds will shape not only its own borrowing costs but also the broader risk environment in European fixed income for some time to come.
The story is still unfolding. Investors who stay focused on the underlying arithmetic of debt, growth, and political capacity will be better positioned to interpret the next set of moves, whatever direction they take.