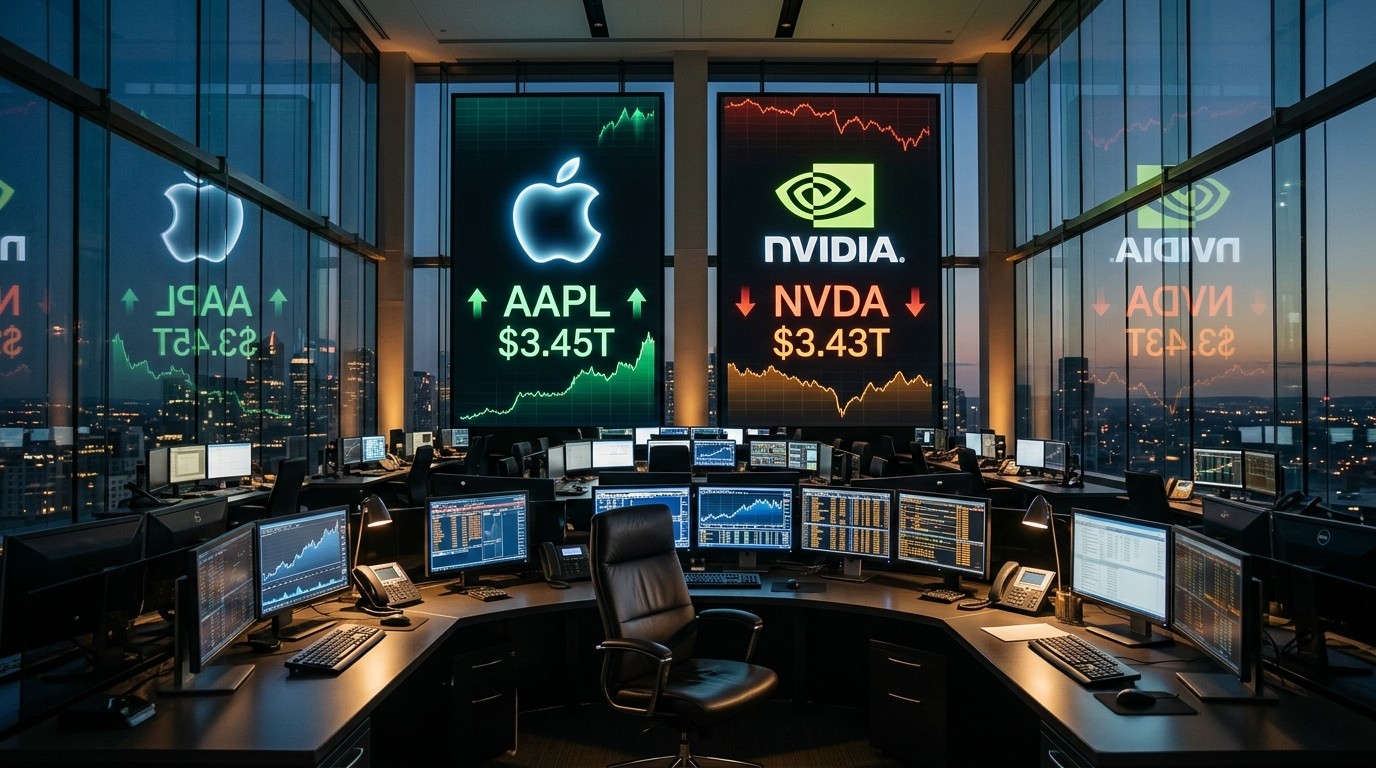

Have you noticed how quickly the top of the market can change hands these days? One week the conversation centers on artificial intelligence hardware, the next it swings back toward the company that has quietly refined consumer devices for years. Right now Apple trades at roughly $5.05 trillion while Nvidia sits at about $5.10 trillion. That narrow gap feels almost personal after months of AI-driven momentum. I’ve been watching these two names trade places in the ranking more than once this year, and the latest shift has me thinking the story is far from finished.
Apple Prepares To Challenge Nvidia For The Top Spot
Apple shares climbed about four percent in October while Nvidia slipped roughly seven percent over the same stretch. Those opposing moves closed the market-cap distance to a level that felt almost impossible just a few months earlier. The company briefly overtook Nvidia in July only to fall back, yet the current setup looks more durable. Strong pre-order demand for the new iPhone Duo and an earnings report scheduled for early November are giving investors fresh reasons to reassess the stock.
What stands out to me is the change in tone. For a long stretch Apple was treated as the steady, almost defensive name among the largest technology companies. Nvidia and other AI-focused names grabbed the spotlight. Now the market seems to be rediscovering the strength of a business that still generates enormous cash from hardware while expanding high-margin services. That combination has always been powerful; the difference this time is the renewed excitement around a premium device launch.
Why The Market Cap Race Suddenly Feels Competitive Again
Market capitalization is a simple number, yet it carries heavy psychological weight. When one company sits clearly above the rest, capital tends to flow toward it by default. When two giants trade within a few percentage points of each other, every product cycle and earnings release becomes a potential tipping point. Apple’s current valuation of $5.05 trillion against Nvidia’s $5.10 trillion creates exactly that tension.
I’ve found that these close contests often last longer than people expect. Investors rotate capital based on short-term narratives, but the underlying businesses keep compounding at different speeds. Apple’s hardware cycle is clearly turning upward at the high end of the price range, while questions about the pace of AI infrastructure spending have introduced some caution around Nvidia. Neither story is finished. Both companies remain exceptional, yet the near-term catalyst calendar favors Apple.
The iPhone Duo Launch And What It Signals
The new iPhone Duo reached stores this week after pre-orders opened on October 16. Demand was immediate. Some configurations sold out within hours, and delivery estimates for certain models stretched into January. That kind of early momentum is rare even for Apple. The device starts at $1,999 and climbs past $3,000 for the highest storage versions. This is a deliberate step away from the recent emphasis on lower-priced models in certain international markets.
Production targets have reportedly been raised. When a company increases manufacturing volume after seeing initial orders, it usually means the internal data looks stronger than the original plan. I’ve watched previous product cycles where early sell-outs faded after the first month. This time the combination of higher starting price and extended delivery windows suggests the enthusiasm is real. Hardware revenue has lagged services growth for several years. A successful premium launch could reverse that trend, at least for a few quarters.
Perhaps the most interesting aspect is the message the price point sends. Apple is leaning into the upper end of the market rather than chasing volume at every price tier. That strategy can support both revenue and margins if the product delivers the experience customers expect. Early signals point in that direction, though the true test will come when the company reports actual unit sales and average selling prices in a few weeks.
Earnings On November 2 Could Tip The Balance
Apple is scheduled to report results on November 2. Consensus expectations hover around $113 billion in revenue, consistent with earlier guidance of nine to eleven percent year-over-year growth. The headline number will matter, yet the qualitative commentary may matter more. Management’s tone on iPhone demand, channel inventory, and services momentum often moves the stock more than the pure financials.
Services remain the quiet powerhouse. In the most recent full fiscal year the segment generated roughly $109 billion. That represents only about a quarter of total revenue, yet gross margins near 75 percent mean services contribute more than 40 percent of overall gross profit. Hardware margins sit closer to 37 percent. The mix explains why even modest services growth can lift the entire profitability profile.
The durability of the services business often gets overlooked when hardware launches dominate the conversation.
I’ll be listening carefully for any updates on subscription trends, advertising within the ecosystem, and the health of the installed base. Those metrics tend to be stickier than quarterly hardware shipments. If management sounds confident on both the new phone and the recurring revenue stream, the market could easily push Apple’s valuation past Nvidia’s in short order.
Hardware Recovery Meets High-Margin Services
For several years the narrative around Apple focused on services growth offsetting slower hardware expansion. That story worked well, yet it left some investors wondering whether the company could still surprise on the product side. The early response to the iPhone Duo suggests the answer may be yes. A return of hardware strength at the premium end would complement the already strong services engine rather than replace it.
In my experience the most resilient technology companies manage to grow both layers at once. Apple has done that before. The current setup looks familiar: a new device generating headlines and store traffic while the services business continues its steady climb. The difference this time is the absolute scale. Both the hardware and services bases are larger than they were in previous cycles, so incremental gains translate into larger absolute dollar amounts.
Gross margin expansion is another piece of the puzzle. Services already operate at a much higher margin than hardware. Any shift in mix toward services, or any improvement in hardware margins from a richer product mix, flows quickly to the bottom line. Investors have rewarded that dynamic for years. A quarter or two of better-than-expected hardware results on top of solid services growth could accelerate the market-cap catch-up.
How Investor Sentiment Has Shifted This Month
October has been kind to Apple and less kind to Nvidia. The four percent gain versus the seven percent decline closed most of the remaining valuation gap. Broader technology stocks have faced pressure from questions about the financing environment for large AI projects. Those concerns have weighed more heavily on companies whose growth is tightly linked to accelerated capital spending.
Apple’s relative resilience makes sense when you consider the customer base. Consumer hardware and services demand tends to move with employment and wage trends more than with data-center budgets. That does not make Apple immune to macroeconomic slowdowns, yet it does create a different set of sensitivities. Right now the market appears to be rotating toward businesses with clearer near-term product catalysts and less exposure to the AI infrastructure debate.
I’ve noticed that rotations of this kind often start quietly. A few percentage points of outperformance accumulate, the market-cap ranking starts to look contested again, and suddenly the narrative flips. We may be in the early stages of that process. Whether it lasts depends on the earnings report and the subsequent holiday selling season. Still, the setup is more competitive than it has been for months.
What Reclaiming The Market Cap Lead Would Mean
If Apple moves back into the top position, the symbolism would be significant. For a long stretch the company set the tone for the broader technology sector. Its product launches, capital returns, and margin expansion became reference points for other large-cap names. Losing the market-cap crown did not change the underlying business, yet it did change the conversation. Reclaiming the title would likely shift attention back toward the consumer hardware and services model.
That does not mean Nvidia’s long-term story has weakened. The demand for accelerated computing remains substantial. The current market-cap proximity simply reflects different short-term catalysts and different investor concerns. Both companies can succeed. The ranking at any given moment is a snapshot, not a final judgment.
From a portfolio perspective the closeness of the two valuations creates an interesting dynamic. Relative performance can swing on small changes in narrative or on a single strong or weak earnings print. Active managers who hold both names may adjust weightings more frequently than usual. Passive flows into market-cap weighted indexes will also respond automatically as the ranking changes.
Key Numbers Worth Tracking Over The Next Few Weeks
Several data points will shape the next chapter of this race. The most obvious is the November 2 earnings release. Beyond the top-line revenue figure, watch for commentary on iPhone sell-through, average selling prices, and channel inventory levels. Any upward revision to production plans or any indication of stronger-than-expected demand in key markets would support the positive hardware narrative.
Services growth rates and margins remain equally important. Even if hardware surprises to the upside, a soft services number could temper enthusiasm. Conversely, solid services results combined with healthy hardware trends would reinforce the balanced growth story. Gross margin guidance for the current quarter will also draw attention, given the potential mix shift toward higher-priced devices and the continued services contribution.
- iPhone unit trends and average selling price commentary
- Services revenue growth and margin outlook
- Overall gross margin trajectory
- Management tone on demand sustainability into the holiday period
- Any updates on production capacity or component availability
Those five items form a practical checklist. None of them exists in isolation. The market will weigh them together against the current valuation and against Nvidia’s own upcoming catalysts. The process will be noisy, yet the direction of the market-cap race will become clearer once the numbers are public.
Looking Beyond The Immediate Ranking
Market capitalization rankings make for clean headlines, yet they capture only one dimension of value creation. Apple continues to generate substantial free cash flow, return capital to shareholders, and expand its ecosystem. Nvidia continues to sit at the center of a multi-year computing transition. Both businesses possess durable competitive advantages. The current contest simply highlights how quickly relative valuations can shift when product cycles and investor narratives align differently.
In my view the more useful question is not which company sits higher on any given day, but how each is positioned for the next several years. Apple’s combination of premium hardware and high-margin recurring revenue has proven resilient across multiple economic environments. The early success of the iPhone Duo suggests the hardware side of that equation is regaining momentum. Services already provide a strong foundation. Together they create a business that can compound at attractive rates even if the broader technology sector experiences periods of volatility.
Nvidia’s opportunity set remains enormous as well. The scale of investment in accelerated computing is still in its early stages by historical standards. Temporary questions about financing or near-term spending pace do not erase the longer-term demand curve. The two companies are solving different problems for different customers. Their market-cap proximity is interesting, but it should not obscure the distinct strengths each brings to the market.
Practical Considerations For Investors Watching The Race
Close market-cap contests often tempt investors to make binary decisions. History suggests a more measured approach works better. Both stocks have delivered exceptional returns over multi-year periods. Attempting to time the exact moment one overtakes the other can introduce unnecessary transaction costs and emotional pressure. A clearer framework focuses on the underlying business trends rather than the daily ranking.
For those who already hold Apple, the current environment offers a chance to reassess position size against the improving hardware narrative and the still-strong services profile. For those who hold Nvidia, the recent relative underperformance may present an opportunity to evaluate whether the longer-term growth drivers remain intact. Diversification across both names has historically reduced the impact of short-term narrative shifts.
I’ve found that the most consistent results come from focusing on cash flow generation, competitive position, and capital allocation rather than on temporary valuation rankings. Apple scores well on all three. The upcoming earnings report will provide updated evidence on the first of those factors. The product cycle underway will speak to the second. The company’s long record of returning capital addresses the third.
The Broader Technology Backdrop
The current Apple-Nvidia dynamic sits inside a larger technology market that has experienced sharp rotations this year. AI enthusiasm drove substantial gains in a relatively narrow group of names. More recently, questions about the sustainability of that spending and about the broader financing environment have introduced caution. In that setting, companies with clearer near-term product catalysts and less dependence on large capital-expenditure cycles have found relative support.
Apple fits that description. Its customer base is broad, its product cycle is visible, and its services business provides recurring revenue that is less cyclical than pure hardware. Those characteristics do not guarantee outperformance in every market environment, yet they help explain the relative strength seen in recent weeks. Whether that strength continues will depend on execution over the next several months.
The rest of the large-cap technology group will also influence the ranking. Relative performance among the biggest names often moves in clusters. A period of strength for consumer-facing technology can lift multiple stocks at once, just as a period of AI-focused enthusiasm can concentrate gains in a smaller set. The current setup favors a broader distribution of leadership, at least in the near term.
Final Thoughts On A Tight Contest
Apple stands within striking distance of reclaiming the title of the world’s most valuable company. The combination of strong early demand for a premium device, an upcoming earnings report, and relative share-price strength has closed most of the gap with Nvidia. That does not guarantee a permanent change in ranking, yet it does create a more competitive environment than investors have seen for some time.
The next few weeks will supply important new information. Earnings commentary, holiday sell-through data, and any further updates on production will shape the hardware narrative. Services trends will continue to provide the underlying stability that has supported the stock through previous cycles. Together those elements will determine whether Apple can convert the current proximity into a clear lead.
Regardless of the short-term ranking, both companies remain formidable. Apple’s ability to generate cash from a massive installed base while innovating at the high end of consumer hardware is rare. Nvidia’s position at the center of accelerated computing is equally distinctive. The market-cap race makes for engaging viewing, yet the longer-term value creation stories are what ultimately matter. For now the score is close, the catalysts are immediate, and the outcome remains open. That combination alone makes the coming weeks worth watching with more than casual interest.
I’ve watched these two giants trade the top position before. Each time the underlying businesses continued to compound regardless of the daily ranking. This episode feels similar. The numbers are large, the gap is small, and the product and earnings calendars are aligned in Apple’s favor for the moment. Whether that alignment proves decisive will become clearer soon enough. Until then the race itself offers a useful reminder of how quickly market leadership can shift when fundamentals and sentiment move together.