

Uae Oil Recovery Record Output Empty Tanks Risk

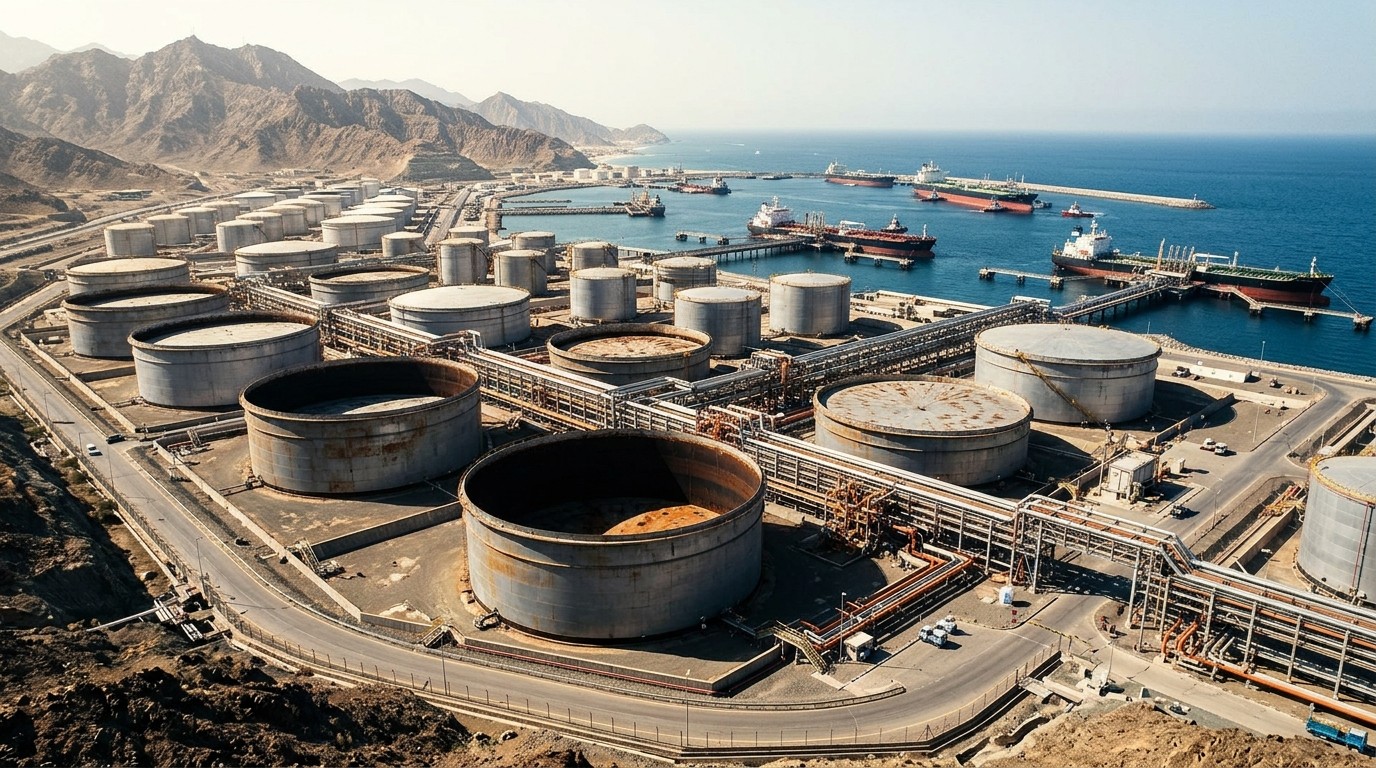
UAE posts record oil output numbers that look impressive on the surface. Dig deeper and the fuel tanks are drained, gas systems still limping. Another disruption could expose just how thin the buffer really is right now.
Financial market analysis from 25/10/2026. Market conditions may have changed since publication.
I remember sitting with a cup of coffee last week, scanning the latest energy flow numbers, and almost spilling it when the headline jumped out. Record oil supply from the Emirates, nearly 5.3 million barrels a day in September. Fujairah pushing out 2.62 million. The big refinery complex back online at full tilt by late August. For a moment it felt like the whole episode had been a bad dream and everything was back to normal. Then the more detailed assessment landed on my desk and the picture changed completely. The crude is flowing again. Almost everything else is not. Gas plants are still running well below capacity. Petrochemical feedstocks are scarce. And the product tanks that once held a comfortable buffer now sit at roughly a third of their pre-conflict levels. That combination is worth a closer look, because it is not the same thing as resilience.
The Surface Numbers Versus the Deeper Picture
On paper the recovery looks sharp. Production that had collapsed to an average around 2.4 million barrels a day through the spring months has climbed back. The exit from quota restrictions removed one artificial ceiling. Some genuine repair work has clearly paid off. Yet the same data that shows the crude surge also shows inventory draws contributing to those export figures. Selling down stocks can post an impressive monthly number. It does not rebuild the underlying system.
What strikes me most is the gap between availability and actual throughput. One major gas operator reported assets 99.9 percent available in the second quarter—better than the prior year—while utilization dropped from 80 percent to 54 percent. The plants were ready. The feedstock, the storage, and the export routes were not. It is a bit like announcing that the car is in perfect mechanical condition while it sits in the driveway missing its wheels. Ready does not equal running.
How Production Collapsed and Then Rebounded
Early in the year output sat near 4 million barrels a day. By March through May the average had fallen roughly 40 percent. That is not a modest dip. It reflects direct hits on key infrastructure and the cascading effects that follow. Refining capacity went offline after a major fire. Gas processing plants that feed both domestic needs and export liquids suffered repeated damage. Even an electrical installation supporting nuclear generation was struck, an incident that underscored how widely the targeting spread.
The rebound has been real for crude. Loadings at the bypass port recovered. The large refining complex declared itself back at full capacity. Those are measurable steps. Yet the same period shows gas production still down more than 30 percent year-on-year in the second quarter, export liquids such as LPG and naphtha down over 50 percent, and the share of LNG even lower. Revenue, EBITDA, and net income at the gas company all contracted sharply. Two point three billion dollars in revenue disappeared in a single quarter at one entity alone. Those are not rounding errors.
The plants were ready, willing and able. They simply could not run because the feedstock, the storage and the export routes had been knocked out.
Repairs move faster than full recoveries. One major gas complex reached about 85 percent of prior supply by early August. A petrochemical facility was fixed by the end of June, then discovered it had little to feed it and settled at roughly 60 percent utilization. An aluminium smelter that went dark in late March had restarted only a quarter of its pots by late August and does not expect to finish the job until sometime in early 2027. The timeline for complete restoration keeps stretching.
Fujairah Stocks Tell a Clearer Story
Here is the figure that should give any energy planner pause. On 19 October Fujairah held 7.25 million barrels of refined products. Before the disruptions the figure sat near 20.7 million. That is a 65 percent drop. Gasoline and naphtha stocks are down 87 percent. Fuel oil is down 53 percent. Diesel and jet fuel are down 23 percent and fell another 18 percent in a single recent week—just as winter demand begins to firm. These are not abstract numbers. Fujairah functions as a major bunkering and product trading hub. Ships refuel there. Traders stage cargoes between Asia and Europe. With roughly a third of normal stocks, the hub has roughly a third of its normal ability to absorb a fresh shock.
Simple arithmetic makes the point. Lose a million barrels a day of export outlets while holding about 10 million barrels of usable storage and you have roughly ten days before fields begin to shut in. Ten days is not a strategic reserve. It is a long weekend. I have watched similar drawdowns in other markets; the moment the buffer shrinks that far, every subsequent disruption becomes more expensive and more likely to cascade.
- Gasoline and naphtha inventories down 87 percent from pre-conflict levels
- Fuel oil stocks reduced by 53 percent
- Diesel and jet fuel down 23 percent, with a further sharp weekly drop
- Overall product holdings at Fujairah reduced by roughly two-thirds
The port itself has absorbed at least 19 attacks since the conflict began. In one mid-March week loadings fell to 440,000 barrels a day. After a strike in early May, refined-product exports essentially stopped for a month; exactly one product tanker departed between then and the start of June. The bypass that was built so the country would never have to worry about the strait turned out to need its own insurance policy.
The Pipeline That Covers Only a Third
The main answer to a closed strait has long been the pipeline running from the gas complex inland to the east-coast port. It is designed for 1.5 million barrels a day and can perhaps stretch to 1.8 million on a strong day. Claimed production capacity sits near 4.85 million barrels a day. The escape hatch therefore fits about a third of the passengers. A second line is planned for 2027. That will be useful for anyone scheduling disruptions in 2028. Until then the capacity mismatch remains structural.
In my experience watching energy infrastructure, these kinds of bottlenecks rarely stay theoretical. When the system is already running with thin product stocks, any further interruption at the port or along the line forces either field shut-ins or expensive rerouting. Both carry costs that show up later in insurance rates, freight, and ultimately consumer prices. The record September numbers partly reflect genuine repairs, partly the removal of quota limits, and partly the drawdown of inventories that were already at record lows. Drawing savings can produce a strong monthly print. It is not a sustainable operating model.
| Infrastructure Element | Pre-Conflict Status | Current Constraint |
| Fujairah product stocks | Approx. 20.7 million barrels | 7.25 million barrels (65% lower) |
| Pipeline capacity | Designed 1.5–1.8 mbd | Covers roughly one-third of claimed output |
| Gas utilization | Around 80 percent | Fell to 54 percent despite high availability |
| Aluminium smelter | Full operation | Partial restart, completion expected early 2027 |
Gas, Feedstock and the Broader System
Crude has returned. Gas has not kept pace. Domestic gas production was down 32.5 percent in the second quarter versus a year earlier. Export liquids fell 54.5 percent. The company’s share of LNG dropped 63 percent. Sales of those export liquids fell from 252 to 117 trillion British thermal units. LNG sales declined about 71 percent. The financial results followed: revenue down 39 percent, EBITDA 47 percent, net income 52 percent. Those percentages describe a system that is still operating well below its design point even after months of repair work.
Petrochemical plants that depend on that gas stream remain constrained. One facility fixed its physical damage, then ran at 60 percent because feedstock was unavailable. Aluminium production, an energy-intensive activity, faces a multi-year path back to full output. These are not peripheral activities. They form part of the broader industrial base that the crude recovery is supposed to support. When feedstock and power are limited, the value-added segments stay subdued even while raw export volumes look strong.
Across the wider region the pattern repeats. Refined-product shipments in September ran at 1.9 million barrels a day against 4.7 million before the disruptions. LPG shipments stood at 670,000 barrels a day versus 1.5 million previously. The recovery is visible for crude tankers. For everything else it remains incomplete. That distinction matters for buyers who need diesel, jet fuel, or chemical feedstocks rather than raw crude.
Inventory Math and the Next Shock
Perhaps the most interesting aspect is how little buffer remains. The 7.25 million barrels at Fujairah represent a sharp contraction from the 20.7 million that once provided a cushion. When product stocks are that low, the ability to cover a sudden loss of supply shrinks dramatically. Analysts who have examined similar situations elsewhere note that the time from disruption to field shut-in can compress from weeks to days once usable storage falls into the single-digit millions of barrels for a major export system.
Is this true resilience or a temporary bounce supported by inventory draws? The data lean toward the latter. Some of the September strength came from genuine repair progress. Some came from the end of quota obligations. And some, according to the same assessments that reported the record supply, came from drawing inventories that were already historically low. That mix can produce impressive headlines. It leaves the system more exposed the next time a disruption occurs.
The country once presented itself as a stable, diversified hub insulated from regional volatility—a place where capital and energy operations could operate with relative calm. Events over the past months have shown that even the bypass port and inland complexes sit within reach of long-range systems. Nineteen attacks on Fujairah alone demonstrate the point. The last time the system absorbed a significant blow it still held roughly 20 million barrels of products as a shock absorber. The next time the figure is closer to seven. Record output paired with empty tanks is not the same as having rebuilt margin. It is a system operating closer to the edge.
What the Partial Recovery Means for Markets
Global markets have adjusted to the crude volumes returning. Differentials and freight rates reflect the partial normalization. Yet the persistent shortfall in products and gas liquids keeps certain segments tighter than the crude headlines suggest. European buyers heading into winter, for example, watch diesel and jet availability closely. Any further interruption that forces additional field shut-ins or product export delays would register more quickly now that the storage cushion is thinner.
Insurance and shipping costs tend to reprice once repeated incidents demonstrate that even bypass infrastructure can be affected. Those costs do not always appear in the spot crude price immediately, but they accumulate in the delivered cost of products. In my view the current configuration—strong crude exports, constrained gas and products, depleted tanks—creates an asymmetric risk. Upside supply surprises are limited by the remaining bottlenecks. Downside surprises can propagate faster because the buffer is smaller.
Nobody can produce a complete public register of every damaged asset and every completed repair. Credit is due for the work that has restored refining capacity and crude loadings. The shape of the remaining problem is nevertheless visible in the utilization rates, the feedstock constraints, the product stock levels, and the pipeline capacity relative to claimed output. Those metrics point to a recovery that is real for one segment and incomplete for others.
Looking ahead, the planned second pipeline will eventually expand the bypass capacity. Until that line is operational the existing mismatch remains. Gas plants continue to climb back toward higher utilization, but the pace depends on feedstock availability and the integrity of associated infrastructure. Product stocks will need deliberate rebuilding if the system is to regain the shock-absorption capacity it once had. In the meantime the combination of record crude numbers and markedly lower product holdings defines the present operating environment.
Energy systems rarely fail in a single dramatic moment. More often they reveal their limits through a series of partial recoveries and persistent constraints. The current data from the Emirates illustrate that pattern. Crude is moving. The rest of the complex is still catching up. For anyone tracking global supply balances, the distinction between headline production and the underlying ability to sustain it through the next disruption is the figure that deserves the closest attention.
I keep coming back to that simple image of the car on blocks. High availability, low utilization. Strong export numbers, thin product tanks. Impressive monthly prints, structural bottlenecks that have not yet been fully resolved. Those contrasts do not cancel the genuine progress that has occurred. They do, however, suggest that the recovery remains uneven and that the margin for further error is narrower than the top-line figures imply. Markets will continue to price the crude that is actually flowing. They will also, over time, have to price the constraints that still limit everything else.
Regional Product Flows and Winter Demand
September data showed refined-product shipments running well below prior levels across the broader area. The gap between 1.9 million barrels a day and the earlier 4.7 million is substantial. LPG flows similarly remain compressed. These shortfalls matter because product markets are less flexible than crude markets in the short term. Refineries need specific crude qualities and continuous feedstock. Storage is more specialized. When the regional product system is already operating with lower inventories, incremental demand from winter heating or aviation recovery can tighten balances faster than crude-only observers expect.
European energy ministers watching diesel and jet availability have reason to monitor these flows closely. The last time the system faced a major interruption it still possessed a larger product cushion at the main trading hub. That cushion has contracted. Any additional loss of refining or export capacity would therefore transmit more directly into delivered prices. Freight and insurance premia already embed some of that risk; further incidents would likely reprice them again.
At the same time, the aluminium and petrochemical segments illustrate how energy disruptions ripple into industrial output. Partial restarts are better than full outages, yet they still leave capacity idle. Those idle units represent both lost production and delayed recovery in the broader economy. The timeline stretching into 2027 for full aluminium restoration is a reminder that some assets recover more slowly than others even after physical repairs are complete.
Capacity, Quotas and the Inventory Contribution
The decision to exit quota arrangements removed one constraint on output. That policy shift helps explain part of the climb back toward higher volumes. It does not, however, create new physical capacity or restore damaged processing units. The claimed production capacity figure of roughly 4.85 million barrels a day remains aspirational relative to the current bypass pipeline and the still-constrained gas system. Until additional export routes are in place, the practical ceiling is lower than the nameplate number.
Inventory drawdowns add another layer. When stocks are already at multi-year lows, further withdrawals can support export statistics for a period. They simultaneously reduce the system’s ability to ride out the next interruption. Analysts tracking these balances note that the combination of lower product holdings and limited bypass capacity shortens the window between a disruption and the need to curtail upstream production. That window, once measured in weeks, can compress into days under the present stock levels.
From a market perspective the distinction is useful. Crude supply that is supported by inventory draws is real in the moment it is loaded. It is less durable if the underlying production and export infrastructure cannot sustain the same rate without continued stock depletion. Buyers and traders therefore watch both the headline volumes and the stock reports. When the two diverge, the more conservative reading tends to prevail over longer horizons.
Lessons from the Availability-Utilization Gap
The 99.9 percent availability figure paired with 54 percent utilization is one of the more revealing data points in the entire assessment. It shows that physical repair work can restore the mechanical readiness of plants relatively quickly. It also shows that readiness alone does not restore throughput when the surrounding system—feedstock supply, storage, and export logistics—remains impaired. Operators can report high availability while still operating well below design rates. The financial results follow the utilization number, not the availability number.
Similar patterns appear in other energy systems after major incidents. The visible assets come back online. The less visible constraints—pipeline integrity, associated gas processing, product tank integrity, and insurance availability—take longer. Until those secondary elements are restored, the headline capacity figures overstate the sustainable output. In the present case the gap is large enough to be material for both domestic supply and export balances.
I have found that these gaps tend to close gradually rather than all at once. Each incremental improvement in feedstock or storage adds a bit more throughput. The process is measurable in utilization rates and in the gradual rebuilding of product stocks. Until those metrics move closer to prior levels, the recovery remains partial even if crude export numbers look strong.
Looking at the Next Twelve to Eighteen Months
The second pipeline scheduled for 2027 will eventually relieve one bottleneck. Between now and then the existing line remains the primary bypass. Gas plants will continue their climb, but the rate depends on uninterrupted feedstock and on the absence of further incidents. Product stocks can be rebuilt only if export and refining operations run consistently above the rate of local and bunkering demand. Any interruption resets that rebuilding process.
For global balances the implication is straightforward. Crude supply from the region is higher than it was in the spring, yet it remains more fragile than the pre-conflict configuration. Product and gas-liquid supplies are still constrained. The storage buffer that once absorbed shocks is smaller. Those three facts together define a system that can post strong monthly numbers while still operating with reduced margin for error.
Markets will price the barrels that actually move. They will also, over successive quarters, price the probability that the next disruption finds a thinner cushion and a still-incomplete gas and product system. The record output is real. The empty tanks are equally real. Both belong in any assessment of how durable the present recovery actually is.
In the end the data point to an uneven restoration. Crude loadings have recovered impressively. Gas throughput, petrochemical feedstock, aluminium output, and especially product inventories have not. The pipeline that was meant to guarantee continuity still covers only a fraction of claimed capacity. And the tanks that once provided a multi-week buffer now provide something closer to a long weekend. Those are the metrics that will determine whether the next headline is another record or another sharp contraction. For anyone following energy markets, they are the figures worth watching most closely in the months ahead.
Money is like manure. If you spread it around, it does a lot of good, but if you pile it up in one place, it stinks like hell.

Western Governments Risk Collapse From Policy Failures
Kids Vaccinated Under Anesthesia At Colorado Hospital Raises Flags
Related Articles
Asia Markets Outlook: Fed Comments Impact
Asia-Pacific markets brace for impact as Fed comments hint at rate cut delays. How will tariffs shake things up? Click to find out!
Self-Care vs. Escapism: How to Tell the Difference
Are you practicing self-care or just escaping reality? Uncover the key differences and learn how to recharge without dodging life’s challenges. Read more to find out how...
Stock Futures Surge As Trump Delays EU Tariffs
Stock futures spike as Trump delays EU tariffs, but is the market's relief premature? Uncover the forces driving this rally and what’s next for investors.