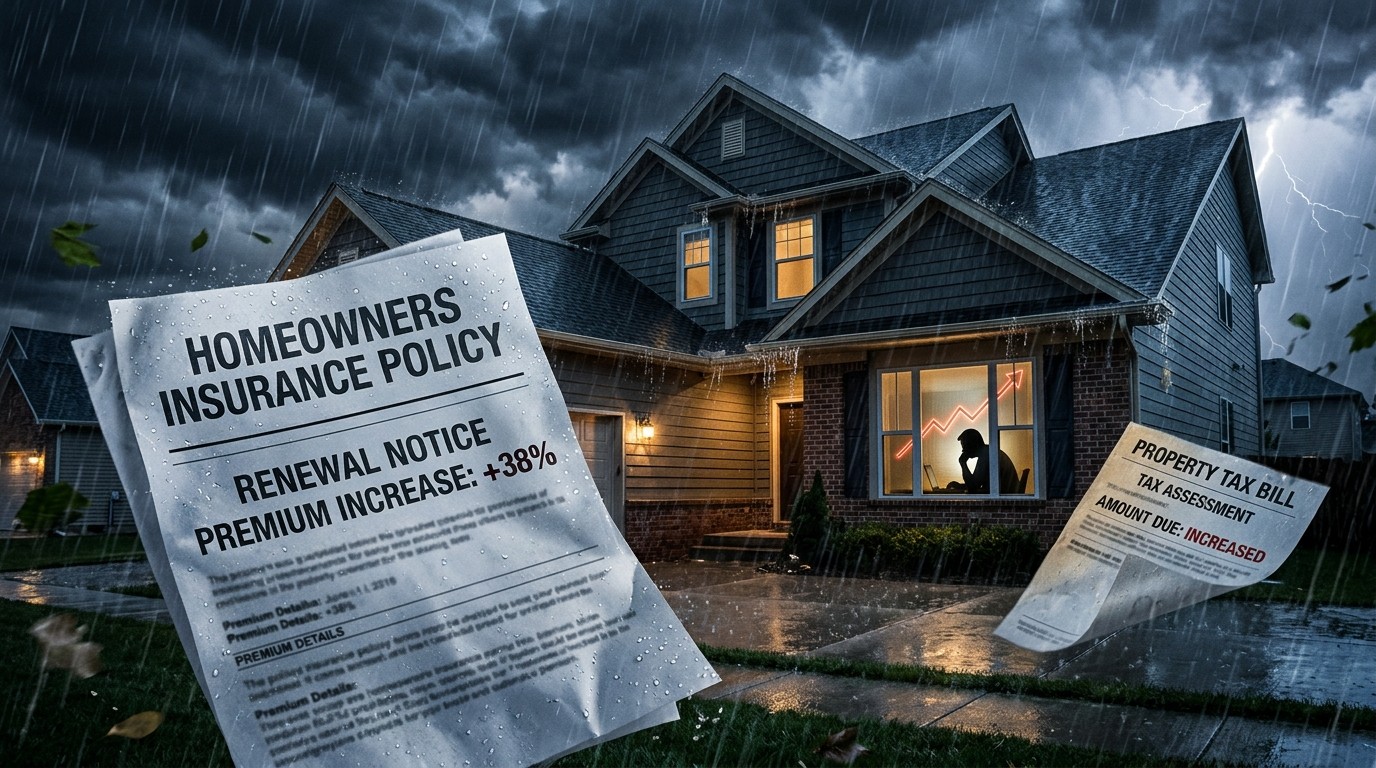

Have you checked your latest home insurance renewal notice yet? For a growing number of American homeowners, that single piece of mail now carries more weight than the annual property tax bill. I still remember the first time I heard someone say their insurance premium had jumped past their taxes. It sounded almost unbelievable. Yet the numbers keep confirming it. Across roughly three-quarters of U.S. counties, the combined cost of homeowners insurance plus the weather-related portion of auto insurance now exceeds what people pay in property taxes.
A Quiet Shift That Caught Many Off Guard
For decades, property taxes stood as one of the largest fixed costs of owning a home. People budgeted for them, complained about them, and sometimes moved to escape them. Insurance was just another necessary expense, usually smaller and more predictable. That relationship has flipped in most places. County-average homeowners insurance premiums have climbed about 45 percent over the past decade after adjusting for inflation. In Nebraska the jump reached a striking 79 percent. Those are not small adjustments. They change household math in real ways.
When you look only at homeowners insurance, premiums already outpace property taxes in about two-thirds of counties. Add the slice of auto insurance tied to extreme weather and the figure rises to 75 percent. On average, homeowners now spend 14 percent more on property insurance than on property taxes. Factor in weather-related auto costs and the insurance burden sits roughly 30 percent higher. These are national averages. The picture grows even more dramatic once you zoom into specific regions.
Why the Southeast Feels the Pinch Hardest
The Southeast carries a unique combination of relatively modest property taxes and high exposure to hurricanes and severe storms. In many of those counties, insurance premiums run two-and-a-half to four times the typical tax bill. Families who once considered property taxes their biggest annual housing cost now face insurance invoices that dwarf them. I have spoken with people who refinanced or adjusted other spending just to keep coverage in place. The pressure is real and immediate.
Meanwhile, the Northeast, the West, and large metro areas often carry higher property tax burdens. Rising insurance costs still hurt, yet they represent a smaller share of the overall housing expense. That difference in relative impact creates uneven stress across the country. Two households with similar home values can experience completely different levels of financial strain depending on where they live.
Midwest and Mountain West Face Their Own Storms
Colorado, Utah, and Minnesota stand out in the Midwest and Mountain West. Hailstorms and severe winter weather have driven claim volumes higher, pushing premiums upward. These states do not always make national headlines for natural disasters the way coastal areas do, yet the cumulative effect on insurance pricing is hard to ignore. Homeowners there are learning that “moderate” weather risk can still translate into significant cost increases over time.
The pattern is clear. Wherever extreme weather produces frequent or expensive claims, insurers adjust pricing. That adjustment lands on policyholders. Over a decade those adjustments compound. What began as a manageable expense can become the largest single housing cost outside the mortgage itself.
The Broader Hidden Costs of Owning a Home
Insurance is only one piece of a larger puzzle. A recent look at typical hidden ownership costs put the national figure at about $16,566 this year. That number has risen more than 31 percent over the past five years. Insurance premiums accounted for the steepest climb among the various categories tracked. Maintenance, repairs, and other ongoing expenses also moved higher, but insurance led the pack.
These hidden costs rarely appear in the glossy purchase calculations people run when they first buy. Mortgage payments, property taxes, and maybe a rough estimate for insurance get most of the attention. The reality of year-to-year premium increases and the growing share of weather-related claims often arrives later, after the papers are signed.
You cannot necessarily stop Mother Nature.
That simple observation captures the core challenge. Weather patterns influence claim frequency and severity. Insurers respond with higher rates, stricter underwriting, or both. Homeowners who want adequate coverage must adapt. Some raise deductibles. Others invest in mitigation measures such as reinforced roofs or impact-resistant windows. Many simply pay more and adjust the rest of their budget.
A Changing Federal Approach to Disaster Costs
Another layer of pressure comes from shifts in how disaster recovery is funded. For roughly two decades the federal government covered about 90 percent of major disaster recovery costs. That split is moving closer to 50-50. Local governments and taxpayers will shoulder a larger share going forward. Analysts describe the change as daunting for local budgets. Municipalities and counties rarely maintain large reserves dedicated to sudden large-scale recovery. When the federal share shrinks, the remaining costs flow somewhere—often into higher local taxes, fees, or reduced services.
Homeowners already paying elevated insurance premiums may eventually feel secondary effects through local tax adjustments or infrastructure decisions. The full impact will take years to unfold, yet the direction of the policy change is clear. More financial responsibility is landing closer to home.
What the Numbers Look Like Across Regions
Regional differences matter a great deal. In high-tax metro areas, insurance growth still registers as painful but remains secondary to the property tax bill. In lower-tax coastal or storm-prone counties, insurance has become the dominant annual cost. That reversal changes how people evaluate locations, housing choices, and even long-term retirement plans.
| Region | Typical Insurance vs Tax Relationship | Primary Drivers |
| Southeast | Insurance 2.5–4 times taxes | Hurricanes, high exposure |
| Northeast & West metros | Taxes still higher | Elevated property values and tax rates |
| Midwest & Mountain West | Insurance pressure rising fast | Hail, severe winter weather |
| National average | Insurance 14% above taxes | Broad premium growth |
The table above simplifies a complex picture, yet it highlights the geographic variation that makes national averages only a starting point. Individual counties within the same state can diverge sharply based on local risk profiles and tax structures.
Practical Steps Homeowners Are Taking
People are responding in different ways. Some shop the market more aggressively at renewal time. Others raise deductibles to bring premiums down, accepting greater out-of-pocket exposure in exchange for lower annual costs. A growing number invest in home hardening—roof upgrades, better drainage, reinforced openings—hoping for credits or simply fewer claims. A few explore alternative coverage structures or higher self-insurance where state rules allow it.
- Review coverage limits and deductibles carefully at each renewal
- Document home improvements that may qualify for premium credits
- Compare multiple carriers rather than accepting the first renewal offer
- Budget for potential future increases rather than assuming stability
- Consider the total cost of ownership when evaluating a new purchase
None of these steps eliminates the underlying trend. They simply give households more control over how the rising costs land on their personal balance sheets. In my view, the most effective approach combines careful shopping with realistic long-term planning. Treating insurance as a fixed, predictable line item no longer matches the data.
The Human Side of Rising Premiums
Behind every percentage increase sits a household making trade-offs. Some delay other home projects. Others adjust vacation plans or contribution rates to retirement accounts. A few question whether their current location still makes financial sense. These decisions rarely make headlines, yet they shape daily life for millions of families.
Younger buyers entering the market face a steeper total cost curve than previous generations. Older owners who paid off their mortgages years ago may still confront insurance bills that rival or exceed former tax obligations. The pressure crosses age groups and income levels, though it lands hardest on those with less flexibility in their budgets.
Looking Ahead: What Might Change
Several forces will influence the path forward. Climate patterns and claim trends will continue shaping insurer pricing models. Regulatory decisions at the state level can either ease or intensify pressure. The evolving federal role in disaster recovery will affect local finances and, indirectly, homeowners. Technological advances in risk modeling and mitigation may eventually help, yet those benefits tend to arrive slowly.
For now, the data points in one clear direction. Insurance costs have grown faster than many other housing expenses and now exceed property taxes across most of the country. Homeowners who treat this shift as temporary may find themselves repeatedly surprised. Those who incorporate higher and more variable insurance costs into their long-term planning will navigate the environment with fewer shocks.
I have watched housing costs evolve for years, and this particular crossover feels significant. Property taxes remain important, of course. Yet the insurance side of the ledger has claimed a larger and more unpredictable share of the ownership burden. Understanding that reality is the first step toward managing it.
Building a More Resilient Ownership Strategy
Resilience starts with information. Knowing how your premiums compare with local tax bills, understanding the drivers behind recent increases, and tracking the broader national pattern all help. From there, practical actions follow. Regular policy reviews, targeted home improvements, and realistic emergency funds become more valuable when insurance volatility rises.
Some households will decide the numbers no longer work in their current location and will explore moves to lower-risk or lower-cost areas. Others will stay and adapt. Both responses are rational. The key is making the choice deliberately rather than discovering the cost pressure only after it becomes acute.
The conversation around housing affordability has long centered on purchase prices, interest rates, and property taxes. Insurance now deserves a more prominent place in that discussion. When premiums routinely exceed taxes in three-quarters of counties, the traditional framing of ownership costs needs updating.
Perhaps the most interesting aspect is how quietly this shift occurred. Many owners noticed individual premium increases but did not realize how widespread the pattern had become until the comparative data appeared. That lag between personal experience and broader awareness is common with gradual financial changes. Once the numbers are clear, the adjustment process can begin in earnest.
Final Thoughts on Managing the New Reality
Owning a home has always involved ongoing costs beyond the mortgage. The balance among those costs is changing. Insurance has moved from supporting player to lead expense in much of the country. Weather-related risks, evolving recovery funding, and cumulative premium growth all contribute. Homeowners who recognize the shift early and plan accordingly will handle the transition more smoothly than those who treat each renewal notice as an isolated event.
The situation is not uniform. Geography still matters enormously. Yet the overall direction is consistent enough to warrant attention from anyone who owns or plans to own residential property. Reviewing your own numbers against the national and regional patterns is a useful starting point. From there, the specific steps will vary by household, location, and risk tolerance.
In the end, the goal remains the same: maintaining adequate protection without allowing any single cost category to dominate the budget. Achieving that balance requires more active management than it did a decade ago. The data makes that clear. The practical response is up to each homeowner.
As insurance continues to claim a larger share of ownership expenses, the households that stay informed and flexible will navigate the next chapter of homeownership with greater confidence. The numbers have already spoken. Now the planning begins.