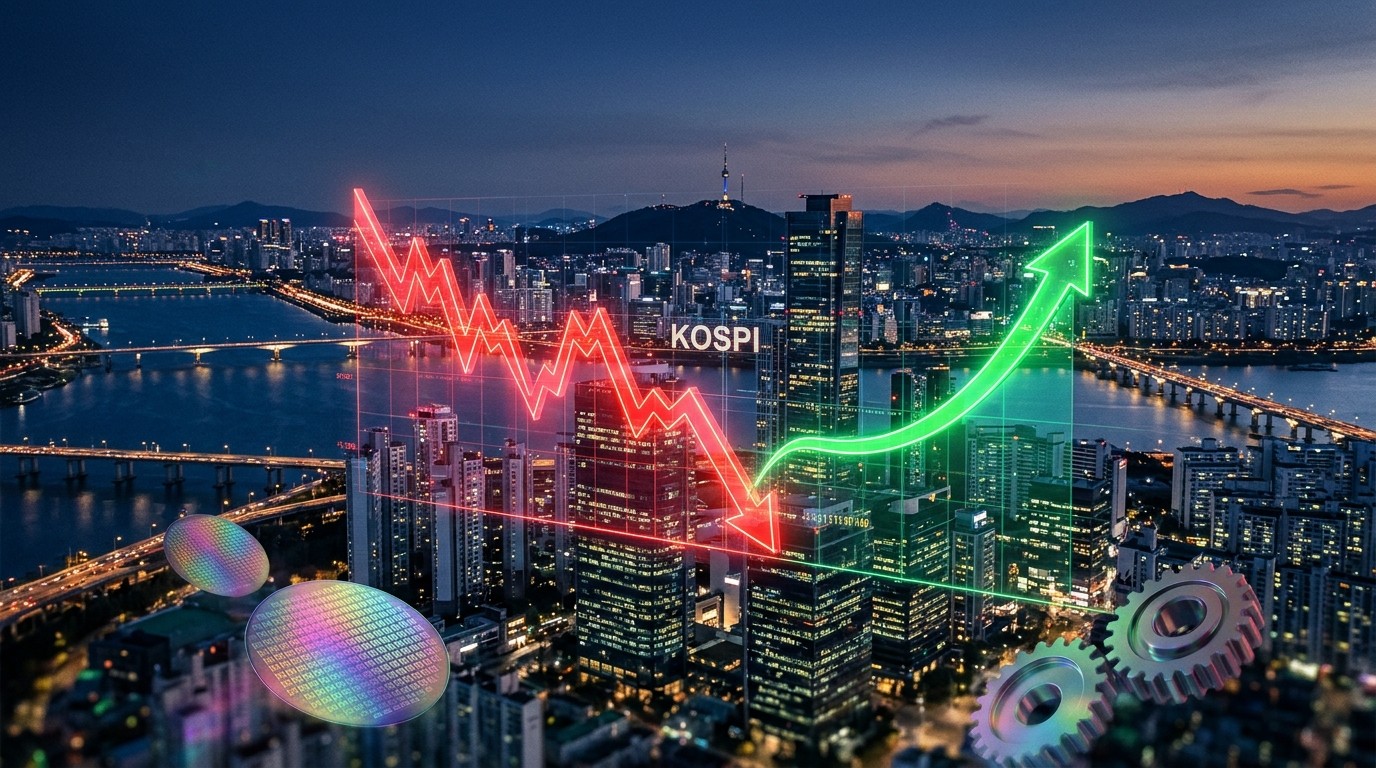

Something about watching a major index get cut so aggressively still hits differently when the same analysts turn around and insist the upside remains huge. That is exactly where South Korea’s Kospi finds itself right now. The 12-month target just dropped from 12,000 all the way to 9,000, yet the revised number still points to more than 60 percent potential gains from current levels. I keep coming back to that gap because it feels almost contradictory at first glance.
Why the Sharp Cut Still Leaves Room for Optimism
Market volatility has clearly intensified and earnings momentum is slowing. Those two factors alone explain a lot of the target reduction. At the same time the index has already fallen roughly 40 percent from its recent highs. Price-to-earnings ratios sit near four times, about three standard deviations below the long-term average. Numbers that extreme rarely stay that way forever.
I have watched similar dislocations before. When valuations compress this far, patient capital often starts to notice. Korean equities look overly discounted relative to the underlying businesses, even after accounting for the current noise. That is the core of the argument being made.
The Memory Chip Concern and Broader Valuation Picture
One area drawing particular attention is the memory chip sector. Current valuations appear to price in something close to a 65 percent decline in 2027 earnings. That level of pessimism feels aggressive. Sustainability of the recent earnings run has become the central question for many investors, especially after the broader sell-off in Asian technology names.
Yet memory does not represent the entire market. Roughly half the index consists of non-memory stocks, and those names still look more than 30 percent undervalued on the same framework. That split matters. It creates space for selective exposure rather than a simple all-or-nothing bet on semiconductors.
Korean equities appear overly discounted relative to their underlying fundamentals, despite heightened market volatility and slowing earnings momentum.
That statement captures the tension well. Fundamentals have not disappeared. Sentiment has simply moved faster than the numbers in many cases.
Sectors Standing Out Beyond the Chip Narrative
Looking past pure memory exposure opens several interesting doors. Power-related names, broader industrials, companies expected to benefit from ongoing corporate governance reforms, and those tied to reflation themes all receive favorable mention. K-culture related businesses and certain risk-reversal approaches also appear on the preferred list.
These areas feel less crowded than the mega-cap technology names that have dominated headlines. In my view that relative quiet can be an advantage. When everyone focuses on the same few stories, opportunities tend to hide in the less-discussed corners of the market.
- Power and energy infrastructure names tied to long-term demand growth
- Industrial companies positioned for any recovery in capital spending
- Firms likely to gain from improved governance standards and shareholder returns
- Businesses sensitive to domestic reflation and consumer recovery
- Select K-culture and content plays with structural tailwinds
None of these ideas exist in isolation. They sit inside a market that has already absorbed a meaningful correction. That context changes the risk-reward calculation.
Foreign Flows and the Broader Asian Sell-Off
Foreign investors, especially hedge funds, have continued to reduce exposure to both Korean and Taiwanese equities. South Korea alone saw roughly one billion dollars of outflows in the recent period. That pressure has been real and visible in daily trading.
The selling sits inside a larger wave of weakness across Asian technology stocks. Concerns over the durability of artificial intelligence related spending, rising oil prices, and a more hawkish tone from several central banks have all contributed. When multiple macro forces align against a region, even solid individual companies can get caught in the downdraft.
Still, sustained foreign selling eventually creates its own opportunity. Once the most aggressive sellers finish reducing positions, the marginal buyer can begin to matter more. We have seen that pattern play out in other markets after sharp corrections.
Understanding the Scale of the Valuation Gap
A price-to-earnings multiple three standard deviations below the historical average is rare. Markets do not stay at those levels indefinitely without either a deep fundamental deterioration or a subsequent recovery in multiples. The current assessment leans toward the second path, provided earnings do not collapse further.
I find the non-memory portion of the market particularly interesting here. When half the index trades at a discount exceeding 30 percent to estimated fair value, the opportunity set expands beyond the usual semiconductor names that dominate foreign portfolios. Diversification inside the country becomes more practical.
Perhaps the most interesting aspect is how little consensus exists right now. Some investors see only the risks of slowing growth and persistent outflows. Others see a market that has already discounted a fairly harsh scenario. That divergence often marks periods when selective long-term positions can be built with less competition.
What the Target Cut Actually Signals
Lowering a target from 12,000 to 9,000 is not a minor adjustment. It reflects a meaningful reassessment of the near-term path. Yet the decision to maintain an overweight recommendation at the same time tells a different story. The analysts still believe the market offers attractive absolute upside even after the revision.
That combination is worth sitting with for a moment. A lower target does not automatically equal a bearish stance. Context matters. When the starting point has already fallen 40 percent, a revised target can still leave substantial room for gains.
In my experience, these moments of apparent contradiction often prove useful. They force a clearer look at what is already priced in versus what could still improve. Volatility has risen, earnings growth has slowed, and foreign money has left. Those facts are not in dispute. The open question is whether the price adjustment has gone far enough relative to the remaining fundamentals.
Positioning Ideas in a Volatile Environment
Building exposure in this kind of market requires patience and selectivity. Broad index buying may work over a multi-year horizon, yet nearer-term results will likely depend on which segments recover first. The preferred areas mentioned earlier—power, industrials, governance beneficiaries, reflation plays, and certain cultural themes—offer a starting framework.
Risk-reversal strategies also receive attention. In practical terms that often means looking for situations where downside has been heavily priced while upside optionality remains underappreciated. Memory names themselves may eventually fit that description if the extreme earnings decline scenario proves too pessimistic.
I have found that markets rarely move in straight lines after such sharp corrections. Periods of stabilization, false starts, and renewed selling can all appear before a more sustained recovery takes hold. Anyone considering new positions should expect that path rather than a smooth rebound.
The Role of Corporate Governance Reform
One longer-term theme that continues to attract interest is the push for better corporate governance across Korean companies. Improvements in capital allocation, shareholder returns, and transparency have the potential to re-rate parts of the market independently of the global technology cycle.
Progress on this front has been uneven, yet the direction remains constructive. Companies that demonstrate clearer commitment to minority shareholders often trade at narrower discounts over time. That dynamic can compound the valuation recovery already implied by the broader market numbers.
For investors willing to look beyond the next quarter’s earnings print, this theme offers a structural overlay that pure cyclical bets cannot match. It is one reason the overweight stance remains in place despite the lowered target.
Macro Cross-Currents Still Matter
Rising oil prices and shifting central bank communication have added another layer of complexity. Higher energy costs can pressure margins for certain industrial firms while also influencing inflation expectations more broadly. Hawkish policy signals raise the discount rate applied to future earnings, which weighs on valuation multiples.
These factors help explain why the sell-off has been so broad. They also highlight why any recovery will likely require some stabilization on the macro side. Markets do not need perfect conditions to advance, but they do tend to struggle when multiple headwinds arrive at once.
At the same time, extreme valuation levels have historically provided a cushion against further deterioration. When multiples already embed a high degree of caution, additional negative news sometimes produces smaller price reactions. That pattern is not guaranteed, yet it is one reason the residual upside calculation remains sizable.
Balancing Caution with Opportunity
No one should pretend the path ahead looks smooth. Earnings estimates may still come down further. Foreign outflows could persist for a while longer. Geopolitical or trade-related surprises remain possible. All of those risks deserve respect.
Yet the combination of a 40 percent drawdown, multi-standard-deviation cheap valuations, and an explicit overweight recommendation from a major house creates a setup that is hard to ignore completely. The question is less about whether risks exist and more about whether those risks are already reflected in current prices.
I keep returning to the non-memory half of the index. That segment offers a way to participate in any broader recovery while reducing concentration in the most debated semiconductor names. Diversification inside a single country market can still improve the overall risk profile of a position.
Looking Ahead with Measured Expectations
The revised 9,000 target implies meaningful appreciation from today’s levels. Reaching that number would require some combination of earnings stabilization and multiple expansion. Neither is guaranteed in the near term, but both become more plausible if volatility begins to settle and foreign flows stabilize.
Investors who focus only on the size of the target cut may miss the larger point. The absolute upside remaining after the cut still exceeds 60 percent. That kind of asymmetry is uncommon in developed or emerging markets at most points in the cycle.
Patience will likely prove more valuable than precision timing. Building positions gradually, emphasizing the less-crowded segments of the market, and maintaining awareness of macro developments offers a practical approach. The current environment rewards those who can tolerate short-term noise in pursuit of longer-term valuation normalization.
South Korea’s equity market has delivered both strong rallies and sharp corrections over the years. The present moment combines elements of both histories. A significant correction has already occurred. The question now is whether the subsequent recovery phase has begun to take shape beneath the surface volatility.
For those willing to look past the headlines of a target reduction, the underlying message is more constructive than it first appears. Valuations have become extreme. Selective opportunities remain visible. And the residual upside, even after a substantial cut, continues to look substantial. That combination deserves careful attention from anyone following Asian equities.
Markets have a habit of surprising both optimists and pessimists. The Kospi’s current setup contains enough of both elements to keep the debate lively for months ahead. Watching how earnings evolve, how foreign capital behaves, and how governance reforms progress will provide the real-time feedback that ultimately determines whether the revised target proves conservative or still too ambitious.
In the end, the most useful stance may be one of cautious engagement rather than outright avoidance or aggressive chasing. The numbers on valuation are hard to dismiss. The risks are equally real. Navigating between those two realities is where the practical work of investing in this market now sits.