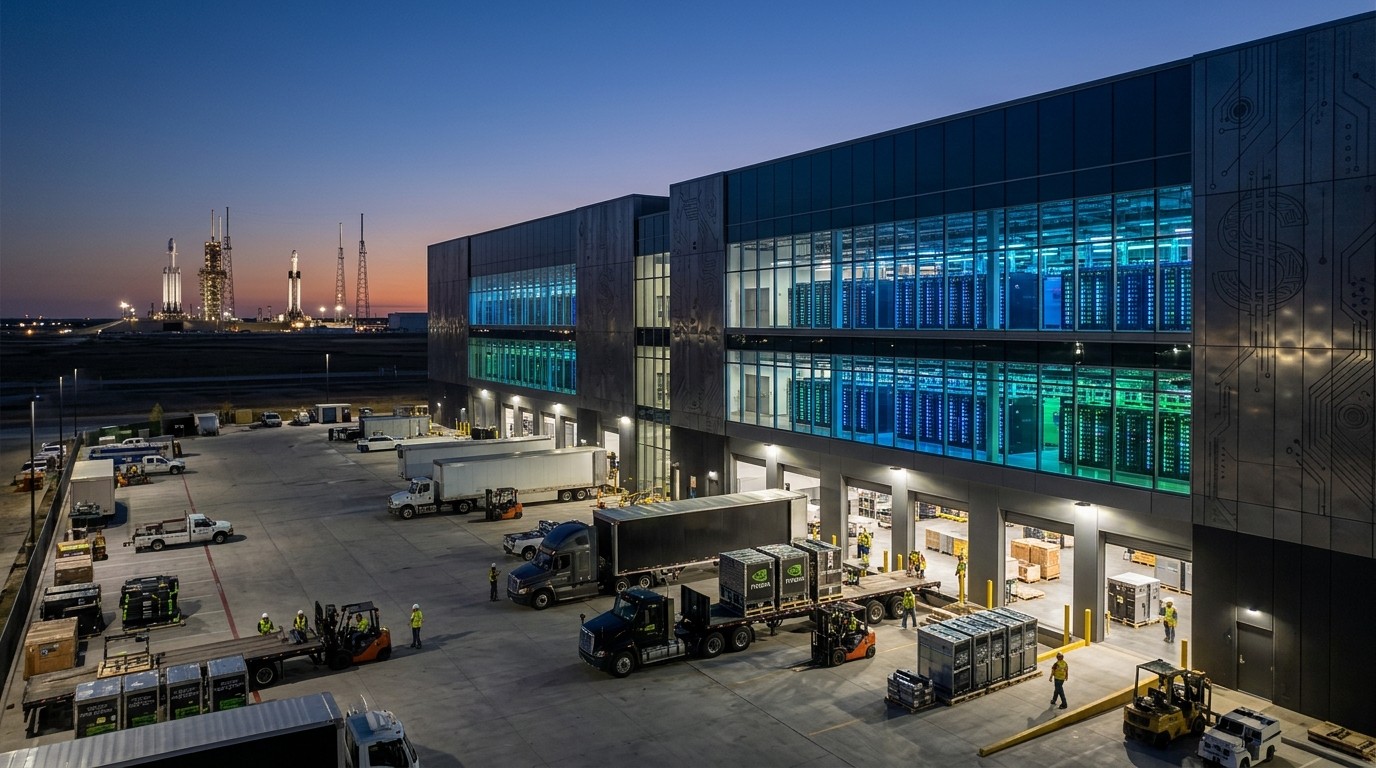

I still remember the first time I realized how hungry artificial intelligence had become for pure computing power. It was not a flashy product launch or a celebrity tweet. It was a quiet conversation with someone who builds data centers for a living. He told me, almost casually, that the next bottleneck would not be algorithms or talent. It would be the ability to finance mountains of specialized chips without destroying your balance sheet. That comment stuck with me. So when Elon Musk announced that SpaceX had closed a $40 billion debt package specifically to buy graphics processing units, I paid attention. This is not just another funding round. It is a signal about who will still be standing when the current AI infrastructure wave finishes cresting.
Why SpaceX Can Borrow What Others Cannot
SpaceX sits in a rare position. Most companies racing to build AI capacity live or die by the next funding cycle. SpaceX does not. Its two core businesses, Starlink satellite internet and orbital launch services, generate real cash every quarter. That cash flow, combined with an investment-grade credit profile, gave lenders confidence that the company could service a large debt load even if AI revenues took longer than expected to materialize.
Musk described the package as primarily callable debt tied to the GPUs themselves. The chips are expected to begin arriving in the first half of 2027. By structuring the financing this way, SpaceX keeps the obligation somewhat flexible. If the AI opportunity evolves, the company can adjust. That kind of optionality is expensive, and only a handful of players can afford it right now.
The Scale of the Commitment
Forty billion dollars is not a rounding error. For context, that figure exceeds the annual capital expenditure of many established technology giants only a few years ago. SpaceX is deploying this capital into a single category of hardware: high-end GPUs designed for training and running large AI models. The company has already renamed its AI efforts Super Intelligence, or SI for short. In the most recent quarter, that segment produced $7.56 billion in revenue, up nine times from the same period a year earlier. Those numbers explain why lenders were willing to write such a large check.
I find the growth rate almost hard to process. Jumping from under a billion to more than seven billion in twelve months is the kind of expansion usually reserved for software companies scaling user bases, not for hardware-heavy infrastructure plays. Yet SpaceX appears to have found a way to turn AI compute into a meaningful revenue stream faster than many pure-play competitors.
How the Deal Was Structured
Earlier reports suggested the company was exploring a special purpose vehicle to keep the debt off its main balance sheet. The goal was clear: protect the investment-grade rating that makes future borrowing cheaper. Whether the final structure used that vehicle or a more traditional corporate facility, the outcome is the same. SpaceX secured long-term access to the chips it needs without jeopardizing the credit profile that supports its launch and satellite businesses.
Callable features give the company another layer of control. If interest rates fall or if internal cash generation exceeds expectations, SpaceX can retire portions of the debt early. That flexibility matters in a sector where technology cycles move faster than traditional industrial assets.
The Broader AI Financing Crunch
What caught my attention even more than the size of the deal was Musk’s warning about the rest of the market. He stated that debt markets have largely closed to companies that lack substantial revenue outside of AI data centers. In his view, more than two hundred so-called neocloud operators face potential failure or forced consolidation. Only a small number will survive.
That prediction feels plausible. Neocloud firms sprung up quickly to meet demand for specialized AI infrastructure. Many relied on continuous access to cheap capital. When capital becomes selective, those without diversified cash flows suddenly look fragile. SpaceX, by contrast, can point to Starlink subscriptions and launch contracts as independent sources of repayment capacity.
Debt markets have largely shut off access to financing for companies without substantial revenue outside AI data centers.
I have watched similar cycles before. In the early days of cloud computing, dozens of smaller providers competed aggressively until the largest platforms consolidated the market. AI infrastructure appears headed down a comparable path, only the capital intensity is higher and the technology risk is greater.
What Investment Grade Really Means Here
Investment-grade status is more than a badge. It translates directly into lower interest costs and broader access to institutional capital. SpaceX achieved that standing through years of operational delivery. Reusable rockets reduced launch costs. Starlink scaled to millions of users. Those achievements created a foundation of trust that pure AI startups simply do not possess yet.
Lenders evaluating the $40 billion package could underwrite against existing cash flows rather than solely against future AI projections. That distinction is decisive. When markets tighten, credit committees favor borrowers who can demonstrate repayment capacity independent of the new venture.
The Arrival Timeline and Its Implications
The GPUs are scheduled for delivery across the first and second quarters of 2027. That timeline gives SpaceX roughly eighteen months to prepare data center capacity, power infrastructure, and cooling systems. It also gives competitors a window to try to match the commitment. Few will succeed at similar scale.
Perhaps the most interesting aspect is the signal this sends to chip suppliers. Securing such a large forward order provides manufacturers with visibility into demand. In an industry still recovering from previous boom-and-bust cycles, that visibility is valuable. It may influence production planning and allocation decisions for the next several years.
Super Intelligence as a Business Unit
SpaceX did not treat AI as a side experiment. Management elevated it to the company’s largest business unit by recent revenue. That internal prioritization matters. Resources, talent, and executive attention follow the numbers. When a segment grows ninefold in a single year, it quickly becomes impossible to ignore.
I suspect the integration of AI capabilities into both Starlink network management and launch operations creates internal demand that pure external customers cannot match. Vertical integration of this kind often produces durable advantages that are difficult for specialized competitors to replicate.
- Existing launch and satellite cash flows support the debt service
- Investment-grade rating lowers the cost of capital
- Callable structure provides future flexibility
- Internal AI applications create captive demand
- Scale of the order improves negotiating position with suppliers
Risks That Still Exist
No financing of this size is risk-free. Technology risk remains. The specific GPU architectures arriving in 2027 may not match the optimal designs required by then. Power availability and data center construction timelines can slip. Regulatory scrutiny of large AI deployments continues to increase in several jurisdictions.
There is also execution risk. Absorbing tens of billions of dollars of specialized hardware and turning it into profitable services is a non-trivial operational challenge. SpaceX has demonstrated competence at complex engineering projects, yet AI infrastructure introduces different constraints around energy, latency, and software orchestration.
Still, the alternative looks worse. Companies that cannot secure chips at scale risk falling permanently behind. In that light, the decision to lock in supply early appears rational even with the associated leverage.
What This Means for the Wider Market
The SpaceX announcement arrives at a moment when capital markets have grown more selective. Equity valuations for pure AI infrastructure plays have compressed. Debt investors now demand clearer paths to cash flow. The result is a classic shakeout environment. Strong operators with diversified revenues consolidate capacity. Weaker ones seek partners, sell assets, or exit.
In my view, the next two years will determine the lasting structure of the AI compute industry. A handful of well-capitalized players with access to both chips and power will dominate. Everyone else will compete for the remaining scraps or pivot into specialized niches.
SpaceX has positioned itself firmly in the first group. The $40 billion package is not merely a financing event. It is a declaration of intent to remain at the frontier of AI infrastructure for the rest of the decade.
Lessons for Other Operators
Several practical takeaways emerge for anyone building or investing in this space. First, diversified cash flows matter more than ever. Relying solely on future AI contracts leaves a company exposed when credit conditions tighten. Second, credit ratings and balance sheet strength influence access to the largest hardware allocations. Third, timing the arrival of capacity to match expected demand remains critical. Too early and you carry expensive idle assets. Too late and customers move elsewhere.
I have found that the operators who treat capital structure as a strategic tool rather than an afterthought tend to navigate these cycles more successfully. SpaceX appears to have internalized that lesson.
Looking Ahead to 2027 and Beyond
By the time the GPUs begin arriving, the competitive landscape will almost certainly look different. Some of the two hundred neocloud firms Musk mentioned will have disappeared. Others will have been absorbed. The survivors will control meaningful shares of available high-end compute. SpaceX intends to be among them, and the financing closed this weekend makes that ambition more credible.
Whether Super Intelligence ultimately becomes a dominant external platform or primarily supports SpaceX’s own ambitious goals remains to be seen. Either outcome would represent a significant expansion of the company’s capabilities. For now, the market has received a clear message: the companies that can still borrow at scale for AI hardware are the ones with proven, non-AI businesses generating real cash today.
That reality will shape investment decisions, partnership strategies, and technology roadmaps across the entire sector for years to come. The $40 billion commitment is large in absolute terms. Its true significance lies in what it reveals about the new hierarchy forming inside the AI infrastructure economy.
The next chapter will be written in data centers, power purchase agreements, and quarterly cash flow statements rather than press releases. SpaceX has bought itself a prominent seat at that table. Many others are still looking for a way to enter the room.
The Human Element Behind the Numbers
Behind every large financing sits a team of people who spent months negotiating terms, modeling scenarios, and managing relationships with lenders. I have spoken with enough corporate finance professionals to know that deals of this magnitude rarely feel smooth from the inside. There are late nights, revised models, and moments when the entire package appears ready to collapse. Closing it requires persistence as much as financial engineering.
SpaceX has built a culture that treats ambitious engineering goals as normal. Extending that mindset to capital markets appears to have paid off. The company convinced sophisticated investors that its combination of launch reliability, satellite network growth, and emerging AI capabilities justified a substantial commitment of capital at a time when many other borrowers were being turned away.
Comparing Approaches Across the Industry
Different companies are solving the same problem in different ways. Some are raising equity at high valuations. Others are forming joint ventures with power producers or chip manufacturers. A few are exploring creative leasing structures. SpaceX chose a relatively straightforward path: large-scale callable debt backed by an investment-grade credit profile and diversified operations. That choice reflects both opportunity and constraint. The company has the credit quality to support significant leverage. It also has internal uses for the compute that reduce reliance on external customers during the ramp-up period.
I suspect we will see more hybrid approaches in the coming quarters. Pure debt may become harder to obtain for anyone without SpaceX’s unique combination of attributes. Equity markets remain open but demand higher returns to compensate for perceived risk. The middle ground of structured finance and asset-backed facilities will likely expand.
Power, Land, and the Hidden Constraints
Chips alone do not create AI capacity. They require enormous amounts of electricity, sophisticated cooling, and suitable real estate. Securing those complementary resources often proves more difficult than ordering the GPUs. SpaceX’s existing industrial footprint and experience with large-scale infrastructure projects may provide advantages here that pure software or cloud companies lack.
Anyone following the sector closely has noticed that power availability has become a primary filter for new data center projects. Regions with abundant, reliable, and relatively affordable electricity are attracting the bulk of new investment. Companies that locked in long-term power agreements early enjoy a structural edge. Those still searching face higher costs and longer delays.
The Role of Existing Revenue Streams
Starlink and the launch business did more than provide collateral. They demonstrated that SpaceX can take complex, capital-intensive technologies and turn them into growing commercial operations. That track record reduces perceived execution risk for the AI initiative. Lenders are not simply betting on a new idea. They are backing a management team that has already commercialized two previous moonshot projects.
This point is easy to understate. In technology, the ability to move from prototype to scaled revenue is rarer than technical brilliance. SpaceX has shown that ability twice. Extending the same discipline to Super Intelligence is a logical next step rather than a radical departure.
Potential Spillover Effects
A successful build-out of AI capacity inside SpaceX could influence other parts of the business. More sophisticated network optimization for Starlink. Improved trajectory planning and autonomous systems for launches. New services offered to government and commercial customers who need secure, high-performance compute in specialized environments. The internal synergies may ultimately prove as valuable as any external cloud offering.
At the same time, the company must avoid the classic trap of over-expanding into areas that dilute focus. Maintaining the reliability culture that defines its launch program while rapidly scaling an AI infrastructure business will require careful prioritization.
Investor Perspective on the Transaction
From an investor standpoint, the financing strengthens SpaceX’s competitive position without the dilutive effects of a large equity raise. Existing shareholders retain more of the upside if Super Intelligence succeeds. The callable nature of the debt further protects the company if market conditions or technology trajectories change. Of course, leverage always cuts both ways. Higher fixed obligations increase the cost of any future missteps. On balance, given the company’s current cash generation and growth trajectory, the structure appears measured rather than aggressive.
I have watched too many technology companies load up on debt during boom periods only to struggle when the cycle turns. SpaceX’s decision to keep the debt callable and to ground it in existing operations suggests an awareness of those historical patterns.
The Consolidation Wave Ahead
Musk’s prediction of widespread failures among neocloud operators deserves serious attention. The economics of AI infrastructure favor scale. Larger clusters deliver better utilization. Better utilization improves unit economics. Improved unit economics attract more customers and more capital. The feedback loop is powerful and tends to produce winner-take-most outcomes.
Companies that cannot reach critical mass will find it increasingly difficult to compete on price or performance. Many will seek acquisition by better-capitalized players. Others will pivot toward niche applications or managed services. A few may simply shut down. The process will be messy and, for employees and investors in the weaker firms, painful. Yet it is the normal functioning of a capital-intensive industry reaching maturity.
Final Thoughts on Strategic Positioning
SpaceX has used its unique position to secure a strategic asset at a moment when that asset is both scarce and essential. The $40 billion debt package is large, but it is also carefully designed. It leverages the company’s strengths, protects its credit profile, and buys time to execute. In an industry moving as quickly as AI infrastructure, time and supply security are often more valuable than headline valuations.
Whether this specific bet pays off at the scale currently envisioned will depend on execution over the next several years. What is already clear is that SpaceX intends to compete at the highest level of the AI compute race. Few other organizations currently possess the combination of financial strength, operational track record, and technical ambition required to make that claim credible. The financing closed this weekend simply makes the claim harder to dismiss.
As the GPUs begin arriving in 2027, the industry will learn which strategies worked and which did not. Until then, the SpaceX deal stands as a benchmark for what is still possible when a company brings more to the table than a promising slide deck and a need for capital. Real businesses with real cash flow still command respect from lenders. That simple truth may prove the most important lesson of this entire episode.