
Have you noticed your online orders taking longer or costing more to ship lately? I certainly have. Just last week a simple pair of shoes arrived with a delivery fee that made me double-check the invoice. Something bigger is happening behind those higher charges, and it starts at the pump.
Why Package Shipping Costs Keep Climbing
The pressure is moving straight from diesel tanks to the price of every cardboard box that rolls out of warehouses. Market watchers now expect U.S. package shipping expenses to hit fresh records before the year ends. Ground delivery rates for the fourth quarter look set to climb about 5.8 percent compared with last year. Express parcels could jump even harder, around 13.8 percent. Those numbers are not abstract. They land on the final bill for shoppers and the cost sheets for every retailer that ships products.
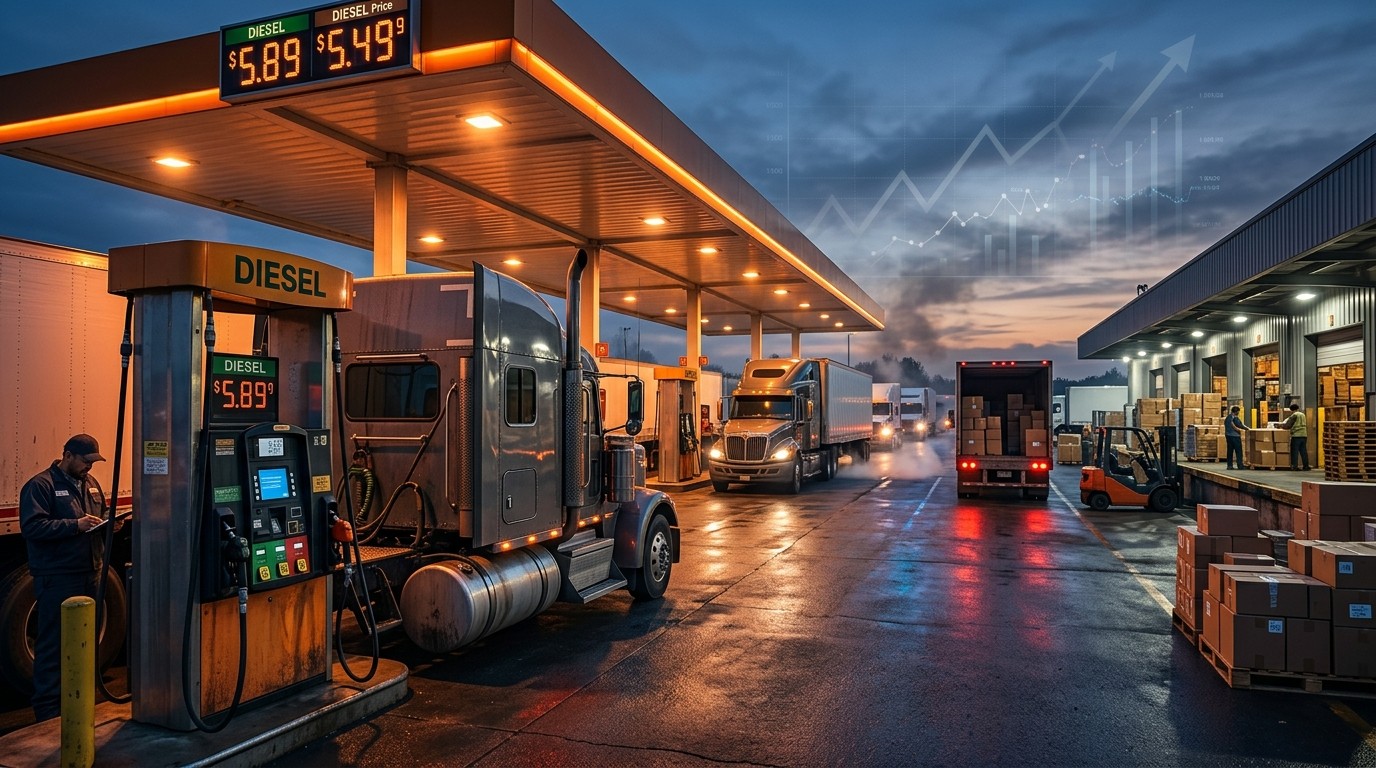
The main driver sits in the diesel market. Recent figures show average highway diesel sitting near 6.28 dollars a gallon. That represents a climb of roughly 65 percent since late February. Incremental supply has stayed tight. Analysts keep pointing out that extra barrels from certain sources simply are not materializing fast enough. Demand, meanwhile, refuses to ease. If winter turns colder than usual, the squeeze could tighten further.
One seasoned commodities strategist put it plainly. The amount of extra diesel that can arrive in the short term is limited. The signal that limitation sends may actually feel worse than the physical shortfall itself. Markets often react more to the story than to the pure barrels. That reaction helps keep prices sticky even when some relief appears possible.
Fuel Surcharges Matter More Than Raw Diesel
Here is the part that surprised me when I dug into the details. Diesel itself is expensive, yet it may not be the biggest reason delivery bills keep rising. Carriers have changed the way they calculate fuel surcharges. That shift acts as the real accelerator.
Look back a few years. In early 2021 diesel averaged close to 2.90 dollars a gallon and fuel surcharges made up only about 7.75 percent of base freight rates. Today the picture looks different. One major carrier lists a fuel surcharge near 29.5 percent. Another sits right around 29 percent. Those percentages apply on top of already higher base rates. Even if diesel stopped rising tomorrow, the surcharge structure would still push total costs upward.
The underlying signal that limited incremental supply sends may suggest the outlook is worse than many first thought. Signaling can sometimes weigh heavier than the actual supply and demand numbers.
I find that distinction important. It means the industry has built a new normal for how fuel costs get passed along. Shoppers feel it as higher checkout totals. Businesses feel it as thinner margins on every order that leaves the warehouse.
How Retailers Try to Soften the Blow
Companies are not sitting still. Many now encourage customers to return online purchases to physical stores instead of mailing them back. That move cuts one leg of the shipping journey. Others are testing additional delivery partners whose fuel surcharges sit much lower. One network charges roughly 8 percent. Another keeps the figure near 3.5 percent. On paper those options look attractive.
Yet the trade-offs are real. Spreading volume across several carriers can erode the volume-based discounts that big shippers normally enjoy. Switching partners also takes time. Holiday shipping schedules get locked in months ahead. Changing course in October or November is rarely simple. I have watched more than one logistics manager scramble when a last-minute shift collided with peak-season volume.
- Encourage in-store returns to cut outbound shipping legs
- Test lower-surcharge carriers for selected product lines
- Review volume discounts carefully before splitting shipments
- Lock holiday plans early so sudden changes stay limited
Perhaps the most interesting aspect is how these small operational tweaks add up. A few percentage points saved on surcharges can protect margins when order volumes spike. Still, none of the adjustments erase the broader pressure created by elevated diesel and the new surcharge formulas.
The Supply Side Story Behind Sticky Prices
Diesel markets have always been sensitive to refining capacity and seasonal demand. Right now the incremental barrels that could ease the market remain constrained. Refineries face their own maintenance schedules and feedstock costs. Global trade patterns add another layer of complexity. When extra supply fails to appear quickly, prices tend to stay elevated longer than pure demand numbers might suggest.
Cold weather could intensify the situation. Heating demand competes for the same middle-distillate barrels that power trucks. A colder-than-average winter would pull more diesel into residential and commercial heating, leaving less for the transportation sector. That competition shows up quickly at the pump and then, with a lag, in shipping invoices.
In my experience watching commodity cycles, the signaling effect often outlasts the physical tightness. Traders and fleet managers plan for the worst-case path. Their caution keeps risk premiums in the market even after some barrels begin to flow. The result is a sticky price environment that filters through to every package on the road.
Ground Versus Express: Different Pain Points
Not every delivery feels the increase the same way. Ground service faces a projected 5.8 percent year-over-year rise. That still hurts, especially for high-volume retailers that move thousands of boxes daily. Express service, however, looks set for a steeper 13.8 percent climb. Time-sensitive shipments carry higher fuel intensity and more complex routing. Those characteristics amplify the impact of both diesel and surcharge formulas.
Shoppers who rely on next-day or two-day delivery will notice the difference first. Retailers that market free expedited shipping absorb the cost or raise the free-shipping threshold. Either choice affects the customer experience. I have seen more brands quietly lift the minimum order size required for free express delivery. The math simply forces the change.
| Service Type | Projected Rate Rise | Key Pressure |
| Ground Delivery | 5.8 percent | Volume and fuel |
| Express Parcel | 13.8 percent | Speed and routing |
| Lower-Surcharge Options | Variable | Network reach |
The table makes the divergence clear. Express customers pay a larger premium for speed while ground customers still face meaningful increases. Both groups ultimately share the same underlying diesel reality.
What the New Surcharge Reality Means for Everyday Buyers
Most people never look at fuel surcharge tables. They simply see a higher total at checkout. Yet understanding the structure helps explain why the numbers keep moving even when diesel stabilizes for a few weeks. The percentage applied to the base rate has expanded dramatically compared with earlier years. That expansion acts like a permanent lift to the cost base.
Retailers pass along what they can. Some absorb part of the increase to protect conversion rates. Others raise product prices modestly across the board. A third group experiments with delivery windows that allow slower, cheaper routes. Each approach carries its own customer reaction. I have found that transparent communication works better than silent price hikes. Shoppers tolerate higher fees more readily when they understand the fuel background.
Holiday season intensifies every calculation. Plans locked months earlier leave little room for sudden carrier switches. Inventory already sitting in fulfillment centers must move under the current rate structure. That rigidity makes the fourth-quarter projections especially relevant. The numbers arriving now will shape the invoices that hit in November and December.
Longer-Term Questions for Logistics Networks
Beyond the immediate season, the diesel and surcharge combination raises structural questions. Will carriers keep the higher percentage formulas even if diesel eventually retreats? History suggests surcharge tables often lag price declines. The lag protects carrier margins but leaves shippers carrying elevated costs longer than pure fuel economics might justify.
Fleet operators face their own decisions. Some accelerate orders for more efficient trucks. Others experiment with alternative fuels on selected routes. Those investments take years to show up in lower operating costs. In the meantime the current diesel environment remains the daily reality.
Perhaps the most interesting aspect is how packaging and routing innovation might eventually offset part of the pressure. Lighter packaging reduces fuel burn per package. Better route density cuts empty miles. Neither solution arrives overnight, yet both sit high on many logistics roadmaps. Progress on those fronts could soften the next cycle even if diesel stays elevated.
Practical Steps Retailers Are Taking Right Now
Several concrete moves appear repeatedly across conversations with logistics teams. First, many are auditing every active surcharge schedule. Small differences between carriers become material once volume scales. Second, they test hybrid networks that keep core volume with primary partners while shifting overflow to lower-surcharge options. Third, they expand in-store pickup and return programs. Each package that never enters the long-haul network avoids the highest fuel multipliers.
- Compare current fuel surcharge tables side by side
- Pilot limited volume with alternative networks
- Expand click-and-collect options in high-traffic stores
- Adjust free-shipping thresholds to reflect true cost
- Communicate fuel-driven changes clearly to customers
None of these steps eliminates the diesel problem. They do, however, create breathing room. In a market where rates can move several percentage points in a single quarter, that breathing room matters.
Looking Ahead Through the Winter Months
The next few months will test every assumption. If temperatures stay mild, some of the heating-related demand pressure may ease. If the cold arrives early and stays late, diesel could firm further. Either path will show up first in wholesale markets and then, with a short lag, in the surcharge tables that carriers publish.
Retailers that locked rates early hold an advantage. Those still negotiating face a tougher landscape. For everyday shoppers the message stays simple: delivery fees are unlikely to retreat soon. The combination of elevated diesel and expanded surcharge formulas has reset the cost baseline higher.
I keep returning to the same observation. The physical barrels matter, yet the way costs get calculated matters just as much. Understanding both pieces gives a clearer picture of why that pair of shoes cost more to ship than it did last year. The pressure is real, the adjustments are underway, and the final invoices will continue to reflect both.
The story is still unfolding. Diesel remains tight, surcharges remain elevated, and the holiday calendar waits for no one. Retailers that adapt fastest will protect more of their margins. Shoppers who plan purchases with delivery costs in mind will feel fewer surprises. And the trucks will keep rolling, carrying both packages and the higher fuel bills that come with them.
Watching this market has reminded me how quickly a change at the pump becomes a change on the doorstep. The numbers may shift week to week, yet the direction for the current quarter looks firmly upward. That reality shapes decisions for carriers, for retailers, and ultimately for anyone who clicks the buy button and waits for the box to arrive.
In the end the most practical takeaway is straightforward. Expect higher shipping costs through the rest of the year. Look for retailers that offer flexible delivery or return options. And remember that the diesel price you see on the highway is only part of the calculation. The rest lives inside those surcharge percentages that now sit near thirty percent for several major networks. That combination explains why the delivery line on your next order looks different from the one you remember from earlier seasons.