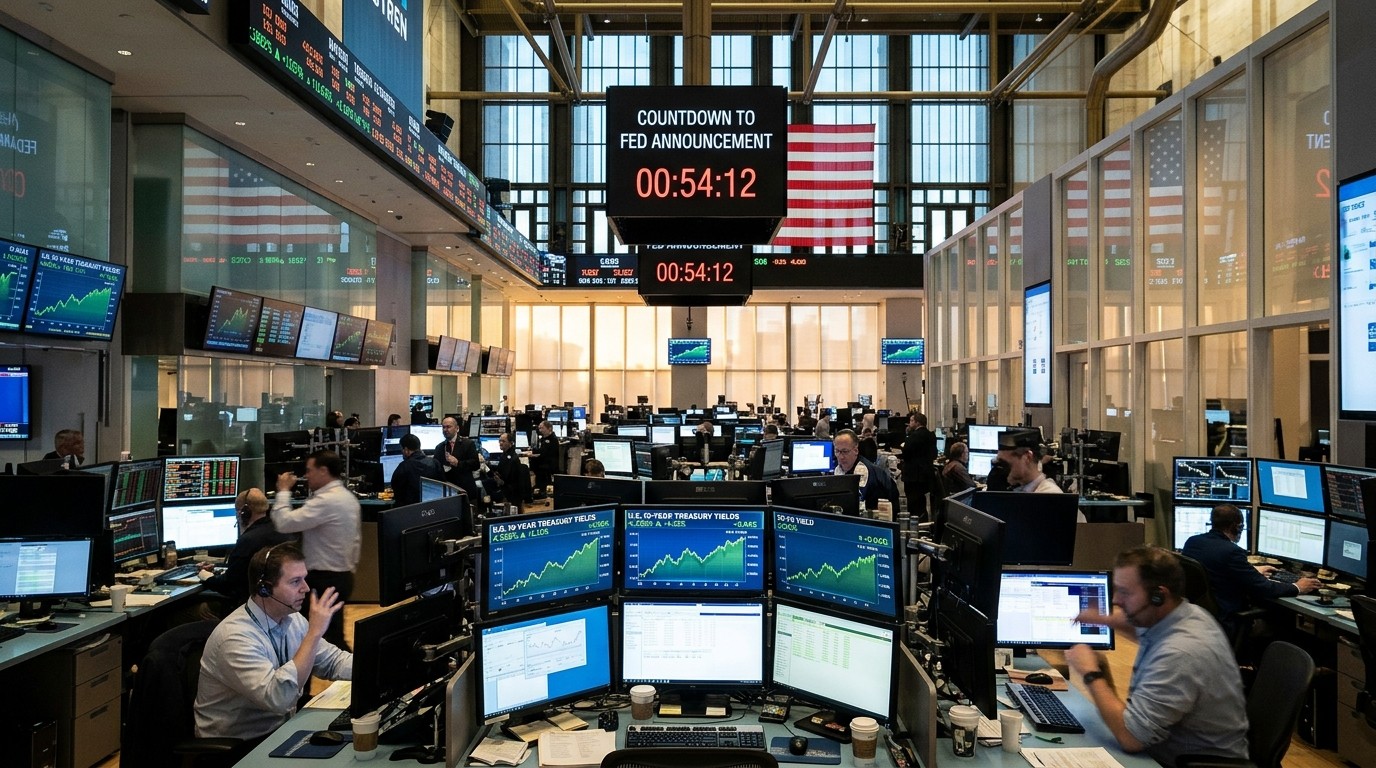

Have you checked the bond market this morning? Something quiet but meaningful is already happening. Treasury yields started climbing before most people even finished their first coffee, and the move feels deliberate. Investors are positioning themselves ahead of the Federal Reserve’s latest interest rate decision, and the numbers are telling a clear story if you know how to read them.
The 10-year Treasury note yield pushed more than two basis points higher, settling around 5.0134 percent. That single benchmark matters more than most people realize because it quietly influences mortgage rates, auto loans, and even credit card interest. At the same time the two-year yield edged up one basis point to 4.7494 percent, while the 30-year yield also rose, reaching 5.3200 percent. These are not dramatic swings, yet they carry weight on a day when the central bank is about to speak.
Why Yields Are Moving Higher Right Now
Markets rarely wait politely for official announcements. Traders spend the hours before a Federal Reserve decision adjusting positions, testing scenarios, and protecting themselves against surprises. Today that preparation is visible in the slight upward pressure on yields across the curve.
A basis point equals one hundredth of one percent. It sounds tiny, but when you multiply it across trillions of dollars in outstanding debt the real-world impact becomes substantial. Yields and bond prices move in opposite directions, so when yields rise the prices of existing bonds fall. That simple relationship is why so many portfolio managers stay glued to these numbers.
The Market’s Current Rate Expectations
Traders currently assign roughly a 90.6 percent probability that the Federal Open Market Committee will keep the target range unchanged at 3.75 to 4.00 percent. That level of conviction is high, yet it does not mean the market is relaxed. Attention has already shifted to the language that will accompany the decision and to the signals about the December meeting.
At the moment the odds of a 25-basis-point increase at the December gathering sit near 76.5 percent. Those expectations can shift quickly once the statement and the press conference begin. I have watched similar setups many times, and the post-decision volatility often exceeds the pre-decision move we are seeing this morning.
What the Different Maturities Are Telling Us
The two-year yield tends to track near-term policy expectations most closely. Its modest rise suggests traders are not pricing in an immediate surprise today, yet they remain alert. The 10-year yield, by contrast, reflects a broader mix of growth, inflation, and risk sentiment. Its larger move hints that some investors are protecting against the possibility of firmer policy language or stronger economic data still to come.
The 30-year yield often reacts to longer-term forces, including geopolitical uncertainty and structural changes in government borrowing. Its smaller but still positive move keeps the entire curve under mild upward pressure. When all three maturities rise together the message is usually that markets are preparing for a slightly higher path of rates than previously assumed.
How Rising Yields Touch Everyday Borrowing Costs
Most households never buy a Treasury note, yet they feel the consequences of these moves. Mortgage rates often follow the 10-year yield with a lag. Auto loans and many other forms of consumer credit also respond. Even credit card rates, which are usually tied to short-term benchmarks, eventually feel the broader shift in financing costs.
When the 10-year yield sits above five percent, the cost of locking in a long-term fixed mortgage stays elevated. Homebuyers notice. Refinancing activity slows. That is why a two-basis-point move on a quiet Wednesday morning still matters to people who are shopping for a house or considering a car purchase.
Bond yields are the quiet messengers of the economy. They rarely shout, but they almost always tell the truth about where money is flowing and where it is becoming more expensive.
Looking Ahead to Tomorrow’s Economic Releases
Thursday brings a heavy cluster of data. The personal consumption expenditures index, the Federal Reserve’s preferred inflation gauge, will take center stage. Alongside it come the latest readings on quarterly GDP growth, personal income, and consumer spending. Together these numbers will either reinforce or challenge the path the central bank appears to be following.
If inflation remains sticky, the case for keeping policy restrictive strengthens. If the numbers cool more than expected, markets may begin to price a gentler path. Either outcome will feed straight back into Treasury yields. In my experience the day after a Fed decision combined with fresh inflation data often produces larger moves than the decision day itself.
What Investors Should Watch in the Statement
The formal rate decision is only the starting point. The real information usually sits in the accompanying statement and in the subsequent press conference. Subtle changes in wording about inflation progress, labor market strength, or the balance of risks can move markets more than the rate decision itself.
Pay particular attention to any forward-looking language. Does the committee still see further tightening as possible? Does it emphasize data dependence more strongly than before? These nuances shape expectations for December and beyond. Seasoned traders often say the statement is more important than the decision on days when the outcome is widely anticipated.
- Watch for any shift in the description of inflation progress
- Note whether the labor market is still described as strong or beginning to soften
- Listen for references to the risks of waiting too long versus acting too soon
- Track how the market repositions in the minutes after the release
The Broader Context Behind Today’s Move
Treasury yields do not exist in isolation. They reflect a constant negotiation between growth expectations, inflation forecasts, and the supply of government debt. Recent months have seen yields remain elevated even as inflation has moderated from its peak. That resilience suggests investors still demand compensation for uncertainty around the final path of policy and the long-term fiscal outlook.
Some market participants argue that yields above five percent on the 10-year note already embed a reasonable risk premium. Others believe the premium should be larger given the size of government borrowing needs. These competing views keep the market in a state of mild tension, which is exactly what we are observing this morning.
Practical Implications for Different Types of Investors
Fixed-income investors face an immediate choice. Higher yields mean newly purchased bonds offer more attractive income. At the same time the market value of existing lower-yielding bonds declines. The trade-off is familiar but never comfortable.
Equity investors watch yields for a different reason. Rising long-term rates can pressure valuation multiples, especially for growth companies whose cash flows sit further in the future. Financial stocks sometimes benefit from a steeper yield curve, while rate-sensitive sectors such as real estate and utilities often feel pressure.
For individuals with variable-rate debt the message is simpler. Borrowing costs are unlikely to fall quickly. Anyone considering a large purchase that requires financing may want to examine current rates carefully rather than waiting for a meaningful decline that may not arrive soon.
| Maturity | Recent Yield | Change | Primary Influence |
| 2-Year | 4.7494% | +1 bp | Near-term Fed policy |
| 10-Year | 5.0134% | +2 bp | Growth and inflation outlook |
| 30-Year | 5.3200% | +1 bp | Long-term risk premium |
Why the Pre-Decision Drift Matters
Some observers dismiss small pre-announcement moves as noise. I tend to disagree. These early adjustments often reveal the market’s true comfort level with the expected outcome. When yields rise modestly ahead of a widely anticipated hold, it usually means investors are hedging against the possibility of a more hawkish tone rather than a dovish surprise.
That hedging can itself influence the eventual reaction. If enough investors have already positioned for higher yields, the actual statement may produce a smaller move than expected. Conversely, if the statement lands softer than the market has prepared for, the reverse move can be sharp. This push-and-pull is part of what makes Fed days both fascinating and stressful.
The Role of Inflation Data Still to Come
Tomorrow’s personal consumption expenditures figures will arrive with the market already sensitive. The Federal Reserve has made clear that it wants to see sustained progress on inflation before declaring victory. A hotter-than-expected reading would likely reinforce the case for keeping policy restrictive and could push yields higher still. A cooler reading might allow yields to ease, at least temporarily.
GDP growth and personal spending data will add further texture. Strong spending alongside sticky inflation would paint a picture of an economy that still needs restraint. Softer numbers would open the door to a more balanced assessment. Either way, the combination of the Fed decision and the data cluster creates a two-day window of heightened sensitivity for fixed-income markets.
How Portfolio Managers Are Likely Responding
Many professional investors use the days around a Federal Reserve meeting to rebalance duration, adjust credit exposure, and fine-tune hedges. Some will have already reduced sensitivity to rising rates. Others may be waiting for the statement before making larger shifts. The modest rise in yields this morning suggests that at least some of that positioning is already underway.
Retail investors do not need to trade every basis point, yet they benefit from understanding the backdrop. Knowing that mortgage rates are unlikely to drop sharply in the near term can influence decisions about home purchases or refinancing. Understanding that higher yields offer better income on new bond purchases can shape allocation choices inside retirement accounts.
A Longer View of the Yield Environment
Stepping back, the current level of yields remains elevated compared with the decade that followed the global financial crisis. For years investors grew accustomed to near-zero policy rates and very low long-term yields. That era appears to have ended. The market is still adapting to a world in which five percent on the 10-year note is no longer unusual.
This adjustment carries consequences for asset allocation, retirement planning, and corporate financing. Companies that grew comfortable with cheap debt must now manage higher interest expenses. Households that refinanced at historically low rates are locked in, while new borrowers face a different reality. The transition is gradual but profound.
Possible Scenarios After the Decision
Several paths remain open. The committee could deliver the expected hold while signaling that further increases remain on the table if data warrant. In that case yields might continue to grind higher. Alternatively, the statement could emphasize progress on inflation and leave more room for a pause that extends beyond December. Yields would likely ease under that outcome.
A third possibility is that the data released tomorrow force a rapid reassessment. Markets have been wrong before about the timing of policy shifts. The combination of today’s decision and tomorrow’s numbers will test the current consensus. That uncertainty is precisely why yields are already under mild upward pressure.
Keeping Perspective Amid the Noise
It is easy to become absorbed by every basis-point change. Yet the larger story is the ongoing recalibration of interest rates after a long period of unusually low levels. Today’s modest rise fits inside that broader narrative. The Federal Reserve decision will add another chapter, and the inflation data will add another still.
For anyone managing money or simply planning major financial decisions, the practical takeaway is straightforward. Borrowing costs remain elevated. Income from high-quality fixed income has become more attractive. Volatility around policy announcements is normal. Staying focused on personal time horizons and risk tolerance usually produces better outcomes than reacting to every pre-meeting flicker in the bond market.
The next few sessions will bring clearer information. Until then the market is doing what it always does before a major central bank decision: adjusting, hedging, and preparing for whatever language emerges from the meeting. The small rise in Treasury yields this morning is simply the visible edge of that preparation.
Whether you follow the bond market daily or only check in when rates affect your mortgage, the message is consistent. Interest rates are still working their way through the economy. The Federal Reserve’s next communication will shape the path, but the market is already expressing its own quiet opinion. That opinion currently points to yields that are firm rather than falling, and that reality is worth keeping in view as the decision approaches.
In the end the numbers on the screen matter less than the decisions people make in response to them. Some will lock in rates. Others will wait. Portfolio managers will adjust duration. Homebuyers will recalculate monthly payments. All of those choices are being influenced by the same modest rise in yields that appeared before most of the country even started its workday. That is how the bond market quietly shapes everyday financial life, one basis point at a time.