
Have you ever watched a major commodity market adapt almost overnight and wondered who actually ends up holding the bag? That question has been sitting with me for a while as fresh data on Russian oil flows keeps landing. The numbers tell a story that runs counter to the simple narrative many expected when restrictions first tightened. Volumes did not collapse. Destinations simply moved.
The Big Redirection of Russian Crude Flows
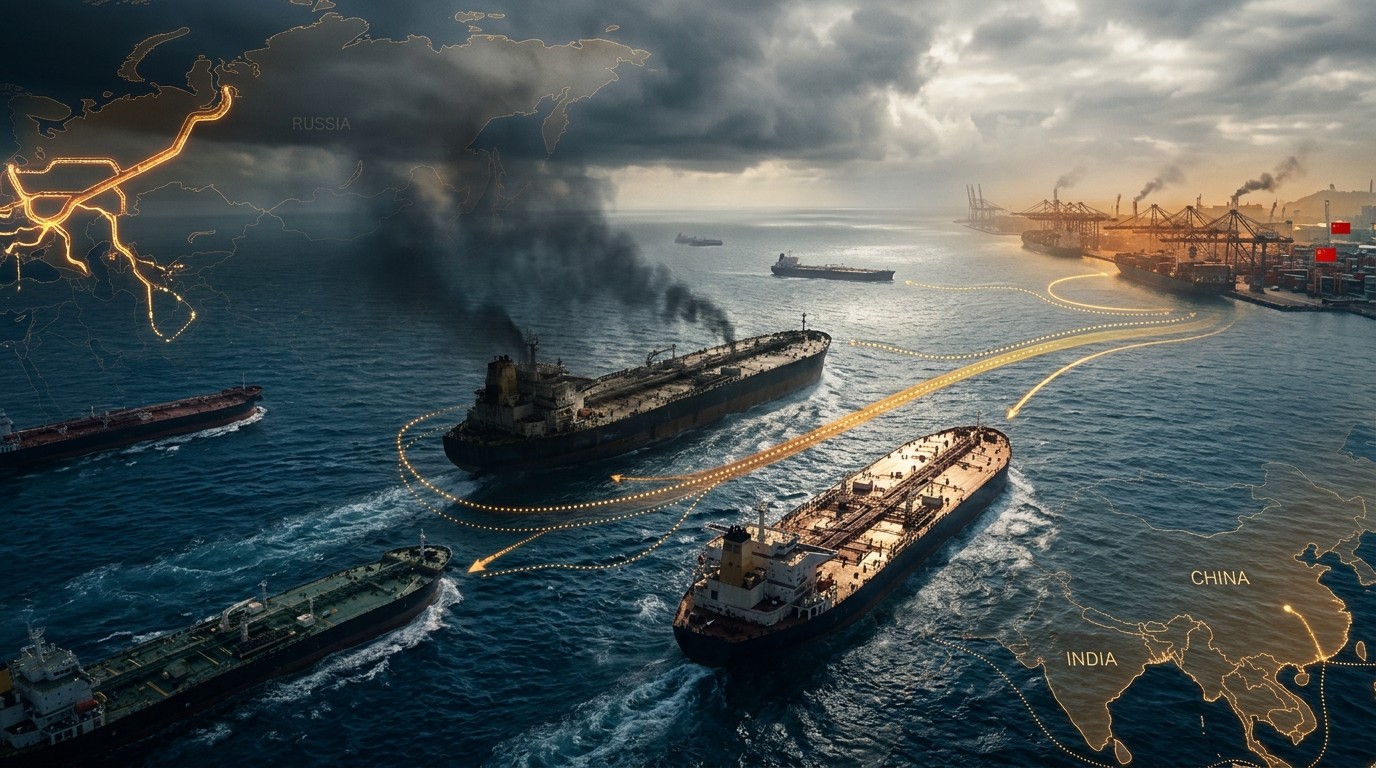
Before the conflict intensified, Europe absorbed nearly half of all Russian crude. That share has now shrunk to a thin slice of the pie. Meanwhile the combined pull from China, India and Turkey has surged past three-quarters of total exports. The shift looks clean on a chart, yet the mechanics behind it are messy, practical and revealing about how oil markets actually work when politics try to rewrite the map.
I keep coming back to one observation from market analysts tracking the numbers: the most visible effect of the restrictions has been to redistribute the global supply of oil rather than remove large volumes from the system. That distinction matters. Sanctions and related measures were jurisdictional. They constrained Western financing, insurance and direct purchases. They did not stop barrels from finding buyers willing to operate outside those systems.
How Destinations Changed Almost Completely
Look at the before-and-after picture. Pre-conflict Europe sat at roughly 48 percent of Russian crude destinations. By recent readings that figure had dropped to about 4 percent. At the same time China, India and Turkey moved from a combined 29 percent to around 77 percent. Those are not small adjustments. They represent an entire rerouting of physical trade.
The gains for the three large Asian and near-Asian buyers came at the expense of other traditional suppliers into those same markets. In China, Russian mineral fuels rose from about 18 percent of imports before the conflict to roughly 27 percent afterward. That displaced volumes that previously arrived from Australia, Iran, South Korea, Saudi Arabia, Singapore and Europe itself. India tells an even sharper story. Russian crude jumped from just over 1 percent of its import mix to around 24 percent, while shipments from Nigeria, Iran and Saudi Arabia lost ground.
Oil is highly fungible. Once a barrel leaves the loading port and changes hands a few times, its origin becomes less visible to the end user. Refineries care about quality, price and reliability more than political branding. That simple commercial reality explains why the map could redraw itself so thoroughly without a corresponding collapse in overall Russian export volumes.
The Resilience of Crude Export Volumes
Despite the embargoes and the price-cap framework, Russian crude exports have held up remarkably well. Volumes sit only around 10 percent below pre-conflict levels according to the latest tracking. That is not the kind of contraction many early forecasts predicted. The system adapted.
A large portion of those barrels now moves on vessels operating outside traditional Western financing and insurance channels. Estimates put the share of this so-called shadow fleet at roughly 61 percent of current Russian crude loadings. These ships sail under different flags, carry different coverage and call at ports willing to handle the cargo. The arrangement is imperfect and sometimes costly, yet it has proven durable enough to keep product moving.
It is worth noting that the restrictions themselves remain jurisdictional rather than universal. Countries that never adopted the measures continue to trade freely. That structural feature of the sanctions architecture helps explain why redirection proved more effective than absolute volume reduction.
Refined Products Tell a Different Story
While crude exports stayed resilient, the picture inside Russia looks more strained. In recent months the country has started importing meaningful volumes of refined petroleum products. For a nation long known as one of the world’s largest exporters of diesel, fuel oil and naphtha, that reversal stands out.
Damage to domestic refining capacity has forced the shift. The result feeds into global product balances and has contributed to keeping gasoline prices elevated in many markets. Crude can still leave the country and find buyers. Finished fuels are harder to replace when local plants face repeated disruption.
This contrast between crude resilience and product tightness is one of the more interesting aspects of the current situation. It shows that pressure on infrastructure can bite even when seaborne crude trade continues. Markets feel the difference in the refined barrel more than in the raw one.
What the Data Reveals About Market Fungibility
Perhaps the most interesting aspect is how cleanly the numbers illustrate oil’s fungible nature. When one set of buyers steps away, another set steps forward if the price and logistics allow it. The physical molecules do not disappear. They simply travel different routes and arrive at different discharge ports.
China’s increased share of Russian mineral fuels displaced other suppliers rather than adding to overall Chinese demand in a one-for-one way. India’s sharp rise in Russian crude came alongside declines from traditional African and Middle Eastern sources. The global supply map redistributed itself. Total barrels available to the world market stayed closer to previous levels than many had expected.
The most visible effect of the restrictions on Russia’s oil exports seems to have been to redistribute the global supply of oil.
That observation captures the practical outcome better than many more dramatic forecasts did. Policy can change ownership and shipping patterns. It is harder to erase the underlying resource from the system when alternative buyers and alternative logistics exist.
Shadow Fleet Mechanics and Their Limits
The rise of vessels operating outside conventional Western systems has drawn plenty of attention. These tankers reduce the reach of insurance and financing restrictions. They also introduce higher operational risk, older tonnage in some cases, and more opaque ownership structures. Still, the fleet has scaled up enough to support the bulk of current Russian crude movements.
In my view the existence of this parallel shipping capacity was underappreciated in early assessments of how effective volume restrictions would prove. Markets find workarounds when the economic incentive is large enough. The shadow fleet is one such workaround, imperfect yet functional.
At the same time the arrangement is not costless. Higher freight rates, longer voyages in some cases, and occasional enforcement actions all add friction. That friction shows up in the discount Russian barrels often trade at relative to other grades. Buyers capture part of that discount. Producers absorb the rest. The trade continues.
Broader Implications for Global Energy Balances
The redirection carries consequences beyond the bilateral Russia-buyer relationship. Traditional suppliers into China and India lost market share. Some of those barrels had to find homes elsewhere or face temporary overhang. European refiners adjusted their crude slates toward other sources, sometimes at higher cost or with different quality characteristics.
Product markets feel the refining disruptions more directly. When a major exporter of diesel and other middle distillates begins importing instead, the global product balance tightens. That pressure has helped keep gasoline and diesel prices elevated even when crude benchmarks have moved in different directions at times.
Looking ahead, the sustainability of the current pattern depends on several variables. Enforcement intensity around the shadow fleet, the durability of Asian demand, the pace of any further infrastructure damage, and the willingness of third countries to continue intermediate roles all matter. None of those factors is fixed.
Key Takeaways From the Latest Tracking
- European share of Russian crude collapsed from nearly half to a few percent
- China, India and Turkey now account for the large majority of export destinations
- Overall crude export volumes remain only modestly below pre-conflict levels
- A majority of loadings now move on vessels outside traditional Western systems
- Russia has shifted from net refined product exporter toward importer status in recent months
- The primary visible effect has been redistribution of supply rather than large absolute reduction
These points sit together as a coherent picture. Policy changed the map of buyers. Commercial and logistical adaptation kept the barrels moving. Infrastructure pressure created a different kind of constraint on the product side.
Why the Story Continues to Evolve
Markets never stand still. Fresh data on loadings, vessel tracking and import statistics will keep refining the picture. Seasonal demand shifts, refinery maintenance schedules and any new policy measures can alter the flows again. The current configuration looks durable for now, yet durability in oil markets is always provisional.
One element that stands out to me is the speed of the commercial response. Within a relatively short period the trade routes realigned. That speed says something about both the flexibility of the physical market and the limits of any single set of restrictions when alternative demand centers exist and are willing to expand purchases.
At the same time the product-side tightness reminds us that not every part of the energy system adapts equally well. Crude can move on different ships to different ports. Sophisticated refining capacity is harder to replace quickly when it faces repeated disruption. That asymmetry is now part of the global balance.
Putting the Numbers in Perspective
It helps to step back from the daily noise. Russian crude still reaches the world market in large quantities. The buyers have changed. The shipping arrangements have changed. The price at which the barrels clear has adjusted. The molecules themselves continue to be refined into fuels and feedstocks somewhere.
For energy analysts and market participants the lesson is familiar yet worth restating. Oil markets are deep, adaptive and global. Policy can raise costs, alter routes and shift margins. Removing large volumes from the system permanently is a higher bar, especially when major consuming nations remain outside the restrictive framework.
The latest tracking simply makes that reality visible in clearer numbers than before. Europe’s role shrank. Asia’s role expanded. Volumes held up better than many anticipated. Product markets absorbed a different kind of pressure. The redistribution is the story that the data most clearly supports.
Looking at the Wider Context
Energy security conversations often focus on supply risk from particular producers. The current episode shows another side of the same coin: demand security for producers and the ability of large consuming nations to expand their purchases when discounted barrels become available. Both sides of the market responded to the new incentives.
China and India in particular demonstrated the capacity to absorb additional volumes and to adjust their supplier mix accordingly. Turkey’s role as both buyer and potential intermediate point adds another layer of flexibility to the overall system. These commercial choices collectively underwrote the resilience of Russian export volumes.
Meanwhile European refiners and consumers adapted by sourcing elsewhere. The transition carried costs and required changes in crude quality handling and logistics. Yet the system continued to function. That dual adaptation on both the selling and buying sides is what allowed the redistribution to occur with relatively limited net impact on global crude availability.
Practical Considerations for Market Watchers
Anyone following these flows closely will want to keep an eye on several indicators. Weekly and monthly loading data by destination remain the primary signal. Vessel tracking that distinguishes conventional and alternative fleets provides another layer. Import statistics from the major Asian buyers offer confirmation from the demand side. Product import numbers into Russia itself help gauge the severity of refining constraints.
Price differentials between Russian grades and other medium sour crudes also carry information. Wider discounts can signal either weaker demand, higher logistical costs, or increased enforcement risk. Narrower discounts may point the other way. Those spreads move with the underlying physical and policy conditions.
In my experience the combination of volume data, destination shares and price signals usually gives a more reliable read than any single number. The current episode is no exception. The pieces fit together into a coherent, if still evolving, picture of redirected rather than eliminated supply.
Final Observations on Adaptation and Limits
Markets adapt. That statement is almost a cliché, yet the data on Russian oil destinations and volumes give it concrete form. Buyers changed. Shipping arrangements adjusted. Export volumes declined only modestly. At the same time refining capacity faced real pressure and product balances tightened as a result.
The episode underscores both the reach and the boundaries of jurisdictional measures in a global commodity market. Reach is clear in the collapse of direct European purchases and the rise of alternative logistics. Boundaries appear in the continued movement of barrels to willing buyers and the incomplete nature of any volume reduction.
As fresh data continues to arrive, the precise percentages will shift. The broader pattern of redistribution looks set to remain the dominant theme for some time. Understanding that pattern, rather than expecting a simple disappearance of supply, offers a clearer guide to how energy markets are actually functioning under the current constraints.
The numbers keep updating. The underlying commercial logic stays consistent. Oil finds a way when demand and logistics permit it. That is the practical takeaway from the latest tracking of who is buying Russian oil today.