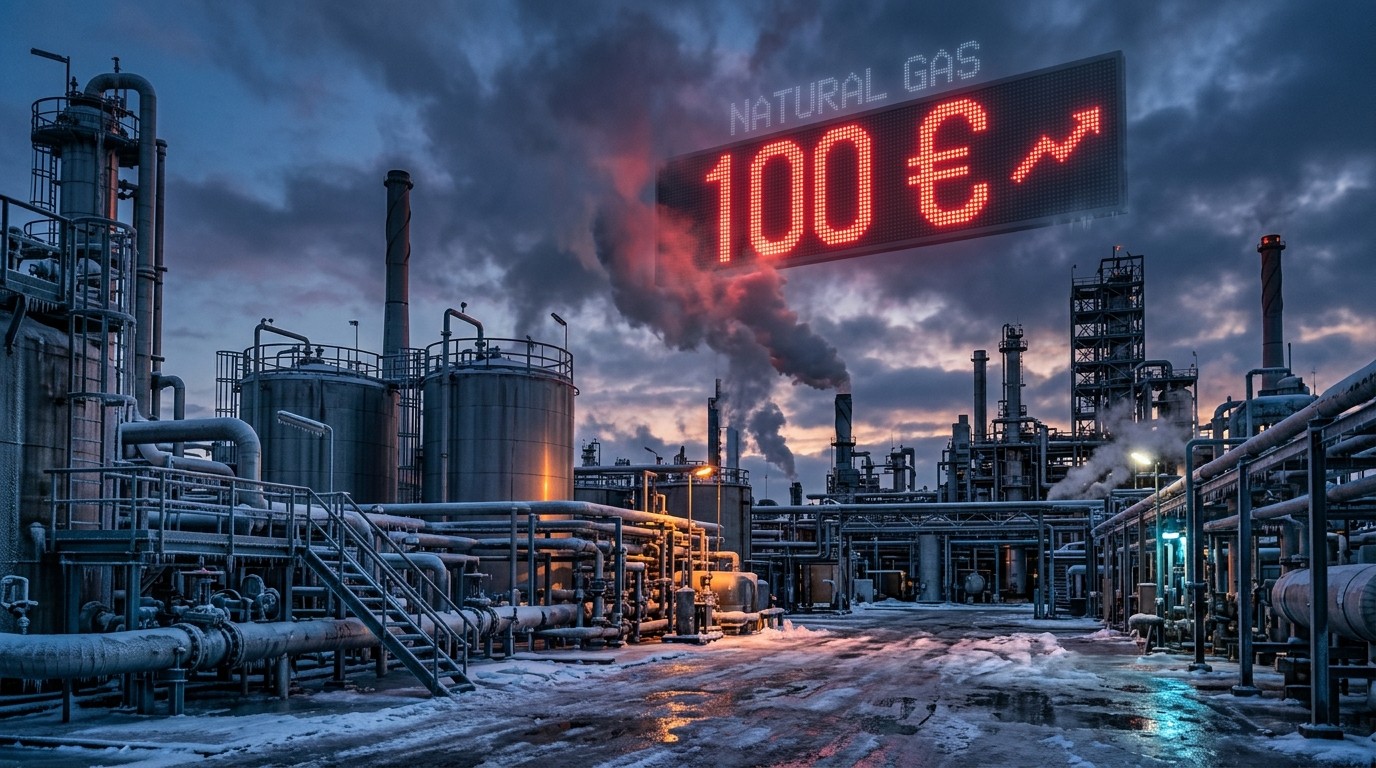

Have you ever watched an energy market cross a round number and felt that quiet shift in the atmosphere? That is exactly what happened when European natural gas futures pushed through the 100-euro mark. It was not just another price tick. It felt like a warning light flashing on the dashboard of an entire continent preparing for winter.
Why Crossing 100 Euros Matters Right Now
Benchmark TTF contracts climbed as much as 4.1 percent in a single session and settled firmly above 100 euros per megawatt-hour. The last time prices lived in that territory for any meaningful stretch was late 2022. Back then the continent was still reeling from abrupt supply changes. Today the drivers look different yet the nervousness feels familiar.
I have followed these markets long enough to know that round numbers often act as psychological magnets. Traders talk about them in meeting rooms and on trading floors. Once the level is breached, positioning can shift quickly. Some participants take profits. Others see confirmation that the next leg higher is already underway. Either way, the conversation changes.
Storage Levels Tell a More Worrying Story
The real concern sits underground. European storage facilities currently hold about 75 percent of capacity. Compare that with the ten-year average near 90 percent for this point in the calendar and the gap becomes obvious. Last week inventories registered their first net decline of the year. That timing matters. Withdrawal season has begun earlier than many operators preferred.
When stockpiles start the cold months thinner than usual, every degree below seasonal norms carries extra weight. A cold blast is already forecast for parts of continental Europe early next month. Households will turn up the heat. Power plants will burn more gas to meet electricity demand. Industrial users who managed to delay some consumption may suddenly find themselves competing for the same molecules.
In my view the storage deficit is the single most important number on the board right now. Prices can spike and retreat. Storage, once drawn down, takes time and favorable weather to rebuild. That lag creates lasting vulnerability.
The Transatlantic Price Divide Keeps Widening
While Europe frets, the United States continues to enjoy relative calm. US natural gas remains near 2.77 dollars per million British thermal units. Convert the European price into the same unit and the multiple stands at roughly 11.8 times. That gap is not a small arbitrage opportunity. It is a structural signal.
Ample domestic production and mild weather linked to El Niño have kept American inventories comfortable. Europe, by contrast, relies heavily on seaborne LNG and remaining pipeline flows. Any disruption to those routes shows up almost immediately in the TTF contract. The result is a persistent premium that European manufacturers and consumers must absorb.
I keep coming back to that multiple. Eleven or twelve times the US price is not sustainable for energy-intensive industries over the long term. Some plants have already cut operating rates. Others are exploring permanent relocation of capacity. The price signal is loud and clear.
Geopolitical Shadows Over the Strait of Hormuz
Supply worries are not limited to European storage. Disruption risks around the Strait of Hormuz continue to hover in the background. A meaningful share of global LNG still passes through that corridor. Even partial interruptions can tighten the available cargo pool for Europe just when demand is rising.
Market participants are watching political developments closely. One analyst recently noted that the geopolitical situation remains fluid and that relatively small changes could push European prices higher still. The upcoming political calendar in the United States adds another layer of uncertainty that traders must price in.
Perhaps the most interesting aspect is how quickly sentiment can flip. A single cargo diversion or a weather forecast revision can move the entire curve. Liquidity is present, yet the market feels thinner than it did a few years ago when more pipeline options existed.
What Analysts Are Saying About the Path Ahead
Some energy research desks have sketched scenarios that reach 150 euros per megawatt-hour by year-end. Those projections rest on two conditions: LNG exports from the Persian Gulf remaining constrained near 25 percent of normal levels and a winter that turns out one standard deviation colder than average. Neither outcome is guaranteed, yet both are plausible enough to keep risk premiums elevated.
€100 is no doubt a psychological mark and could provide some resistance to further gains. With the geopolitical situation changing so much at the moment, it will not take much to move European gas prices even higher.
That assessment captures the mood well. Resistance may appear near the round number, but the underlying balances still look tight. If temperatures drop faster than expected, the market will test how much incremental supply can be attracted on short notice.
How Households and Industry Are Feeling the Pressure
For ordinary families the impact arrives through heating bills and electricity tariffs. Many retail contracts still carry lagging price adjustments, so the pain is not always immediate. Over the coming months, however, higher wholesale levels will feed through. Governments that offered support schemes during earlier crises face tighter budgets this time around.
Industrial users face a sharper choice. Some can switch to alternative fuels when the spread justifies the conversion costs. Others cannot. Continuous process industries such as chemicals and metals simply absorb the higher input cost or reduce output. I have spoken with operators who describe the current environment as a slow squeeze rather than a sudden shock. The effect is still real.
- Higher wholesale gas feeds into power generation costs within days
- Retail heating bills typically adjust over several months
- Energy-intensive factories review production schedules weekly
- Governments monitor social support budgets more carefully
The cumulative effect is a quieter form of economic pressure. Growth forecasts already contain cautious assumptions about energy costs. Another leg higher would force revisions.
Comparing Today with the Crisis of 2022
It is tempting to draw direct parallels with the extreme prices seen four years ago. The comparison only goes so far. In 2022 the continent faced abrupt pipeline reductions and scrambled to fill storage from near-empty levels. Today storage starts lower than average yet still contains a meaningful buffer. LNG import capacity has expanded. Demand destruction lessons from the previous episode remain fresh in the minds of large consumers.
Still, the psychological mark of 100 euros revives memories. Risk managers who lived through that period keep tighter contingency plans. Some utilities have increased their contracted LNG volumes earlier in the season. Others have layered in weather derivatives. The toolkit is broader now, yet the fundamental exposure to cold weather and seaborne supply has not disappeared.
In my experience markets rarely repeat the exact same path. They rhyme. The rhyme this winter is a thinner safety margin combined with elevated geopolitical noise.
Weather Forecasts Move Markets Faster Than Fundamentals
Short-term weather models have become some of the most closely watched data releases in the European gas complex. A forecast that adds several heating degree days across Germany, France and the Benelux region can lift the prompt contract within hours. Conversely, a milder outlook can trigger rapid profit-taking.
The early-November cold snap currently on the charts is therefore more than a meteorological curiosity. It is a potential catalyst. If the cold air settles and persists, storage withdrawals will accelerate. If the pattern breaks earlier than expected, the market may find temporary relief. Either outcome will be priced almost in real time.
I find it striking how weather has reclaimed center stage. A decade ago pipeline flows and long-term contracts dominated the conversation. Today the Atlantic weather pattern and the availability of floating LNG cargoes often matter more on a day-to-day basis.
Possible Scenarios for the Rest of the Heating Season
Several paths remain open. A mild winter combined with steady LNG arrivals could allow prices to drift lower and storage to stabilize. That outcome would feel like a soft landing. A normal winter with occasional cold spells would likely keep prices elevated but contained near current levels. The more stressful path involves a colder-than-average season plus any interruption to LNG flows. Under those conditions the 150-euro zone discussed by some desks becomes a live possibility.
None of these scenarios is locked in. Markets will reassess weekly as temperature forecasts and shipping data arrive. What feels certain is that the margin for error is thinner than it was twelve months ago.
| Scenario | Weather Assumption | Likely Price Range |
| Soft Landing | Milder than average | Below 90 euros |
| Base Case | Near seasonal norms | 90-120 euros |
| Stressed Case | Colder plus supply hiccup | Above 130 euros |
The table is illustrative rather than predictive. Real outcomes will depend on the interaction of weather, shipping and residual demand destruction.
Longer-Term Questions Europe Must Answer
Beyond this winter the continent faces structural choices. How much additional LNG import capacity makes economic sense once demand growth moderates? What role should domestic production and alternative low-carbon gases play? How quickly can industry adapt to structurally higher energy costs relative to other regions?
These questions do not lend themselves to quick answers. They require investment decisions measured in years rather than months. The current price spike simply brings the underlying issues back into public view.
I have found that energy transitions rarely proceed in straight lines. Periods of tightness serve as reminders that reliability still matters. The market is delivering that reminder once again.
Practical Steps Market Watchers Are Taking
Portfolio managers and corporate treasury teams are not sitting idle. Many have increased the frequency of storage and weather reviews. Some have adjusted hedge ratios earlier than usual. Others are exploring longer-dated contracts to lock in visibility even at elevated levels.
- Monitor weekly storage reports more closely than last year
- Track Atlantic weather models on a daily basis
- Review exposure to prompt versus seasonal contracts
- Stress-test budgets against a 150-euro outcome
- Maintain dialogue with LNG suppliers on flexibility options
None of these steps eliminates risk. They simply improve preparedness. In a market where sentiment can shift on a single forecast revision, preparation is the practical edge available to most participants.
The Human Element Behind the Numbers
It is easy to treat natural gas as an abstract commodity. Behind every price movement sit real decisions by households deciding whether to turn the thermostat down, by plant managers calculating whether a production run still makes sense, and by policy makers weighing support measures against fiscal constraints.
When prices cross a psychological threshold the conversation in those kitchens, control rooms and ministries changes. That human layer is what ultimately gives the market its force. Charts and storage percentages matter, yet the collective response of millions of individual decisions shapes the path from here.
Looking ahead, the next few weeks will reveal whether the 100-euro level becomes a temporary peak or a new floor. Weather holds the strongest short-term influence. Geopolitics and shipping remain the wild cards. Storage levels provide the underlying constraint that will not disappear until spring.
For now the market has delivered a clear message. Europe enters the heart of the heating season with less cushion than usual and with prices already elevated. How the continent navigates the coming months will depend on a combination of luck with the weather and skill in managing the available supply. Both will be tested.
The story is still unfolding. Every fresh weather map and every storage update will add another chapter. Those who stay attentive to the details will be better placed to understand the next move when it arrives.